Florida Special Needs Trust Distributions: What the Trust Can and Cannot Pay For
What a special needs trust can pay for in Florida depends on four things: the trust document, whose money funded the trust, the benefits the beneficiary receives, and how the payment is made. There is no universal list of approved expenses. A Florida special needs trust, also called a supplemental needs trust, may pay for goods and services that improve a beneficiary’s daily life, but a payment can be permitted by the trust and still affect a benefit.
Before authorizing a distribution, the trustee needs to check the trust’s terms, whose money funded it, the beneficiary’s current benefits, and how the payment will be made. This guide to special needs trust distributions in Florida addresses spending from an existing trust: the expense-by-expense review, what the trust cannot pay for, food and shelter under the current SSI rules, cars and homes, cards and reimbursements, caregivers and travel, ABLE accounts, and the records a trustee should keep. For the broader planning framework, see the Florida special needs trust guide.
Lorenzo Law offers a free initial consultation about Florida trust administration. Consultations are available in English and Spanish. Only the initial consultation is free; the scope and fee for legal work are confirmed separately.
Request a free initial consultationCall (305) 224-6811
Trustees · Beneficiaries · Families · Allowable expenses · Food and shelter · Cards and reimbursements · ABLE accounts · English and Spanish · Statewide
| Two separate questions | Whether the trust permits a payment and how that payment affects a benefit are different questions. A payment can be allowed by the trust and still reduce SSI. |
|---|---|
| Trust and money source | First-party, third-party and pooled arrangements have different rules. The name on the document does not establish whose assets funded it. |
| Food | Since September 30, 2024, food a trust buys directly is not counted as in-kind support and maintenance for SSI. Cash given to buy food is analyzed separately. |
| Shelter | Rent, mortgage payments and specified household costs can still reduce SSI when a trust pays them, but not always by the same amount. |
| Cash and cards | When a trust’s principal is not countable, cash paid directly to an SSI recipient is generally income. A card’s ownership and cash access matter more than its marketing. |
| Records | Keep the request, the authorizing provision, the invoice, proof of payment and the benefit information used for every material distribution. |
What Changed for Special Needs Trust Distributions
The “new rules for special needs trusts” that matter for distributions are the dated changes below. They concern SSI payment treatment, ABLE eligibility and a trustee’s powers under Florida law, and they do not create a universal list of approved expenses.
| Date and type of change | Change | What it means for a trustee |
|---|---|---|
| September 30, 2024 | Social Security stopped counting food in its in-kind support and maintenance calculation for SSI, the SSI food rule change (SSA EM-24048). | Groceries or meals a trust buys directly should not be described as an automatic SSI reduction. Cash for food and shelter payments are separate questions. |
| January 17, 2025: revised guidance for rules effective September 30, 2024 | Social Security issued revised implementation instructions for other September 30, 2024 living-arrangement changes (SSA EM-24047 REV). | Shelter valuation depends on the living arrangement. Do not assume every shelter payment causes exactly a one-third reduction. |
| June 20, 2025: Florida statute amendment | Chapter 2025-159 amended Florida’s trust decanting statute, section 736.04117, to let a qualifying trustee decant by modifying the terms of the existing (first) trust in place, rather than only by appointing its principal to a new second trust. The statute’s definition of a “beneficiary with a disability” predates this amendment. | Decanting is a separate power with its own requirements. It can matter when a trustee considers moving assets of an existing trust into a special needs trust. |
| January 1, 2026 | The ABLE disability-onset age threshold expanded to before age 46 (SSA ABLE guidance). | More beneficiaries may qualify for an ABLE account. The threshold refers to when the qualifying condition began, not the person’s age when opening the account. |
These changes do not automatically amend a particular trust or resolve every benefits program’s treatment. Any use of the amended trustee powers requires its own legal review.
Special Needs Trust Distribution Rules: What the Trustee Should Check Before Paying
These special needs trust distribution guidelines give a trustee the same starting point for every request. Start with the actual request: what is being purchased, for whom, at what price, and who will receive the money or own the property afterward. Then work through these questions.
- Does the trust authorize it? Read the distribution provisions, restrictions, amendments and any relevant court order. Identify who has authority to approve the payment. A caregiver’s request is not itself a trustee decision. If a guardianship court approved the trust or its funding, check the order; see Florida adult guardianship.
- Which trust and funds are involved? Identify first-party, third-party or pooled funds, and keep their treatment separate. The name on the document does not establish whose assets funded it.
- Which benefits does this person receive? Use current award and eligibility notices. Record SSI, Medicaid and its coverage category, SSDI, Medicare, housing assistance and any other assistance separately.
- What is the payment route? A provider invoice, cash to the beneficiary, a reimbursement, a credit-card bill and a transfer to an ABLE account can raise different issues.
- What records and review are needed? Document the purpose, price, beneficiary’s needs, ownership, expected benefit effect and any required approval before committing funds.
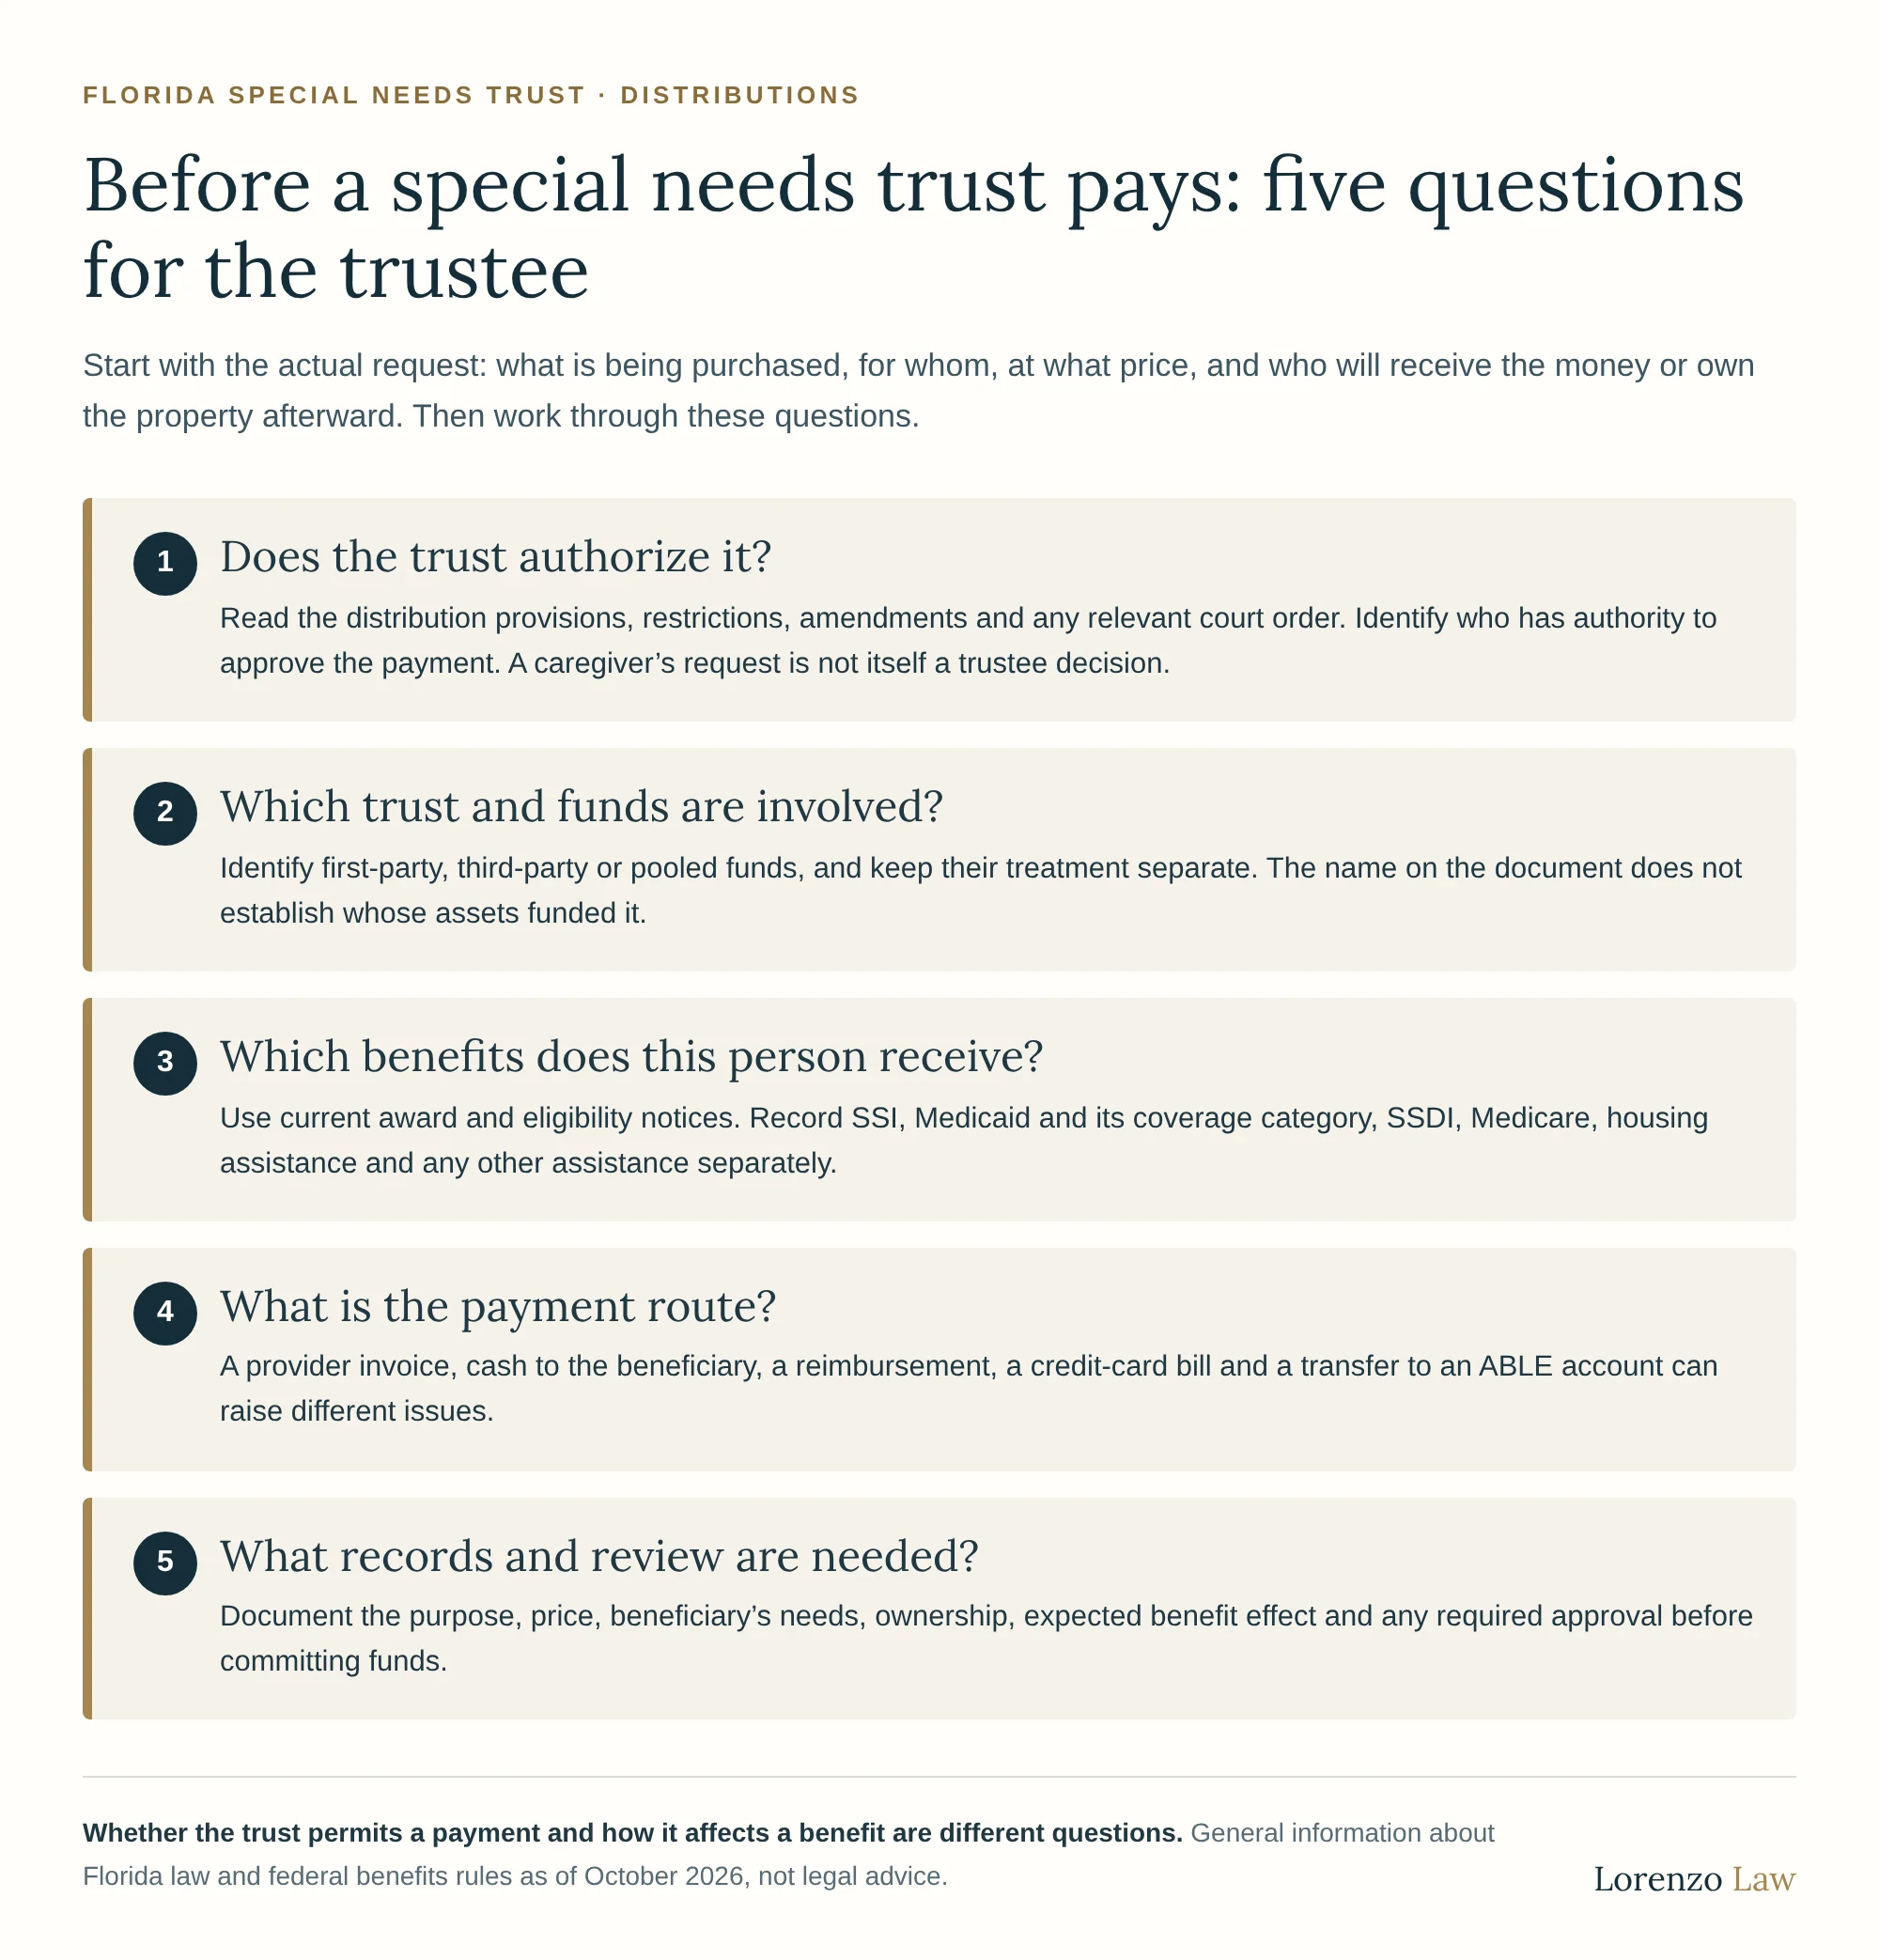
View the “Before a special needs trust pays: five questions for the trustee” chart (zoom in to read; the details are also in the list above).
Florida trustees must administer a trust in good faith under its terms and purposes and in beneficiaries’ interests. Even broad discretion is subject to that standard: a trustee must exercise a discretionary power in good faith and in accordance with the trust’s terms and purposes and the beneficiaries’ interests, even if the trust calls the discretion “absolute” or “sole.” A court will not substitute its judgment merely because it would have decided differently, but an abuse of discretion can be reviewed. See Florida Statutes § 736.0801 and § 736.0814. For who should hold that role, see selecting a trustee under Florida law.
Trust Type and Source of Funds Affect Distribution Decisions
The three common types of special needs trusts, first-party, third-party and pooled, are funded differently, and the funding source shapes what a trustee may pay and what happens to the money later.
| Arrangement | What the trustee needs to identify | Distribution consequence to review |
|---|---|---|
| First-party special needs trust (self-settled; often called a “d4A” trust) | Assets belonging to the beneficiary, such as settlement proceeds or an outright inheritance; the applicable statutory exception and trust terms | Beneficiary-focused spending, resource treatment, payback provisions and the effect of each payment. Qualification under an exception does not make every distribution benefit-neutral. |
| Third-party special needs trust | Assets supplied by someone else that did not first belong to the beneficiary | The actual distribution standard and beneficiary’s access to funds. What a third-party special needs trust can pay for is set mainly by its terms. Do not add the beneficiary’s own funds without reviewing the resulting treatment. |
| Pooled trust account (often called a “d4C” account) | Master trust, joinder agreement, source of funds and administrator’s procedures | Submit requests through the administrator’s process; a pooled trust’s allowable expenses follow the master trust and the administrator’s policies. A pooled arrangement does not remove benefits review or make age-related transfer issues disappear. |
| Trust created under a will | Will, operative trust provisions and source of the property | “Testamentary” describes how the trust takes effect; it does not supply a separate universal expense rule. |
The federal first-party and pooled-trust exceptions have different requirements. For example, the first-party exception in 42 U.S.C. § 1396p(d)(4)(A) includes an under-65 requirement and Medicaid reimbursement provisions; pooled trusts have a separate exception. Resource exclusions and transfer penalties must be analyzed separately. See Social Security Act § 1917(d)(4), POMS SI 01120.203 and CMS guidance on special needs trusts.
For funds supplied by parents or other relatives, the third-party special needs trust guide explains that planning context, and the pooled special needs trust guide explains how pooled accounts work. This page does not replace a review of the existing trust’s authority.
A Miller Trust (Qualified Income Trust) Has a Different Purpose
A qualified income trust, also called a Miller trust, addresses an income-limit issue in specified Florida Medicaid long-term-care programs. It is an income-only arrangement with its own deposit, payment and patient-responsibility rules. It is not a substitute account for inherited assets or settlement principal, and the expense examples below are not QIT spending instructions. Florida DCF specifically says not to add assets to a QIT. See the Florida DCF QIT information sheet.
Is There a Florida Special Needs Trust Statute?
Florida does not have one comprehensive special needs trust statute. A Florida special needs trust is governed by its own terms, the Florida Trust Code in Chapter 736 of the Florida Statutes, and the federal and state benefits rules that apply to the beneficiary.
The Florida special needs trust rules a trustee meets most often when making distributions are:
- Good-faith administration under the trust’s terms and purposes and in the beneficiaries’ interests (§ 736.0801).
- Limits on discretion, even when the trust grants “sole” or “absolute” discretion (§ 736.0814).
- Separate, accurate records and separation of trust property (§ 736.0810).
- Information and annual accountings for qualified beneficiaries of an irrevocable trust (§ 736.0813).
- Reasonable compensation and the court’s power to adjust it (§ 736.0708).
- Impartiality when a trust has more than one beneficiary, such as remainder beneficiaries: due regard for their respective interests, not identical treatment (§ 736.0803).
- Removal of a trustee by the court, in addition to any removal power the trust itself grants (§ 736.0706).
- Loyalty: administering the trust solely in the beneficiaries’ interests, with transactions involving the trustee’s close family presumed to be conflicts (§ 736.0802).
- Prudent investing and administration (§ 518.11; § 736.0804).
- Remedies for breach of trust, including recovery of a distribution that was too large (§ 736.1001).
On the benefits side, Florida Medicaid eligibility for SSI-related categories is determined by Florida DCF, which publishes its program rules in a manual, and SSI is a federal program administered by Social Security; both are discussed below.
Expense-by-Expense Review: What Can a Special Needs Trust Pay For?
A special needs trust can pay for many goods and services that supplement what public benefits provide, such as uncovered medical and dental care, therapy, equipment, education, recreation, travel, transportation and personal items, when the trust’s terms allow the payment and the trustee has considered its effect on the beneficiary’s benefits. Payment for shelter, cash given to the beneficiary and purchases that create a countable asset need a closer look.
Whether the question is what a special needs trust can be used for, what can be paid out of it, what trust money can be spent on, or what you can buy with it, the answer runs through the same four checks. Lists of permissible distributions, allowable disbursements or allowable expenditures can help a trustee think through a request, but they cannot replace those checks. These are examples for review, not a list of automatically approved expenses. Each row assumes the trustee has first established legal authority and checked the beneficiary’s circumstances. The SSI discussion concerns distributions from a trust whose principal is not a countable resource; different analysis applies when the trust itself is countable.
Special needs trust allowable expenses: review table
| Requested expense | Payment method to review | First question to ask | Benefits or trust issue | Documents to keep |
|---|---|---|---|---|
| Dental, vision or hearing care (such as eyeglasses or hearing aids), therapy or adaptive equipment | Payment to the provider | Does insurance or Medicaid cover any of it? | Confirm coverage, the uncovered cost, trust authority and any ownership issue. A medical label alone does not resolve all programs’ rules. | Invoice, coverage explanation, equipment details and approval |
| Education (such as tuition or tutoring), telephone service or recreation (such as a gym membership or hobby) | Payment to the school or provider | Is the bill itemized? | Often compatible with supplemental spending, but identify bundled charges and anything transferred to the beneficiary. | Itemized bill, purpose and payment record |
| Clothing and personal care | Purchase from the store or provider | Who will receive and own the items? | Clothing is not counted as in-kind support and maintenance for SSI. Confirm the trust’s terms and that the purchase is for the beneficiary. | Receipt and purpose |
| Internet service, a computer or other electronics | Payment to the provider or seller | Is the service or device for the beneficiary’s use? | Not among the household costs SSA counts as shelter (POMS SI 00835.465). A device becomes the beneficiary’s property; consider its value and the trust’s terms. | Account statement or receipt, device details |
| Furniture and household goods | Purchase from the seller | Who else in the household will use it? | Review sole-benefit rules where they apply and whether the item is for the beneficiary’s home. | Receipt, delivery address and purpose |
| Groceries or restaurant meals | Direct purchase of food | Is the trust buying the food, or giving cash? | Food has been excluded from SSI’s ISM calculation since September 30, 2024. Cash given to buy food needs a separate income analysis. Other benefits still require review. | Receipt identifying food and any nonfood items |
| Rent, mortgage or household utilities | Payment to landlord, lender or utility | What is the living arrangement, and is the SSI effect worth it? | Shelter assistance can affect SSI even when paid directly. Review living arrangements, the charge and applicable valuation rules. | Lease or mortgage, itemized bills and household contribution records |
| Property taxes, homeowners insurance, condominium fees and repairs | Payment to the county, insurer, condominium association or contractor | Who owns the home, and which costs count as shelter? | Real property taxes, and property insurance required by a mortgage holder, are household costs SSA counts as shelter. Condominium fees in themselves are not, though identifiable charges inside them, such as garbage removal, can be. Review repairs separately. | Tax bill, policy, association statement, contract |
| Moving costs | Payment to the moving company | Will the new residence change the living arrangement? | The move itself is usually a supplemental expense; the new home’s rent or ownership costs need their own review. | Estimate, invoice, new lease or deed |
| Vehicle, including a wheelchair-accessible vehicle, or accessible transportation | Vendor payment with an ownership plan | Who will hold title, and is there already a vehicle? | Check existing vehicles, use, title, insurance and resource exclusions; purchasing another vehicle is not automatically excluded. | Quote, title plan, insurance and transportation need |
| Auto insurance, fuel and repairs | Payment to the insurer, station account or shop | Is the vehicle used for the beneficiary’s transportation? | Pay vendors rather than giving cash where practical. Review who owns the vehicle and who else uses it. | Policy, receipts, repair invoice |
| Home purchase or home modifications for accessibility, such as ramps | Payment under a reviewed purchase or construction arrangement | Purchase, ongoing costs or modification? | A home purchase, recurring shelter bills and modifications can have different SSI treatment. Review title, occupancy, other residents and long-term costs. | Contract, title review, budget and occupancy details |
| Caregiver services or an accompanying traveler | Payment under a documented service or travel arrangement | Is the service or companion needed because of the beneficiary’s condition? | Review services, reasonable compensation, conflicts and applicable sole-benefit rules. A family relationship does not alone qualify or disqualify the payment. | Service agreement, time records, itinerary and assistance needed |
| Care management, advocacy, legal and accounting fees | Payment to the professional | Does the service benefit the beneficiary or the trust’s administration? | Many trusts authorize professional services. Review the trust’s terms and whether the fee is reasonable. | Engagement letter, invoice, purpose |
| Pet care | Payment to the veterinarian or supplier | Do the trust’s terms permit it, and is the pet the beneficiary’s? | Treated like other personal expenses: authority and benefit to the beneficiary first. | Invoice and purpose |
| Life insurance premiums | Payment to the insurer | Who owns the policy, whose life is insured, and who is the beneficiary? | A policy the beneficiary owns can have cash surrender value that counts as a resource (20 C.F.R. § 416.1230). Premiums for a policy that benefits someone else raise sole-benefit questions in trusts subject to them. | Policy, ownership and beneficiary designation, premium notices |
| Funeral or burial planning | Payment to the funeral provider under a written plan | Is this a prepaid plan during life, or a bill after death? | Prepaid arrangements made during the beneficiary’s life are reviewed differently from costs after death; a first-party trust’s reimbursement provisions matter after death. | Contract, plan terms, trust provision |
| Gift cards and cash equivalents | Review before buying | What can the card be used to buy? | A gift card that can buy food or shelter, or can be resold, is generally SSI income in the month received, and an unspent balance can be a resource the next month. A gift card is not in-kind support, so the September 2024 food exclusion does not cover it. | Receipt, card terms, how it was used |
| Reimbursement or credit-card payment | Review the original expense and recipient before paying | Who originally paid, and for what? | Separate reimbursement to a third party from cash paid to the beneficiary. Itemized charges matter; changing the payment route does not erase the underlying expense. | Original receipts, proof of payment and itemized statement |
SSA’s trust-disbursement guidance addresses payment methods and property received. Read its older food references with the later food-rule update. For applicable sole-benefit and accompanying-traveler rules, see POMS SI 01120.201 F.
What Can a Special Needs Trust Not Pay For?
It depends on the trust’s terms and on whose money funded it. Many lists of special needs trust prohibited expenses, and generic special needs trust spending rules, confuse two different things: a payment the trust does not allow, and a payment the trust allows that may reduce a benefit. Food and shelter are not automatically prohibited.
A trustee should decline or get advice before making these payments:
- Payments the trust document forbids or does not authorize. The trust’s distribution standard controls first. Some trusts limit spending to specific purposes; others give broad discretion.
- Payments for someone else’s benefit in a trust subject to sole-benefit rules. Another person’s incidental benefit is different from using trust assets to make gifts to that person.
- Cash handed to an SSI recipient without analysis. When the trust’s principal is not countable, cash paid directly to its SSI beneficiary is generally unearned income, and money the beneficiary holds onto can later count toward the SSI resource limit.
- Purchases of property that is not excluded for SSI. A noncash item the beneficiary receives may count as income in the month received and as a resource afterward. Check both stages before paying the vendor.
- Services a program already covers. Verify what Medicaid or another program covers before paying privately for the same care.
- The beneficiary’s legal support obligations or the trustee’s own expenses. These raise trust-law and conflict questions; see the sole-benefit and conflict points below.
A payment that may reduce SSI is not automatically forbidden. If the trust permits it, the trustee may decide that the beneficiary’s housing, safety or health need outweighs the benefit reduction, and document why.
Food and Shelter Receive Different SSI Treatment
For a special needs trust and SSI, the rule behind most shelter questions is in-kind support and maintenance (ISM): support someone else provides in kind, which can reduce an SSI payment. Since September 30, 2024, food is no longer counted in the ISM calculation; shelter still is.
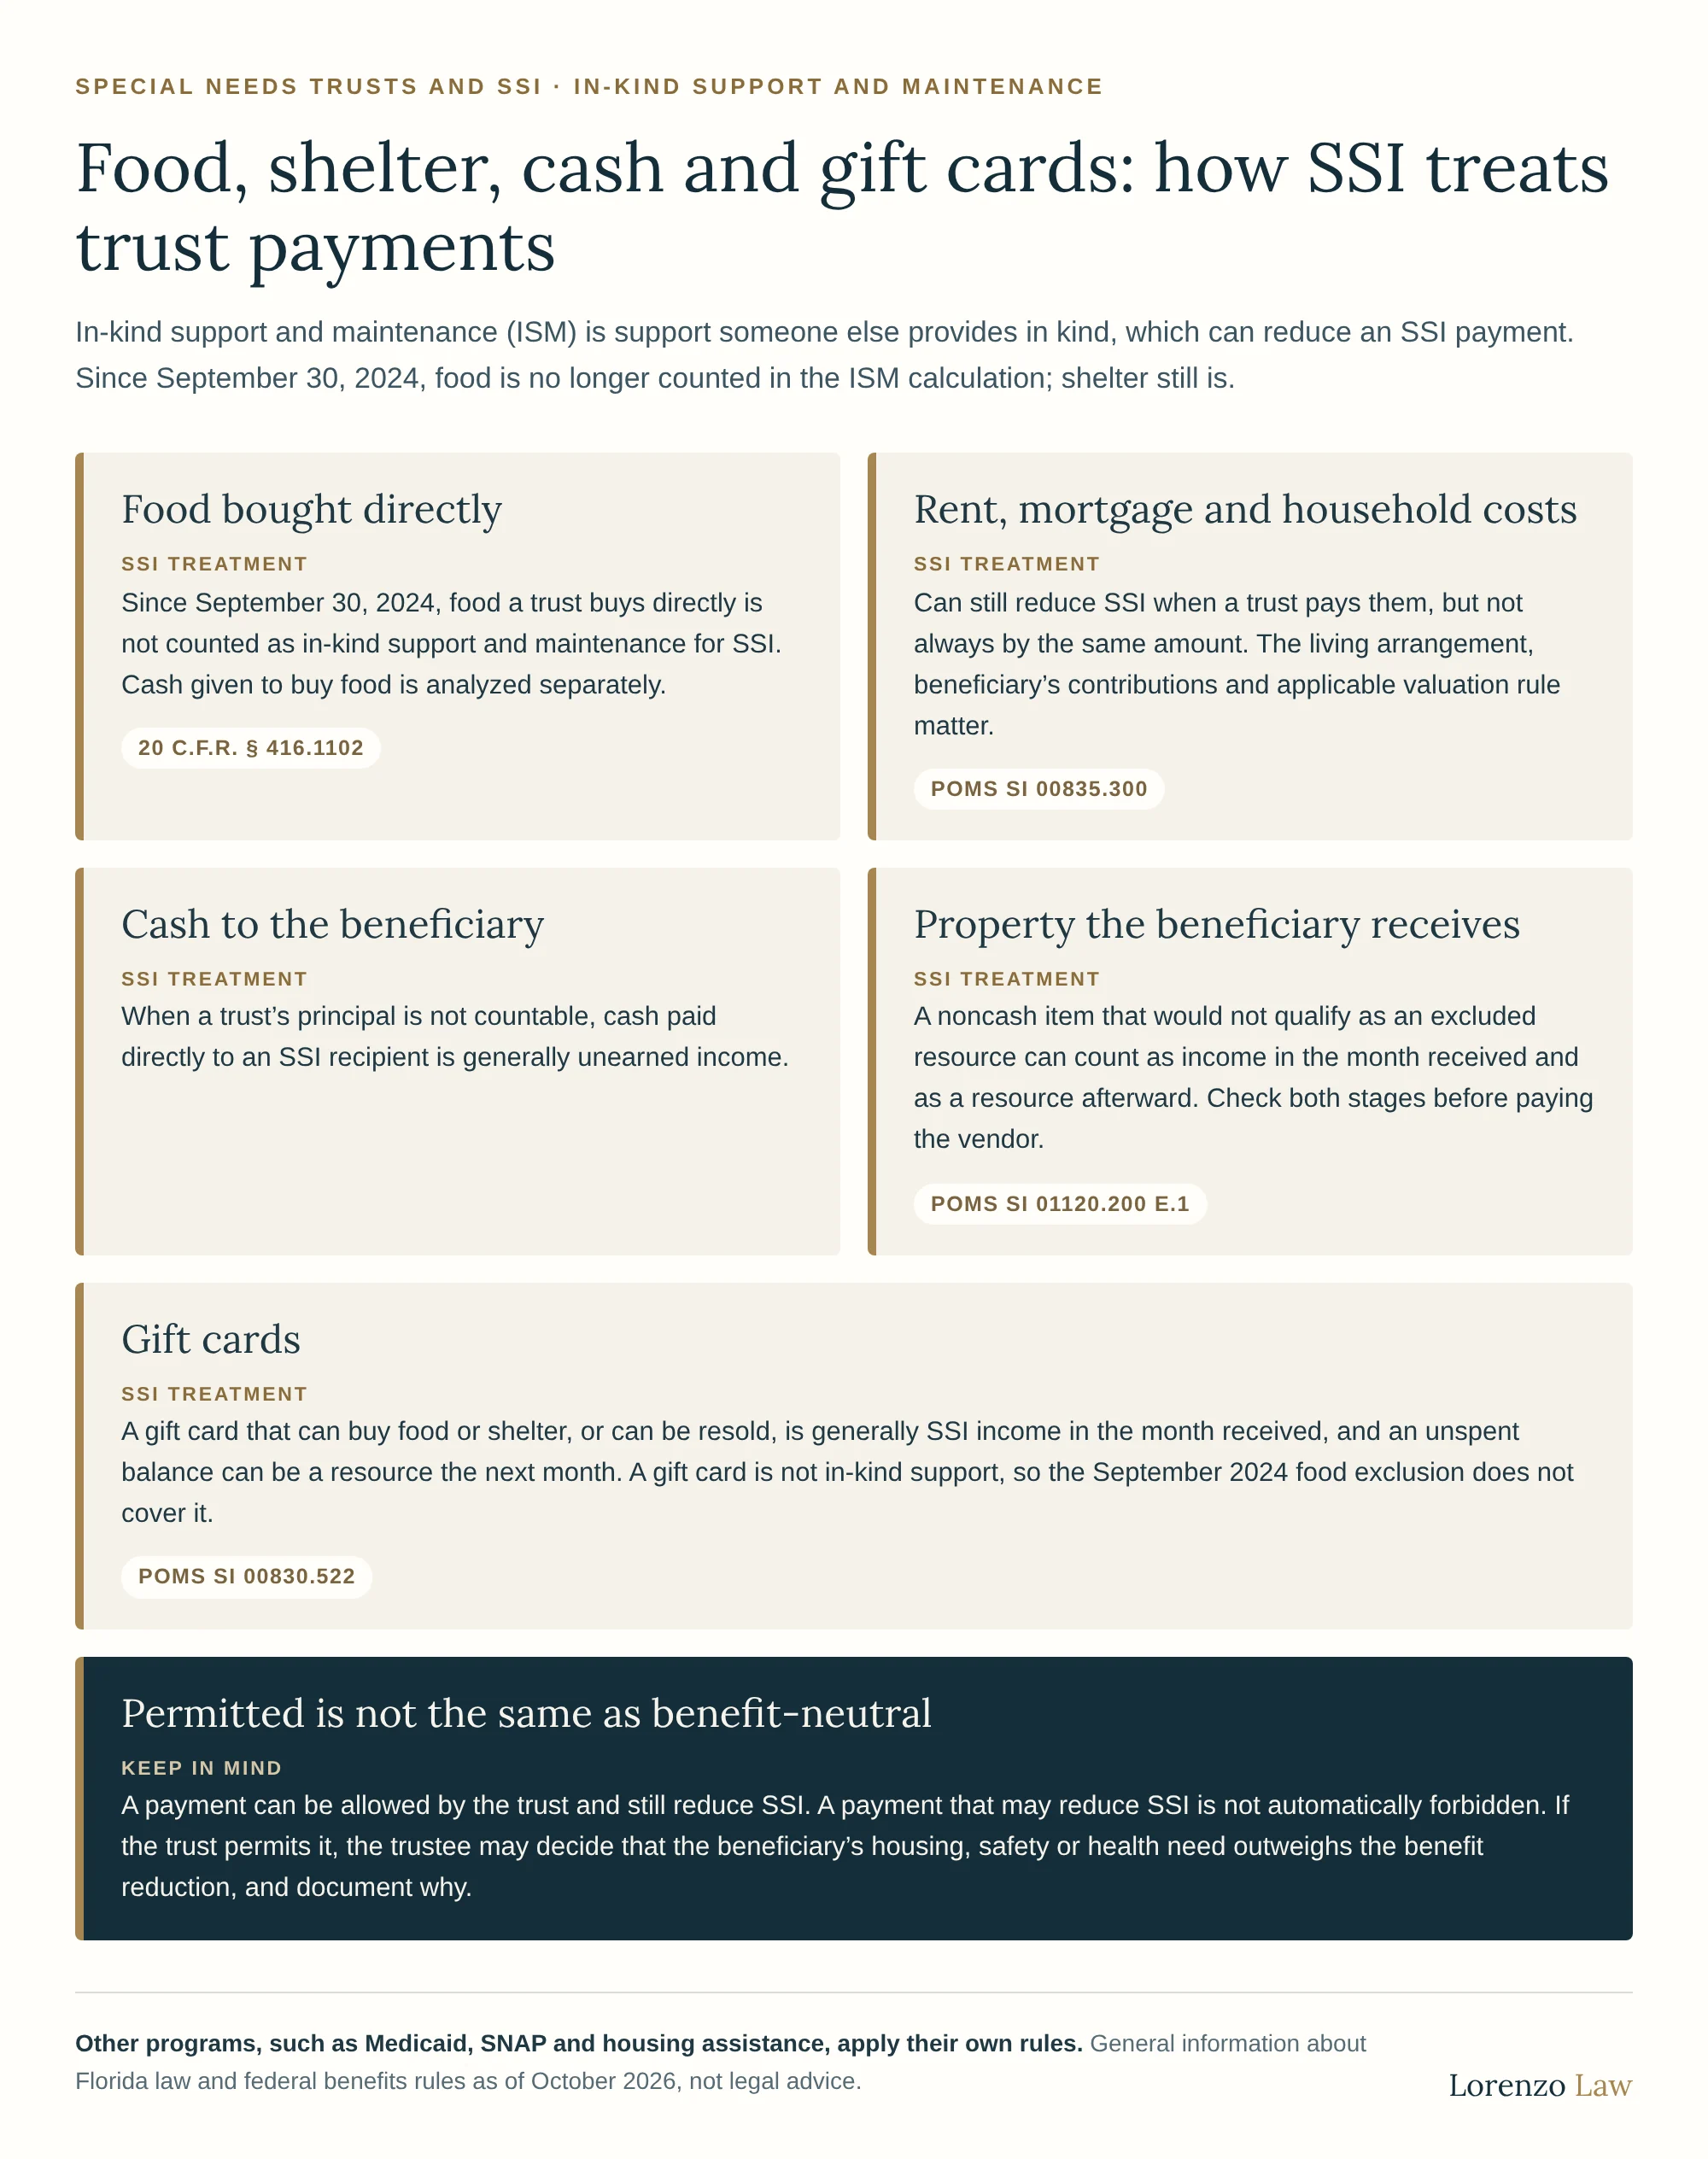
View the “Food, shelter, cash and gift cards: how SSI treats trust payments” chart (zoom in to read; the details are also in the text above).
Can a special needs trust pay for food or groceries?
Yes, if the trust permits it. Effective September 30, 2024, SSA stopped including food in its in-kind support and maintenance calculation (20 C.F.R. § 416.1102). A trust’s purchase of groceries or a meal therefore should not be described as an automatic SSI reduction for food. The change does not turn cash given to a beneficiary into a noncash food purchase, amend a restrictive trust provision, or establish how another benefits program treats the transaction. See SSA EM-24048.
Can a special needs trust pay for rent, a mortgage or utilities?
Often, if the trust permits it, but the payment can reduce SSI. Rent, mortgage payments and specified household costs can still create in-kind support and maintenance, or ISM, for SSI. Do not assume every shelter payment causes exactly a one-third reduction. The living arrangement, beneficiary’s contributions and applicable valuation rule matter under the SSI living arrangement rules. Moving in with someone, or having someone move in, can change the living arrangement too. Trust payments for shelter generally require consideration of the presumed maximum value rule; other household arrangements may involve the one-third reduction rule. See SSA trust guidance, E and F, and the SSA living-arrangement implementation instructions.
The presumed maximum value (PMV) rule caps how much a shelter payment can reduce SSI in a month (POMS SI 00835.300); the exact amount changes with the federal benefit rate, so it is not stated here. Because the reduction is capped, a trust payment covering a large share of rent can sometimes improve the beneficiary’s housing more than it reduces SSI. That is a judgment for the actual numbers.
An SSI effect does not automatically make a payment forbidden under the trust. If the trust permits it, the trustee may need to weigh a documented benefits effect against the beneficiary’s housing and safety needs. That decision requires a review of the actual trust and benefits; this article cannot calculate the tradeoff for a particular person.
Can a special needs trust buy a house or own a home?
A special needs trust can buy and own a house in Florida if the trust allows it, but ownership alone does not settle the benefits question. A trust-owned home requires more than choosing whose name appears on the deed. Review the purchase itself, the beneficiary’s occupancy, mortgage payments, operating expenses, repairs and other residents’ use separately. SSA distinguishes a trust’s home purchase and shelter payments from repairs or accessibility improvements. A trust’s ownership alone is not a guarantee of no SSI effect. See POMS SI 01120.200 F.
After the purchase, plan for the carrying costs. SSA counts real property taxes, and property insurance required by a mortgage holder, as household (shelter) costs; condominium fees in themselves are not, though identifiable charges inside them can be. Repairs and accessibility work are reviewed separately (POMS SI 00835.465). If relatives will live in the home, decide in writing who pays what, because other residents’ use raises sole-benefit and household questions. For deed and homestead questions, get advice before closing.
Whether a special needs trust can own a rental property is a different question from buying the beneficiary’s home. It depends on the trust’s investment and distribution terms, the trustee’s duties in managing it, and how the rental income is treated. For SSI, when the trust’s principal is not a countable resource and the beneficiary has no right to receive or demand its retained rental earnings, those earnings generally are not the beneficiary’s income while retained. Income-tax reporting follows the trust’s tax classification, so a first-party grantor trust’s rental income is generally reported by the beneficiary even while it stays in the trust.
Can a Special Needs Trust Buy a Car?
Usually it can, if the trust permits it and the vehicle is for the beneficiary’s transportation. The questions are who will hold title, whether the beneficiary already has a vehicle, and who else will use it.
Check existing vehicles, use, title, insurance and resource exclusions; purchasing another vehicle is not automatically excluded. If you are asking how much a car can be worth on SSI, SSA excludes one automobile per household, regardless of value, when the beneficiary or a household member uses it for transportation (POMS SI 01130.200); a second vehicle, or one not used that way, may count as a resource if the beneficiary owns it. A vehicle titled to the trust is reviewed differently from one titled to the beneficiary, and the trust may need to insure it.
A special needs trust can usually pay for car insurance, gas, maintenance and repairs, paid to the vendor. If a family member drives the beneficiary, document the beneficiary’s transportation need and how personal use of the vehicle by others is handled.
Debit Cards, Credit Cards, Gift Cards and Reimbursements
When a trust’s principal is not countable, cash paid directly to its SSI beneficiary is generally unearned income; amounts retained may also raise a later resource issue. Paying a vendor can avoid handing over cash, but it does not make shelter or countable property disappear from the analysis.
Can a special needs trust have a debit card or credit card?
A trust can use cards, but the card type does not decide the outcome. Questions about a special needs trust debit card or prepaid card, including prepaid debit cards marketed for disabled adults, come down to who owns the account, whether it can produce cash, what restrictions apply and what is actually bought. A beneficiary-owned debit account is different from a trustee-owned, administrator-managed prepaid card. Account ownership, cash access, restrictions and actual purchases all matter. A credit card also requires item-by-item review of the bill. Do not assume a card is acceptable because it is marketed for special needs trusts. See SSA payment-method guidance, E.
Many pooled trust administrators offer their own debit or prepaid cards for accounts in the pooled trust. Those cards follow the administrator’s rules on limits, cash access and receipts, and purchases made with them still need the same review.
Card and account types at a glance
| Arrangement | Who owns or controls it | Can it produce cash? | What to review |
|---|---|---|---|
| Debit card on the beneficiary’s own account | The beneficiary | Usually yes | Money the trust deposits may be treated as the beneficiary’s income, and balances as the beneficiary’s resources. |
| Prepaid card controlled by the trustee or administrator | The trustee or administrator | Depends on the card’s settings | Whether cash withdrawals are blocked, what categories are allowed, who can reload it, and what was actually bought. |
| Credit card paid by the trust | Depends on whose account it is | Cash advances can | Each charge on the statement: food, shelter, items the beneficiary keeps, and anything bought for someone else. |
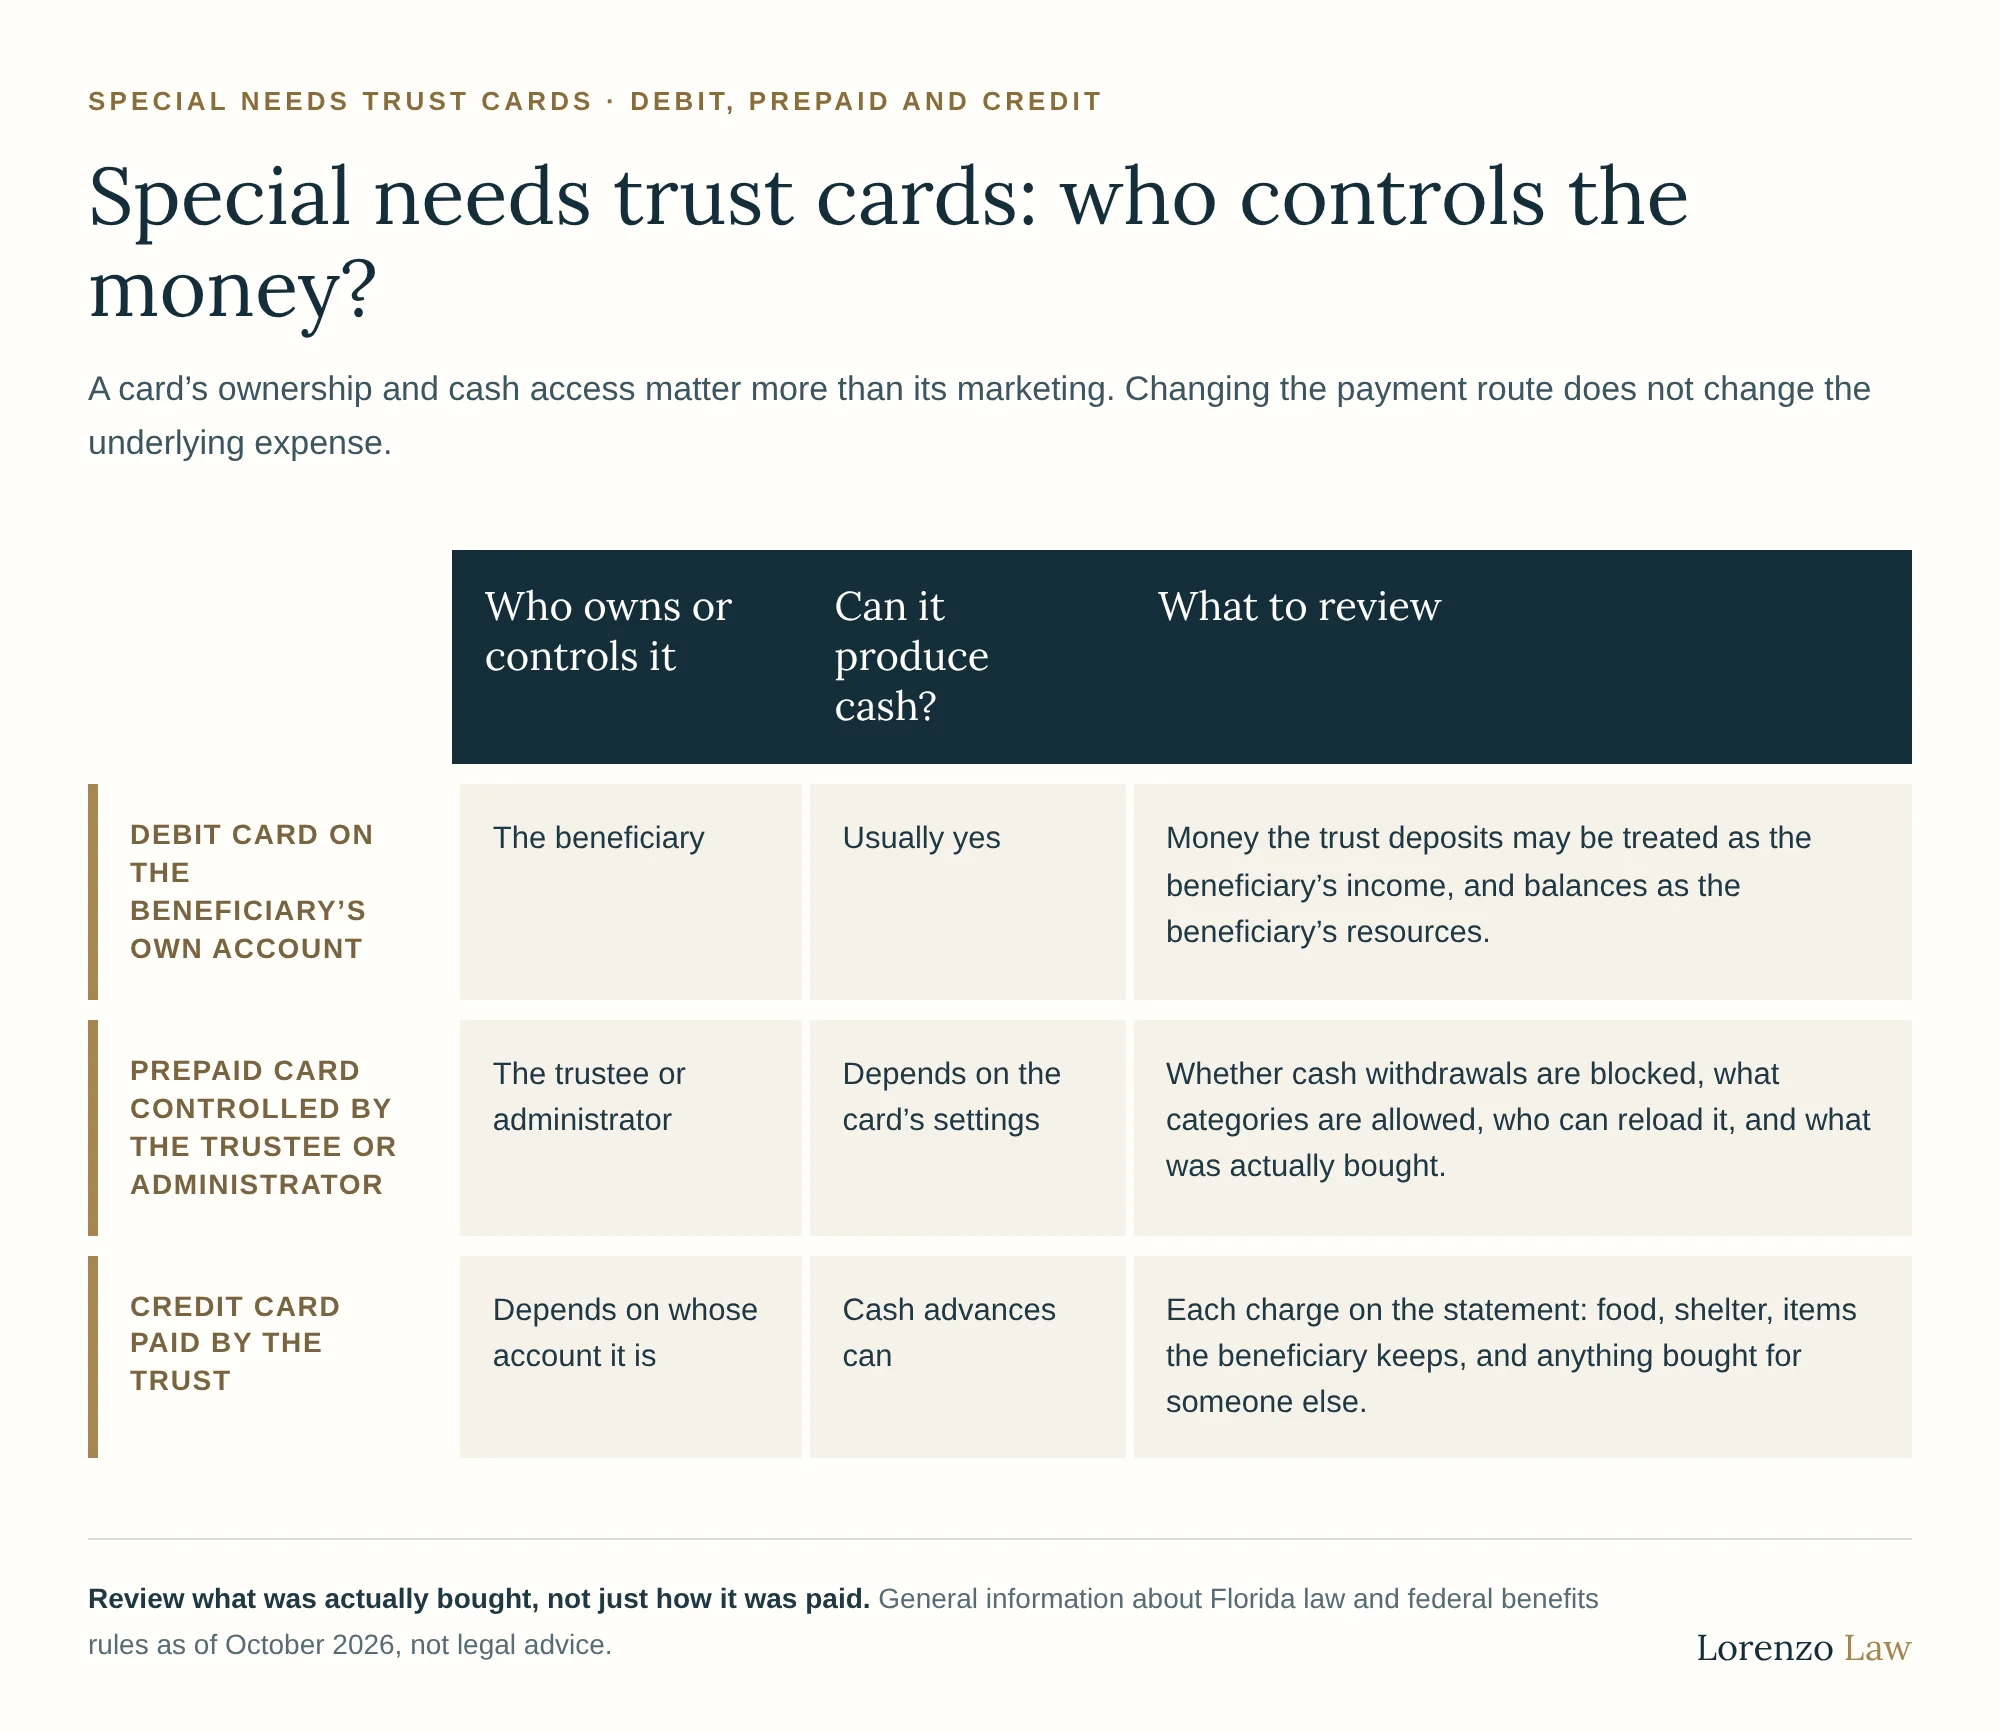
View the “Special needs trust cards: who controls the money?” chart (zoom in to read; the details are also in the table above).
Can a special needs trust buy gift cards?
Treat gift cards with caution. Under SSA’s gift-card policy, a gift card or certificate is generally income in the month it is received if it can be used to buy food or shelter or can be resold, and resale is presumed unless the card legally prohibits it. Any unspent balance is a resource beginning the next month (POMS SI 00830.522). SSA treats a gift card separately from in-kind support and maintenance, so do not assume that the September 2024 exclusion for food purchased directly (EM-24048) also excludes the value of a grocery or restaurant gift card. Paying the store or provider directly, or using a controlled card with records, is usually easier to document.
How does a special needs trust reimbursement work?
For reimbursements, retain evidence of who originally paid, what was purchased, who received it and when. Get advice before assuming that reimbursing a beneficiary has the same treatment as reimbursing a parent or provider.
How Does a Special Needs Trust Pay Out? The Distribution Request Process
Administering a special needs trust day to day mostly means handling distribution requests. Most distributions follow the same sequence, whether the trustee is a family member, a professional or a pooled-trust administrator.
- Request. The beneficiary, a family member or a care manager describes the need, the price and the vendor, with a quote or invoice.
- Authority. The trustee confirms the trust permits the expense and identifies the provision relied on.
- Benefits check. The trustee reviews current benefit notices and how this payment, and the way it is made, may affect each program.
- Payment. The trustee pays the vendor directly where practical, or documents why another route is used.
- File. The request, decision, invoice and proof of payment go into the trust’s records, along with any reporting step.
There is no single official special needs trust distribution request form. Pooled trust accounts use the administrator’s own request process and forms; follow those procedures rather than paying around them. Families can help the trustee by putting the beneficiary’s routines, preferences and needs in writing; see memorandum of intent.
SSI, SSDI, Medicare, Medicaid and Housing Assistance Are Separate Programs
SSI has income and resource rules. SSDI is based on Social Security disability-insurance requirements and does not use SSI’s needs-based resource test. A beneficiary may receive both. Medicare coverage is also distinct from Medicaid; help with Medicare costs can involve additional program rules. Use the award notices rather than the family’s shorthand description of “disability benefits.” See SSA disability eligibility and Medicare basics.
Programs at a glance
| Program | Needs-based? | What a distribution can affect | What to check |
|---|---|---|---|
| SSI | Yes | Cash and cash-like payments as income; shelter payments as in-kind support; retained items and money as resources | Current award notice, living arrangement, reporting |
| SSDI | No | Generally not the SSDI payment itself | Whether the person also receives SSI or Medicaid |
| Medicare | No, except help-with-costs programs | Eligibility for programs that help pay Medicare costs | Any Medicare Savings Program or Extra Help notice |
| Florida Medicaid | Yes, by category | Eligibility and, in long-term care, patient responsibility | The coverage category and the DCF notice |
| Housing assistance and SNAP | Yes | Countable income under each program’s own rules | Whether the payment is trust principal or income (housing) and whether it goes to a vendor or the household (SNAP) |
Florida Medicaid and patient responsibility
Florida Medicaid review must identify the coverage category, applicable trust rules and any patient responsibility. DCF’s SSI-related Medicaid manual distinguishes payments to the individual from qualifying trust payments to third parties and separately addresses income used to calculate patient responsibility. Its rules have stated conditions; they are not a universal approval for every trust or beneficiary. See the Florida DCF manual, §§ 1640.0576.08–.09. Changes affecting SSI also need a separate review of the person’s Medicaid eligibility route and any agency notice.
Does a trust distribution affect Section 8 or other housing assistance?
It can, under rules separate from SSI’s. Under HUD’s rules as amended by the Housing Opportunity Through Modernization Act (HOTMA), distributions of principal from a special needs trust are excluded from annual income only if the trust is excluded from net family assets under 24 C.F.R. § 5.603(b), that is, no family or household member can revoke or control the trust. Trust income distributions are generally counted as annual income unless an exclusion applies, including amounts used for a minor’s health and medical care expenses or amounts for or reimbursing any family member’s health and medical care expenses (24 C.F.R. § 5.609(b)(2)(i), (b)(6)). HUD has set January 1, 2027 for enforcing full compliance by most housing agencies, with separate timing for some (HUD Notice PIH 2026-15), so confirm which rules apply to the household’s certification and how the payment is classified before arranging recurring distributions.
Does a trust distribution affect SNAP food assistance?
SNAP (food stamps) applies its own income rules. Payments a trust makes directly to a vendor, from money the household is not owed, are generally excluded, while cash distributions to the household are generally counted as income unless a SNAP exclusion applies (7 C.F.R. § 273.9(b), (c)), but confirm with the SNAP office before relying on that, especially for recurring payments.
Can a special needs trust pay for assisted living or nursing-home extras?
It may, depending on the trust and the program. For a person receiving institutional or community-based long-term care, verify what the program covers before paying for a private caregiver, room upgrade or other service. Do not assume the same coverage or distribution treatment applies in every setting. In an assisted living facility, separate the charge for room and board from the charge for services, because a trust payment for room and board can be treated as shelter for SSI while Medicaid long-term-care coverage, where it applies, addresses services. Florida’s Statewide Medicaid Managed Care long-term-care program covers assisted living services (§ 409.98), and Florida’s Department of Elder Affairs explains that Medicaid cannot pay room and board in an assisted living facility (Elder Affairs housing guidance).
Caregiver Payments, Travel and Other People’s Expenses
Can a special needs trust pay a family member for care?
It can, with documentation. Payments involving relatives deserve clear documentation. Identify the actual services, hours, rate and benefit to the beneficiary, and check conflicts of interest before approval. For trusts subject to sole-benefit requirements, another person’s incidental benefit is different from using trust assets to make gifts to that person.
A written agreement signed before services begin, describing the duties, schedule and rate, with time records kept as the work is done, makes the arrangement easier to explain to an agency or a court. Payments for past care that was never documented are harder to support. If the caregiver is also the trustee, the conflict needs extra care under Florida’s duty of loyalty (§ 736.0802), and the trust’s terms or court approval may matter.
Can a special needs trust pay for vacation or a companion’s travel?
Often, yes, for the beneficiary’s own travel when the trust allows it. SSA permits certain accompanying-traveler expenses when assistance is necessary because of the beneficiary’s disability, medical condition or age. It also applies a reasonableness test to the number of people accompanying the beneficiary. That does not authorize paying for an entire family’s vacation merely because the beneficiary comes along. See POMS SI 01120.201 F.3–4. For family planning around a child with a disability, see estate planning for parents in Florida.
Special Needs Trust vs. ABLE Account: When an ABLE Account May Be Relevant
An eligible beneficiary’s ABLE account (an Achieving a Better Life Experience account, sometimes called a 529A account) can sometimes work alongside a trust, but it has separate eligibility, contribution, expense and recordkeeping rules. Beginning January 1, 2026, the disability-onset age threshold expanded to before age 46. That refers to when the qualifying condition began, not simply the person’s age when opening the account.
Housing distributions retained outside the ABLE account into the following month can become countable resources for SSI. Do not route a payment through ABLE without checking eligibility, contribution capacity, timing and the trust’s authority. See SSA ABLE guidance.
Special needs trust and ABLE account compared
| Question | Special needs trust | ABLE account |
|---|---|---|
| Who controls spending? | The trustee, under the trust’s standard | The account owner or an authorized person, within ABLE rules |
| Paying housing costs | Can reduce SSI as in-kind support | A housing expense under ABLE rules; timing of the withdrawal matters for SSI |
| Paying food | Direct food purchases are outside SSI’s ISM count since September 30, 2024 | Check the ABLE program’s qualified-expense rules |
| Contribution limits | Set by the trust and funding source | Annual contribution limits apply |
| Eligibility | Depends on trust type | Disability onset before age 46 (from January 1, 2026), plus SSI or SSDI entitlement on that basis or a disability certification |
Florida’s ABLE program is ABLE United. Contribution limits and program rules change, so confirm them with the program before relying on a figure.
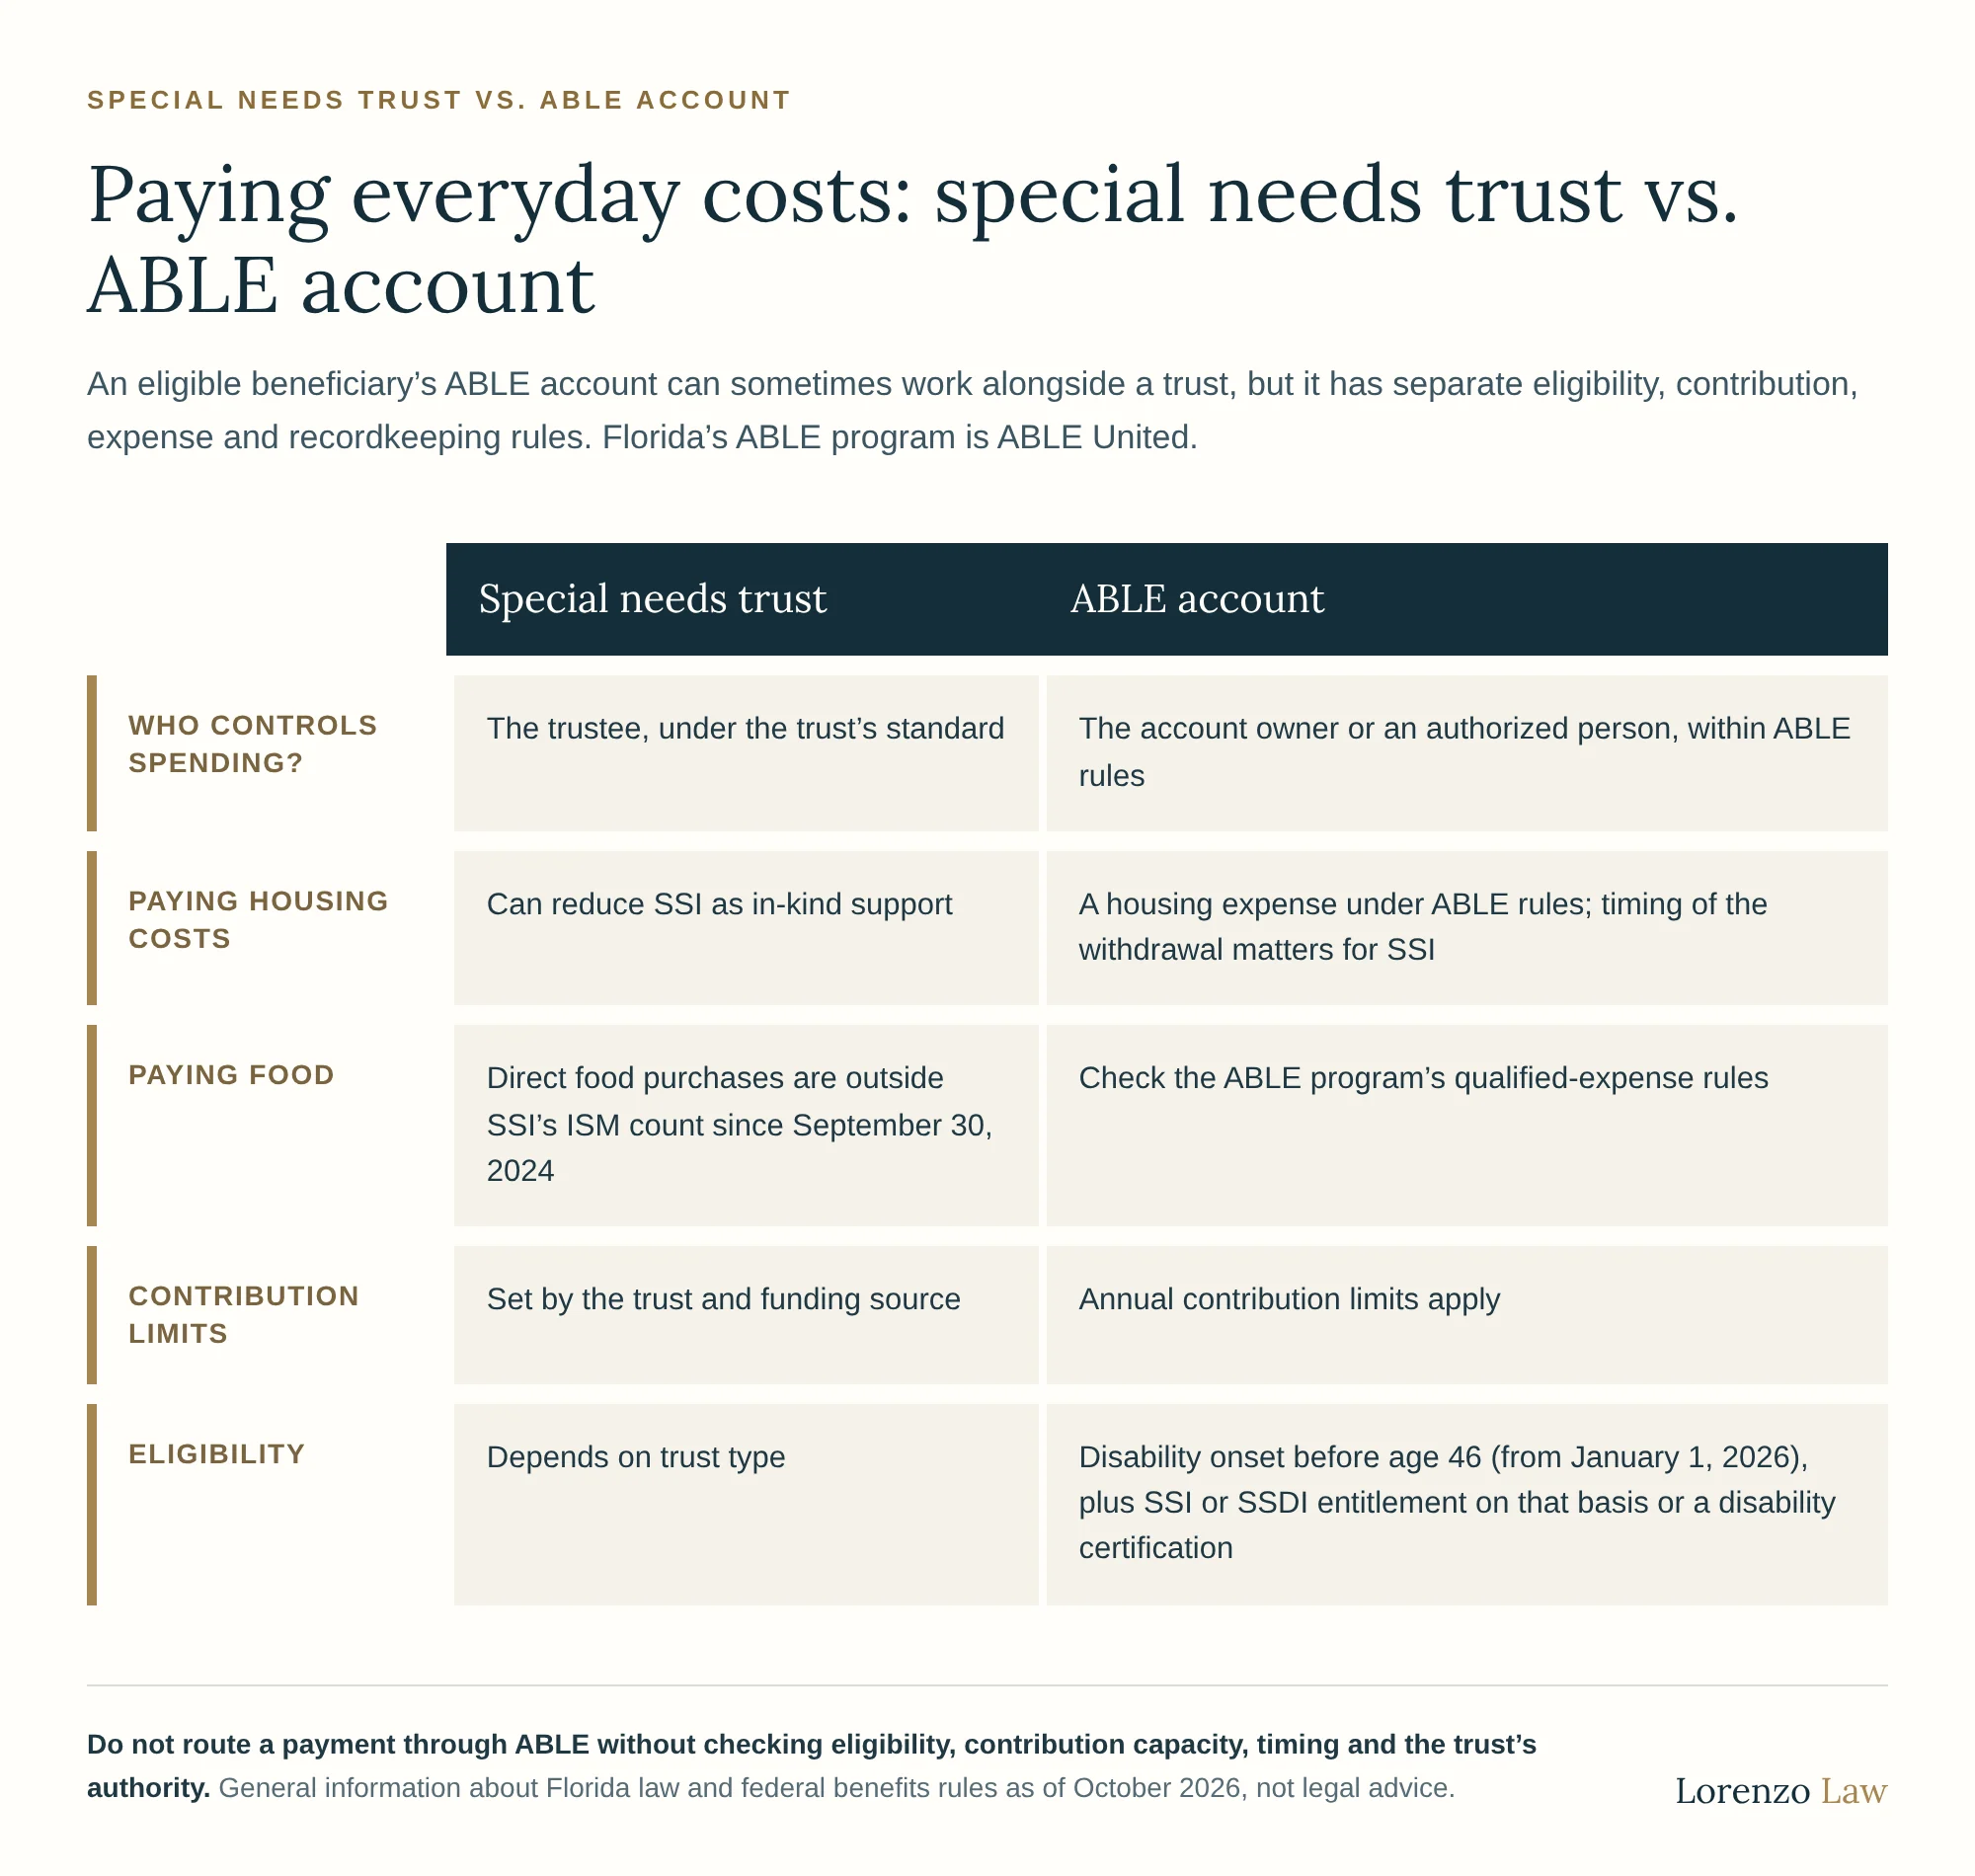
View the “Paying everyday costs: special needs trust vs. ABLE account” chart (zoom in to read; the details are also in the table above).
Can a special needs trust fund or contribute to an ABLE account?
Sometimes. ABLE rules allow contributions from any person, including a trust, and every contribution counts toward the account’s annual limit (POMS SI 01130.740). If the trust’s terms permit it and the beneficiary is eligible, a trustee may be able to contribute to the beneficiary’s ABLE account, but a first-party trust’s terms and reimbursement provisions need review first. Medicaid recovery from an ABLE account needs a separate review. Federal law permits, but does not require, a state to file a Medicaid payback claim against the account at the beneficiary’s death (26 U.S.C. § 529A(f)). For a Florida ABLE United account, however, Florida’s Medicaid program is barred from filing a recovery claim except as required by federal law (§ 1009.986(7)(b)); that bar applies only to accounts under the Florida program, not to ABLE accounts opened in another state. Review the account’s home-state rules, any benefits received in another state, and the first-party trust’s own reimbursement obligations before transferring funds. Treat the transfer as a distribution decision like any other, with its own record.
Special Needs Trust Accounting: Records That Support a Trustee’s Decision
A special needs trust trustee’s duties in Florida include keeping records that can support an accounting. Keep a distribution file with the request, date, amount, payee, purpose, authorizing trust provision, invoice, proof of payment and any title or ownership document. Include the benefit information used, the advice obtained and the reason for approving or declining a material request. For recurring expenses, record what circumstances would require a fresh review.
Keep trust money in a separate special needs trust bank account titled to the trust, maintain separate trust records and reconcile statements. Florida law requires clear, distinct and accurate records of trust administration and separation of trust property from the trustee’s own property. See Florida Statutes § 736.0810.
What information and accountings must a Florida trustee give the beneficiary?
Once the trust is irrevocable, the beneficiary’s information and accounting rights are governed by section 736.0813, the same provision that applies to other irrevocable trusts. Qualified beneficiaries are entitled to notice of the trust, a complete copy of the trust instrument on request, relevant information about the trust’s assets and administration on reasonable request, and an accounting at least annually. These core duties cannot be eliminated by the trust’s terms (§ 736.0105(2)(r)–(t)), subject to statutory exceptions: a qualified beneficiary may waive the right to annual accountings in a signed writing (§ 736.0813(2)), and a special rule permits a family trust company serving as trustee to account only at termination, on a change of trustee, or on demand (§ 736.0813(1)(d)). An accounting must meet the content requirements of section 736.08135; bank statements or transaction logs alone are not a statutory trust accounting (Revah v. Revah, 424 So. 3d 971 (Fla. 4th DCA 2025)).
Can a trustee of a special needs trust be paid?
Yes. If the trust is silent on compensation, a Florida trustee is entitled to compensation that is reasonable under the circumstances. There is no statutory percentage schedule. If the trust sets compensation, a court may allow more or less when the trustee’s duties are substantially different from those contemplated or the specified compensation would be unreasonably low or high. See section 736.0708. Trustee fees are a trust expense and belong in the records like any distribution.
A trustee is also entitled to be reimbursed from trust property for expenses properly incurred in administering the trust, such as accounting, tax-preparation and legal fees for the trust (§ 736.0709). Keep receipts for those reimbursements, separate from distributions for the beneficiary.
In practice, family members who serve as trustee often serve without a fee, and professional or corporate trustees commonly use published fee schedules, which are worth reviewing before an appointment. Florida law does not require a fee schedule and sets no special compensation cap for first-party trusts.
How do you change the trustee of a special needs trust?
The beneficiary cannot do it alone unless the trust grants that power. Once a trust is irrevocable, replacing a trustee runs through a removal power in the trust instrument or a court petition under section 736.0706; when a trustee resigns or the office becomes vacant, the trust’s terms and section 736.0704 govern who fills it. See removing a trustee in Florida; for disputes over distributions, see Florida trust litigation.
Does SSI ask for receipts?
Special needs trust reporting requirements run in two directions: Florida’s information and accounting duties to beneficiaries, described above, and reporting to Social Security. Social Security can ask about trust distributions and may request records, so keep receipts and invoices for every distribution. Coordinate with the beneficiary and any representative payee so reportable changes are addressed. A trustee and an SSI representative payee have different roles. Changes that may affect SSI must be reported no later than ten days after the end of the month in which they happen (20 C.F.R. § 416.714; reportable events are listed in 20 C.F.R. § 416.708). Keep copies of submissions and agency notices. See SSA reporting responsibilities.
Special Needs Trust Mistakes and Violations to Avoid
No single official list of special needs trust violations or penalties exists. A distribution the trust does not allow can be a breach of trust, and one that affects benefits can lead to a reduced benefit or an overpayment notice. Most problems come from a few repeated patterns:
- Treating a “prohibited list” as the trust’s rules. The trust document and its funding source control, not a generic list.
- Handing over cash or loading the beneficiary’s own debit account without analyzing the income and resource effect.
- Paying shelter costs without measuring the SSI effect, or refusing them when the trust allows them and the housing need justifies the reduction.
- Buying something the beneficiary will own and keep without considering whether it becomes a countable resource.
- Paying relatives without a written agreement, time records or a reasonable rate.
- Paying for the whole family where sole-benefit rules apply.
- Using trust money for the trustee’s or family’s own purposes. That is misuse of trust property, whatever its effect on benefits.
- Mixing trust money with personal money or failing to keep records that would support an accounting.
- Not coordinating reporting with the beneficiary or representative payee.
What if a payment has already been made?
If a payment has already been made, preserve the records and obtain advice about its treatment and any reporting or correction needed. Do not assume that relabeling the payment, returning funds or using a different account will reverse its effects.
Two Worked Examples
Example 1: rent for an SSI recipient. A beneficiary who receives SSI rents an apartment, and her rent is rising. The trust allows housing payments. The trustee confirms the living arrangement, estimates the monthly SSI reduction under the applicable valuation rule, compares it with the rent the trust would cover, and documents the decision. If the trustee pays, the landlord is paid directly, the change is reported, and the lease and payments go into the file. The facts in this example are hypothetical.
Example 2: a family member asks to be reimbursed for a car. A parent bought a used car for an adult son who receives SSI and Medicaid and asks the trust to repay him. The trustee asks who holds title, whether the son already owns a vehicle, how the car is used and what the trust allows, and reviews the original purchase records before deciding. Reimbursing the parent is a different transaction from paying the son, and the file should show which one occurred. The facts in this example are hypothetical.
Special Needs Trust Distributions: Frequently Asked Questions
Short answers to common questions. Each answer is limited by the qualifications in the sections above.
What can a special needs trust pay for in Florida?
Goods and services that supplement public benefits, such as uncovered medical and dental care, therapy, equipment, education, recreation, travel, transportation, phones, computers and clothing, when the trust permits the payment. Shelter costs, cash and items the beneficiary will keep need a closer look; see the expense review table.
Does a special needs trust affect SSI?
Holding money in a properly structured trust whose principal is not countable is designed to protect SSI, but distributions can still affect it. Cash to the beneficiary is generally income, and shelter payments can reduce SSI. Food bought directly is outside SSI’s in-kind support count since September 30, 2024.
Is a distribution counted as income for SSI?
Cash paid directly to an SSI beneficiary from a trust whose principal is not countable is generally unearned income. Vendor payments require review of what the beneficiary receives: shelter may be in-kind support, and noncash property that would not qualify as an excluded resource can count as income in the month received as well as raise a resource issue afterward (20 C.F.R. §§ 416.1103, 416.1207; POMS SI 01120.200 E.1). Direct food purchases have been excluded from SSI’s in-kind support calculation since September 30, 2024.
Can you withdraw money from a special needs trust?
The beneficiary generally cannot withdraw money on demand; the trustee decides under the trust’s distribution standard. A beneficiary who could take money out freely could have the trust treated as a countable resource.
What are the downsides of a special needs trust for day-to-day spending?
The main disadvantages are practical. The beneficiary cannot spend the money freely: the trustee decides, under the trust’s terms, and must keep records. Shelter payments can reduce SSI, cash usually counts as income, and professional trustee and administration fees reduce the fund. A first-party trust also carries Medicaid reimbursement provisions at the beneficiary’s death. For many families those limits are the price of keeping needs-based benefits.
Can a special needs trust pay for clothing, a phone or a computer?
Usually, when the trust permits it. Clothing is not counted as in-kind support and maintenance for SSI, and phone and internet service are not among the household costs SSA treats as shelter. Pay the seller directly and keep the receipt.
Can a special needs trust pay medical bills or health insurance premiums?
Usually, when the trust permits it. SSA does not count medical services, including medical items, as SSI income, whoever pays for them, and a third party’s direct payment of a person’s health insurance premiums is not income either (POMS SI 00815.050). Pay the provider, pharmacy or insurer directly rather than reimbursing the beneficiary in cash. Before paying, confirm coverage, any remaining patient charge and the reason for a private payment; keep the bill and the coverage explanation.
Can a special needs trust pay for funeral expenses?
A trust can often buy an irrevocable prepaid funeral or burial arrangement during the beneficiary’s lifetime, if its terms permit. After the beneficiary dies, a first-party trust’s Medicaid reimbursement provisions limit what it can pay before the state is reimbursed, while a third-party trust follows its own terms. What happens to the rest of the trust at death is covered in the Florida special needs trust guide.
Are special needs trust distributions taxable to the beneficiary?
It depends on how the trust is classified for income-tax purposes. A first-party trust is often treated as a grantor trust, so its income is reported by the beneficiary. A third-party trust may pay its own tax or carry income out to the beneficiary through distributions, and some qualify for a larger exemption as a qualified disability trust (26 U.S.C. § 642(b)(2)(C)). A trust that is not a grantor trust generally needs its own tax identification number (EIN) and files its own special needs trust tax return, a fiduciary income tax return on Form 1041, when it meets the filing threshold. Ask a tax adviser before year-end. If retirement accounts are left to the trust, see beneficiary designations for retirement plans.
Does a special needs trust affect SSDI or Medicare?
SSDI does not use SSI’s needs-based resource test, and Medicare coverage is distinct from Medicaid. Programs that help pay Medicare costs can have their own income and resource rules, so check any such notice.
Is a Miller trust the same as a special needs trust?
No. A qualified income trust (Miller trust) is an income-only arrangement for specified Florida Medicaid long-term-care programs. Florida DCF says not to add assets to it, and the expense examples on this page are not QIT spending instructions.
Can a special needs trust pay off the beneficiary’s credit card debt?
Review the underlying charges first. Paying a credit card bill is treated by what was bought: charges for shelter, cash advances and purchases the beneficiary keeps can each have a different effect. Changing the payment route does not erase the underlying expense.
How much money can be in a special needs trust?
There is no general dollar cap on what a special needs trust may hold. The questions are what the trust’s terms allow, how distributions affect benefits, and, for a first-party trust, its Medicaid reimbursement provisions.
Money held in the trust can be invested. A Florida trustee must invest under the prudent investor rule (§ 518.11) and administer the trust prudently (§ 736.0804). For SSI, when the trust’s principal is not a countable resource and the beneficiary has no right to receive or demand its retained earnings, those earnings generally are not the beneficiary’s income while retained. Income-tax reporting follows the trust’s tax classification; a first-party grantor trust’s income is generally reported by the beneficiary.
Who decides whether a distribution is made?
The trustee, under the trust’s terms. Even broad discretion must be exercised in good faith and in accordance with the trust’s terms and purposes and the beneficiaries’ interests (§ 736.0814). A beneficiary’s challenge turns on whether that discretion was abused.
Is a supplemental needs trust different from a special needs trust?
The terms are often used interchangeably for a trust that supplements, rather than replaces, needs-based benefits, so what a supplemental needs trust can pay for follows the same rules described here. What matters is the trust’s actual terms and funding source, not its label. The same arrangement is sometimes called a supplemental trust or, informally, a trust account for a disabled adult.
Can a special needs trust pay for the beneficiary’s spouse or children?
Not as gifts from a trust subject to sole-benefit rules. Because a first-party trust must be administered for the beneficiary’s sole benefit, distributions that primarily benefit a spouse or child, rather than the beneficiary, can jeopardize benefits and should not be made without specific advice. Another person’s incidental benefit from a purchase for the beneficiary is different from using trust assets to pay that person’s expenses. A third-party trust follows its own terms, which may allow more.
Discuss a Florida Trust Administration Question
If you need a Florida special needs trust attorney for a trust administration question, such as a trustee deciding on a distribution or a beneficiary questioning one, Lorenzo Law offers a free initial consultation about Florida trust administration. Explain whether you are the trustee, beneficiary or a family member, what payment is proposed or has already occurred, and whether an agency or court notice gives a deadline. Consultations are available in English and Spanish, and one lawyer, Jose M. Lorenzo, Jr., handles each matter himself.
Have the signed trust and amendments, relevant court orders, current benefits notices, recent trust statements and expense details ready for a requested review. Do not send Social Security numbers, account numbers or private medical records through the public contact form.
The scope and fee for legal work are confirmed separately. This consultation offer concerns trust administration; it does not include a promise to handle Medicaid or SSI applications, reporting or appeals. Benefits, tax and other specialized questions may require separate professional advice.
Request a free initial consultation or Call (305) 224-6811
Lorenzo Law’s principal office is in Kissimmee, with meetings by appointment in Coral Gables (Miami-Dade County) and Fort Lauderdale (Broward County), and the firm works with trustees and families statewide. For related planning, see the Florida trusts guide.
This article provides general information about Florida law and federal benefits rules. It is not legal advice and does not create an attorney-client relationship. No example on this page grants permission to make a real payment; a proposed expense requires review of the actual trust, funding history, orders, benefits notices and payment route. It reflects the law and agency guidance as of October 2026.
About the Author
Jose M. Lorenzo, Jr. was admitted to The Florida Bar on October 4, 2013, Bar number 107002. His pre-admission paralegal experience is described separately in his biography. Lorenzo Law’s principal office is in Kissimmee, with meetings by appointment in Coral Gables (Miami-Dade County) and Fort Lauderdale (Broward County).
Authorities Cited on This Page
The Florida statutes cited here are the 2026 Florida Statutes. Statutory, regulatory and agency text controls over any summary on this page.