Florida Inheritance Tax: Does Florida Have One? No — Here Is What Heirs Still Pay
Florida inheritance tax does not exist: Florida has no inheritance tax, no estate tax for deaths after December 31, 2004, and no gift tax, so heirs owe Florida nothing because they inherit.
What heirs and estates can still owe is mostly federal: the estate tax on estates above the $15 million exclusion for 2026 deaths, income tax on inherited IRAs and 401(k)s, and capital gains when inherited property is sold, while the property tax on an inherited Florida home can rise. This guide, written by a Florida probate attorney, explains each one, who pays it and which forms apply.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing. Consultations are available statewide in English and Spanish, by phone or video.
Request a free initial consultationCall (305) 224-6811
Go straight to: How much is tax-free · Federal estate tax 2026 · Inherited IRAs · Inheriting a house · DR-312
By situation: an heir should start with how much you can inherit and whether an inheritance is income; a personal representative, with who must file Form 706 and the estate’s income taxes; a surviving spouse, with portability and the property-tax exceptions; a family with property elsewhere, with other states and moving to Florida.
All guide sections 25 sections
Short answer. Does Florida have an inheritance tax? No. Florida has no inheritance tax, no state estate tax for people who died after December 31, 2004, and no state gift tax, so there is no Florida inheritance tax rate to calculate and no Florida death tax for heirs to pay, whatever the amount and whatever the relationship to the person who died (Florida Department of Revenue). Other taxes can still apply. The estate itself may owe federal estate tax if it is large enough; an inherited traditional IRA or 401(k) is taxed as income when the money comes out; income the estate earns after death is taxable; selling inherited property can produce a capital gain; the property tax on an inherited Florida home can rise; and another state can tax property located there. Probate costs are court and administration expenses, not a tax.
| Florida inheritance tax | None. No Florida tax is due because you receive an inheritance, for a spouse, child, sibling, friend or anyone else. Why Florida has none |
|---|---|
| Florida estate tax | None for deaths after December 31, 2004. Personal representatives no longer file Forms DR-312 or DR-313 (beginning July 1, 2023). Florida filings |
| Florida gift tax | None. Federal gift-tax rules still apply to large lifetime gifts. Gift tax |
| Federal estate tax | Paid by the estate, not by each heir, and only when the taxable estate exceeds what the exclusion covers: $15 million for a death in 2026 ($13.99 million in 2025), top rate 40 percent. Federal estate tax |
| Income tax | An inheritance is not income, but withdrawals from inherited pretax retirement accounts, and interest, dividends or rent earned after death, are taxable. Is an inheritance income? |
| Capital gains | Capital gains tax applies only on a later sale, measured from the stepped-up basis — generally the value at death, not what the decedent paid. Inheriting a house |
| Property tax | The Save Our Homes cap usually resets on January 1 after the home changes hands, unless an exception applies. Property taxes |
| Other states | Kentucky, Maryland, Nebraska, New Jersey and Pennsylvania have inheritance taxes, and several states have estate taxes, based on where the decedent lived or the property sits. Other states and abroad |
Start with three facts: who died and when, what you inherited, and what happens to the asset next. A cash distribution, an inherited IRA withdrawal and the sale of an inherited house are taxed differently, and the year of death decides which federal estate-tax figures apply. The tables below summarize each tax, who pays it and what triggers it.
| Tax or cost | Who pays or files | What triggers it | Starting authority |
|---|---|---|---|
| Florida inheritance tax | No one | Florida does not impose one | Fla. Const. art. VII, § 5; Florida DOR |
| Florida estate tax | No one, for deaths after December 31, 2004 | A death before 2005 requires review under the rules then in force | § 198.02; § 198.13 |
| Federal estate tax | The estate, through the personal representative; the burden is then apportioned among the interests | Gross estate plus adjusted taxable gifts above the filing threshold for the year of death; tax is due only after deductions and credits | IRS estate tax; § 733.817 |
| Income tax on retirement accounts and other income in respect of a decedent | Whoever receives the payment: a beneficiary, an estate or a trust | Distributions of pretax money; final wages, bonuses, deferred interest | IRS Publication 590-B; Publication 559 |
| Income tax on income earned after death | The estate or trust, or the beneficiary who receives it in a distribution | Interest, dividends, rent and gains during administration | Form 1041 instructions |
| Capital gains tax | Whoever sells: the estate, a trust or the heir | A sale for more than the adjusted basis, which usually starts at the value at death | IRS Topic 703; Publication 559 |
| Florida property tax | The owner | Ongoing ownership; a change of ownership can reset a capped homestead assessment | § 193.155 |
| Another state’s inheritance or estate tax | The estate or the recipient, under that state’s law | The decedent’s domicile, where real property sits, and the recipient’s relationship | New Jersey Division of Taxation (example) |
| Probate fees and administration expenses | Usually the estate | Court filings, personal-representative and attorney fees, appraisals, recording | § 28.2401; § 733.617 |
Figures are for deaths in calendar year 2026 unless a row says otherwise. A reporting form can be required even when no tax is due; see the forms table.
Inheritance tax, estate tax, death tax and income tax: what each one means
An inheritance tax is charged to the person who receives property, usually at a rate that depends on that person’s relationship to the decedent. An estate tax is charged to the estate on the value of everything the decedent owned at death, before anything is distributed. “Death tax” is an informal name for either. An income tax applies to income, including income earned after death and pretax retirement money that comes out of an inherited account. Florida imposes none of the first two, and Florida has no personal income tax.
| Question | Estate tax | Inheritance tax |
|---|---|---|
| Who is taxed | The estate, before distribution | Each recipient, on what that person receives |
| What sets the rate | The size of the taxable estate | Usually the recipient’s relationship to the decedent; spouses and often children are exempt |
| Federal version | Yes: the federal estate tax, with a $15 million basic exclusion for 2026 deaths | No: there is no federal inheritance tax |
| Florida version | None for deaths after December 31, 2004 | None |
| States that have one | About a dozen states and the District of Columbia | Kentucky, Maryland, Nebraska, New Jersey and Pennsylvania; Maryland has both |
Whatever name is used, the answer is the same. Florida inheritance tax, inheritance tax in Florida, inheritance tax Florida and FL inheritance tax all describe a tax Florida does not impose; there is no Florida state inheritance tax, sometimes called a state of Florida inheritance tax. A Florida estate tax (estate tax in Florida, or Florida state estate tax) does not apply to anyone who died after December 31, 2004, and Florida death tax or death tax Florida is an informal name for those two. “Succession tax” and “hereditary tax” are older or foreign names for a tax on what an heir receives, and “inherent tax” is a common misspelling of inheritance tax; Florida has none of them. How does inheritance tax work in Florida, then? It does not apply; the questions that matter are federal estate tax, income tax, capital gains, property tax and other states.
There is also no federal inheritance tax. When someone asks “how much is federal inheritance tax in Florida” or “is there a federal inheritance tax,” the tax they usually mean is the federal estate tax, which the estate pays (see the federal estate tax). Is inheritance tax the same as estate tax? No. Estate tax vs inheritance tax comes down to who is taxed, as the table above shows, and the difference matters when property in another state is involved.
Common myths about Florida inheritance and estate taxes
- “Heirs pay a Florida inheritance tax.” No Florida tax applies to receiving an inheritance.
- “The estate tax exemption is a per-heir allowance.” The $15 million figure is the estate’s federal basic exclusion for a 2026 death, not an amount each beneficiary may receive tax-free.
- “Everything I inherit is tax-free.” Principal usually is, but an inherited traditional IRA is taxed as it is withdrawn, and income after death is taxable.
- “Probate is a tax.” Probate costs are court fees and administration expenses.
- “A trust avoids estate tax.” A revocable trust can avoid probate for assets titled in it, but its assets remain in the federal gross estate.
- “The exemption dropped to about $7 million in 2026.” That scheduled drop did not happen; the 2026 basic exclusion is $15 million.
Why Florida has no inheritance or estate tax
The Florida Constitution bars any state tax on estates, on inheritances, or on the income of natural persons who are Florida residents or citizens, except to the extent of amounts that may be credited against or deducted from a similar tax levied by the United States or any other state (art. VII, § 5(a)). That single limit is why Florida has no state estate or inheritance tax and no personal income tax. Florida’s estate tax statute, Chapter 198, measured the tax by the federal credit for state death taxes. When federal law phased that credit out, the Florida estate tax stopped applying to people who died after December 31, 2004. Florida does not tax beneficiaries on what they receive.
For decades Florida collected a “pick-up” or “sponge” estate tax: it captured, for Florida, the federal credit that the estate could claim for state death taxes, so the Florida tax cost a large estate nothing extra. The federal credit was phased down after 2001 and replaced with a deduction beginning in 2005. With no credit to measure it, the Florida estate tax for later deaths became zero (Florida DOR; § 198.02).
The limit now appears in article VII, section 5 of the 1968 Constitution, as amended at the general election of November 2, 1971.
Chapter 198 remains in the Florida Statutes. Its provisions still govern older estates and set out the return relief and lien rules described in the Florida filings section. In short, Florida has no state estate tax since 2005: with the Florida estate tax eliminated after December 31, 2004, there is no Florida estate tax to calculate for a death on or after January 1, 2005.
Could Florida bring back an inheritance tax or estate tax?
Under current law there is none, and this page does not predict future legislation. The constitutional limit ties any Florida estate or inheritance tax to a credit or deduction allowed against a similar tax levied by the United States or any other state, so the question would turn on future changes to federal law, to the Florida Constitution, or both. Planning should be based on the law in force on the date of death, which for 2026 means no Florida inheritance tax and no Florida estate tax.
How much can you inherit in Florida without paying taxes?
Any amount, as far as Florida is concerned: there is no Florida limit, threshold or exemption because there is no Florida inheritance tax. At the federal level, the estate, not the heir, owes estate tax only if the taxable estate exceeds what the exclusion covers, which is $15 million for a person who dies in 2026. What you may still owe as an heir is income tax on certain assets, such as an inherited traditional IRA, and capital gains tax applies if you later sell inherited property for more than its basis, which generally starts at the value at death.
How much inheritance is tax free in Florida? All of it, as far as Florida is concerned. What is the threshold for inheritance tax in Florida, and what is the inheritance tax limit? Florida has neither, so there is no current threshold and no state maximum inheritance without tax. How much can you inherit without paying taxes in Florida, or how much money can you inherit without paying taxes at all? Florida sets no cap, and the federal estate-tax figure is a measure of the whole estate, not a per-beneficiary allowance: a $16 million estate divided among four children can owe federal estate tax even though each child receives $4 million, and, under the U.S.-citizen/resident assumptions above, and assuming no prior taxable gifts that used the exclusion, a $3 million estate owes no federal estate tax regardless of how it is divided.
Do I have to pay taxes on a $10,000, $100,000 or $1 million inheritance?
Generally not on the inheritance itself. Receiving $10,000, $100,000 or $1 million in cash, or a house or stocks worth that much, is not taxable income to you, and Florida charges no inheritance tax on any amount. Three things change the answer. First, if the money comes from a traditional IRA, 401(k), 403(b) or annuity, the pretax part is taxable to you when it is distributed. Second, interest, dividends or rent earned after the date of death are income to whoever receives them. Third, if the inheritance came from abroad, a U.S. person may have to report it even though no tax is due (see inheritances from abroad). If the thought is “I inherited $100,000, what should I do?”, identify which of those categories the money falls into before you withdraw, spend or invest it.
Is an inheritance taxable income? What to report to the IRS
An inheritance is not taxable income to the person who receives it. Federal law excludes property acquired by bequest, devise or inheritance from gross income, so inherited cash, a house, stocks or other property is not reported as income on your Form 1040 just because you received it (IRS Publication 559). Income connected to the inheritance is different: pretax retirement money, income the decedent earned but had not been paid, and income the property earns after death are taxable to whoever receives them.
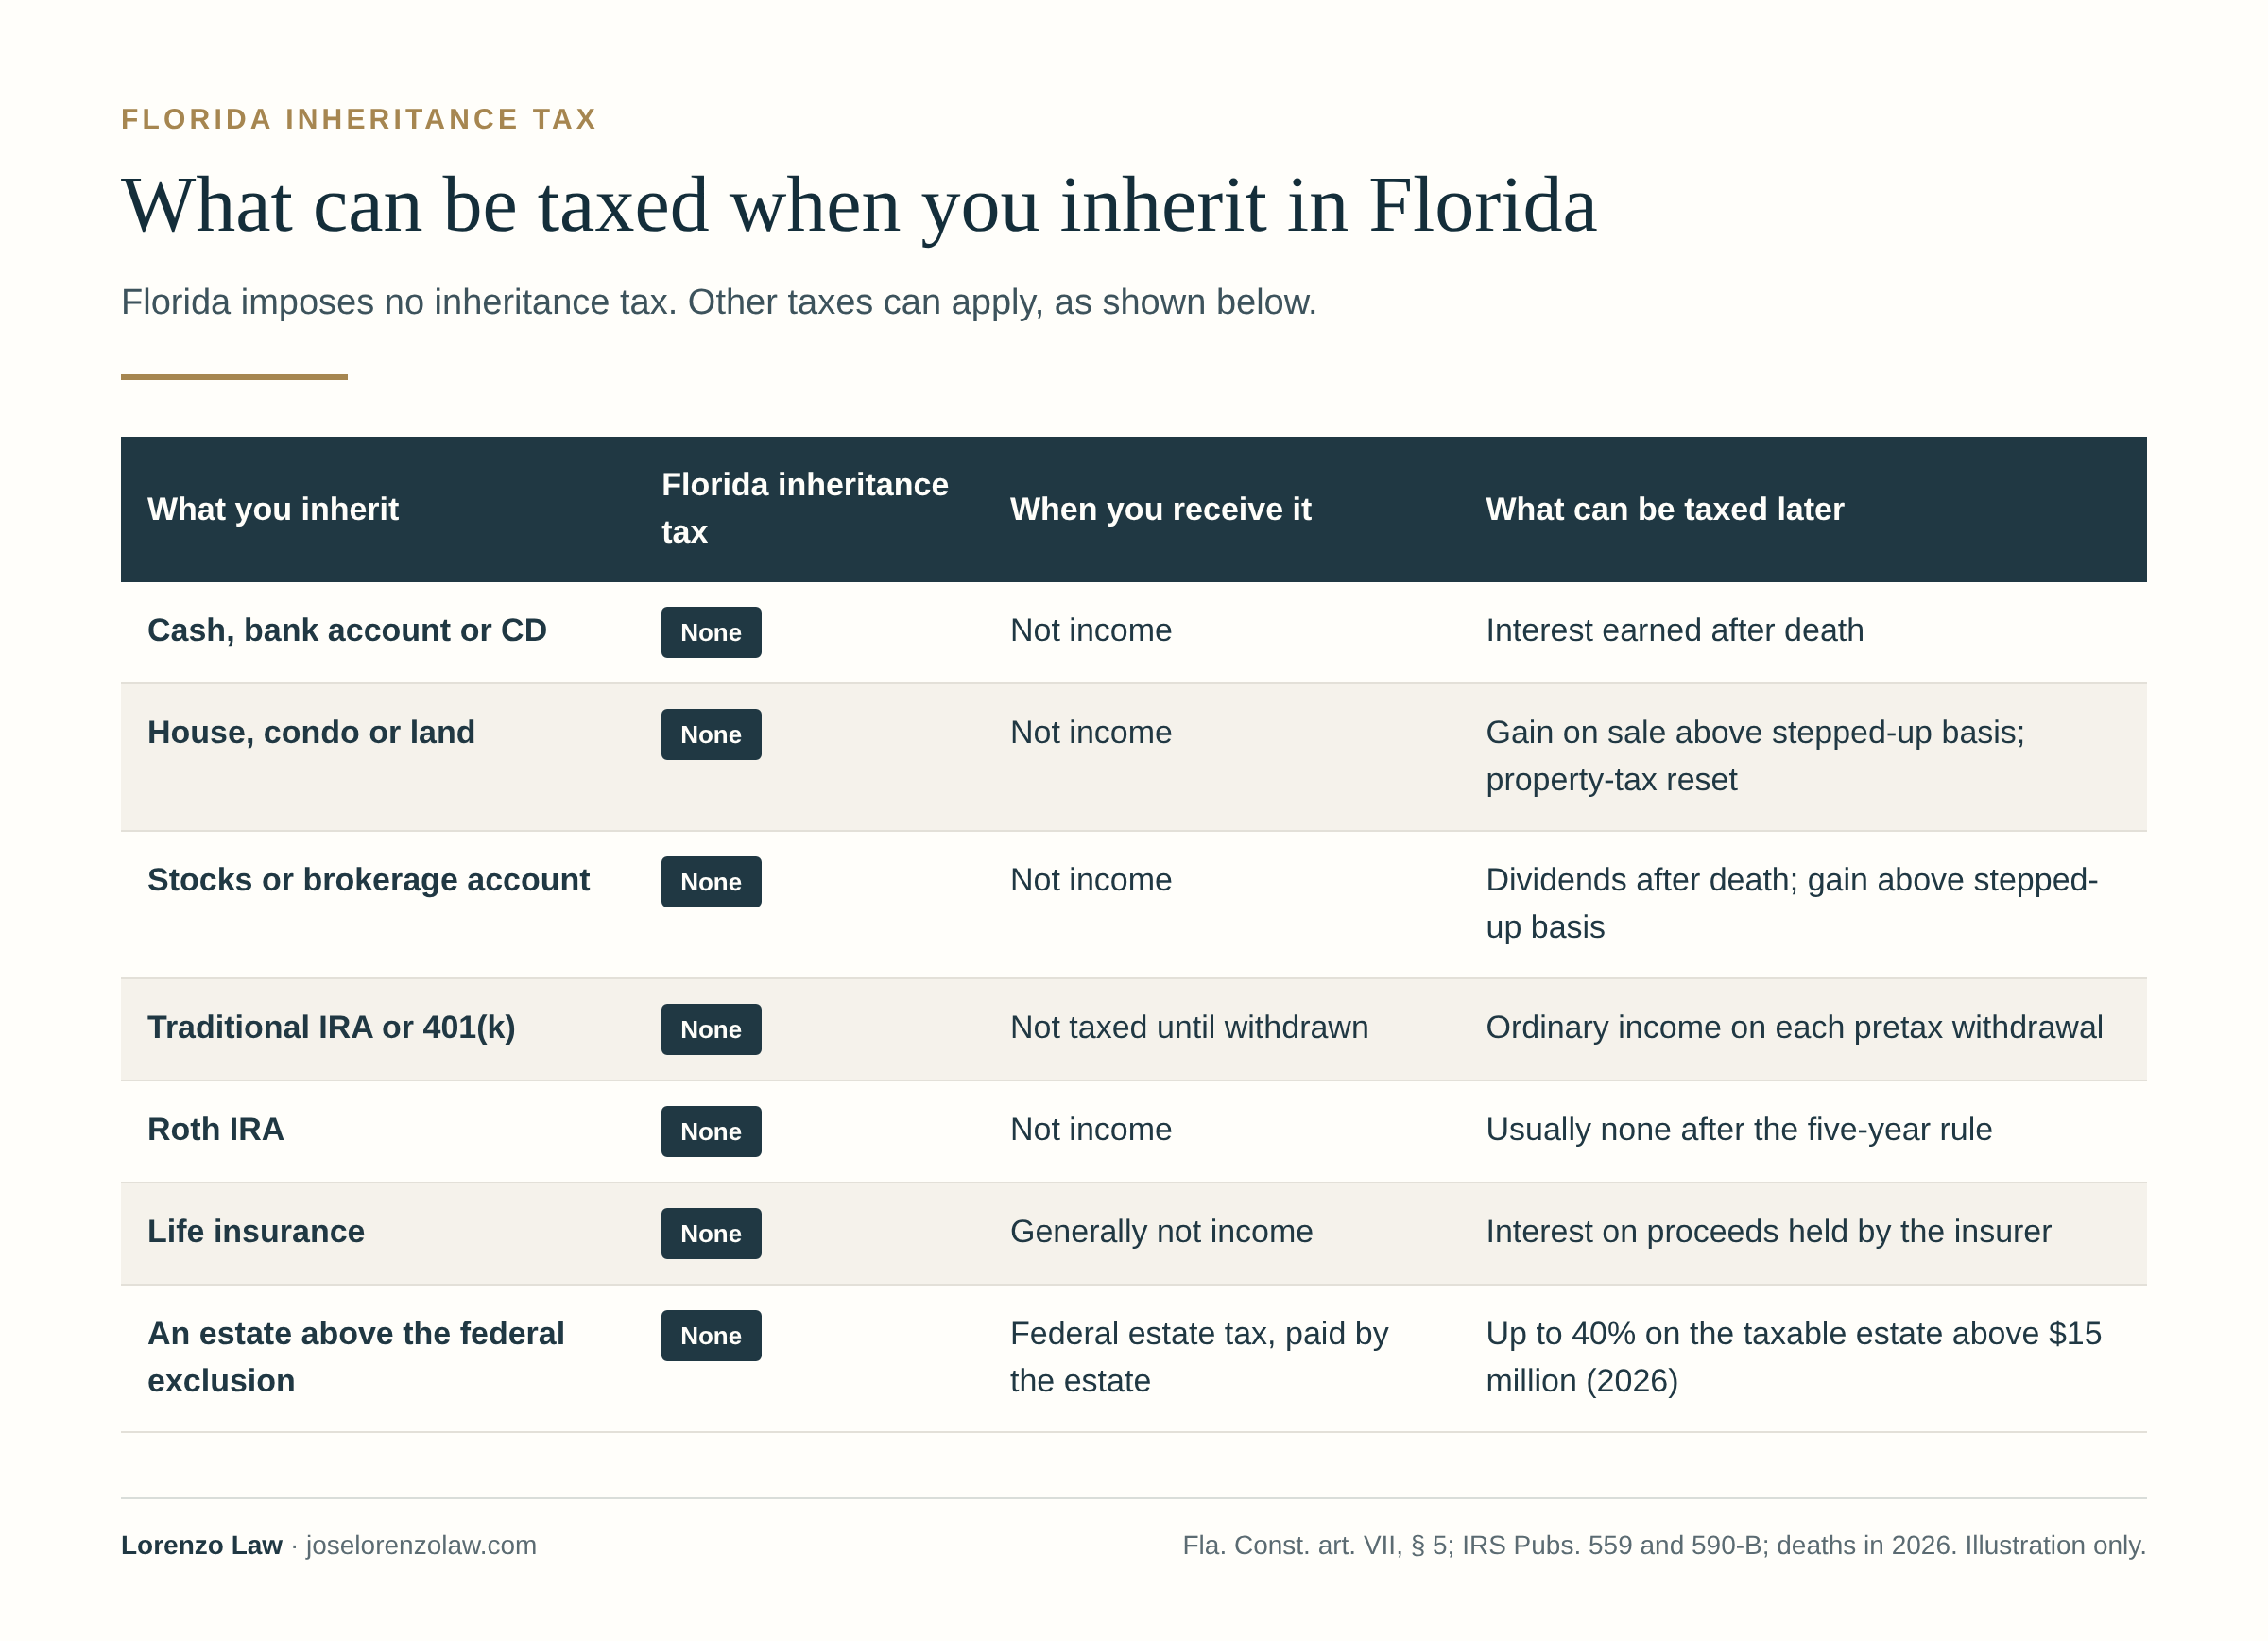
Is inheritance taxable? Not the principal. What part of an inheritance is taxable? The parts that carry income, such as pretax retirement money and income earned after death; the table below lists them.
| What you inherited | Taxable when received? | What can be taxable later |
|---|---|---|
| Cash, a bank account or a CD | No | Interest earned after death |
| Stocks, mutual funds or a brokerage account | No | Dividends after death; gain on a sale above the value at death |
| A house, condo or land | No | Rent after death; gain on a sale above the value at death; property tax going forward |
| Traditional IRA, 401(k), 403(b), 457(b) | No, until money is withdrawn | Each distribution of pretax money is ordinary income |
| Roth IRA or Roth 401(k) | No | Usually nothing, if the account met the five-year rule |
| Annuity | No, until paid | The part of each payment above the owner’s investment |
| Life insurance proceeds | Generally no | Interest paid on proceeds held by the insurer |
| U.S. savings bonds | No | Interest the decedent had not reported, when it is reported |
| Money from a trust or an estate | Principal: no | The share of the trust’s or estate’s income reported to you on Schedule K-1 |
| Final wages, bonus or other income owed to the decedent | Yes, to whoever receives it | The payment itself (income in respect of a decedent) |
Inherited cash, bank accounts and payable-on-death accounts
Cash in the decedent’s account on the date of death is principal. Interest that accrues after death is income: to the estate if the account stays in the estate, or to you once the account is yours. A payable-on-death or joint account passes outside probate, but the income-tax rule is the same, and the account still counts in the federal gross estate. Do beneficiaries pay taxes on bank accounts? Only on the income the account generates — interest after death, plus any income earned before death that had not yet been taxed (income in respect of a decedent). Is inherited money taxable? Not the cash itself; only that income.
Inherited stocks and brokerage accounts
Inherited stocks, bonds and fund shares take a basis equal to their value at death, so selling them soon after death usually produces little gain or loss (see step-up in basis). Dividends and interest after death are taxable to whoever owns the account when they are paid. Ask the brokerage to record the date-of-death value in the new account, and keep the statement.
Life insurance proceeds
Life insurance paid because of the insured’s death is generally not taxable income to the beneficiary, and Florida taxes none of it (IRS Publication 525). Interest the insurer pays on proceeds it holds, or installment payments that include interest, are taxable. Separately, a policy the decedent owned or controlled is generally included in the federal gross estate, which matters only for estates near the exclusion; that is why large estates sometimes use an irrevocable life insurance trust (see planning).
Money from a trust or an estate
A distribution of principal from a trust or an estate is not income to you. When the trust or estate has earned income during the year and distributes it, the income generally “carries out” to the beneficiary, who reports the share shown on Schedule K-1; the trust or estate deducts what it passed through. Is inheritance from a trust taxable, or is money inherited from an irrevocable trust taxable? The principal is not; your share of the trust’s income for the year may be. Is money left to me in a will taxable? The same answer applies. See the estate’s income taxes.
Savings bonds, final paychecks and other income in respect of a decedent
“Income in respect of a decedent” is income the decedent had earned or was entitled to but had not been taxed on: the balance of a traditional IRA or 401(k), deferred compensation, a final paycheck or bonus, accrued savings bond interest, installment-sale payments and similar items. It is taxed to whoever receives it, it does not get a step-up in basis, and if the estate paid federal estate tax, the recipient may be able to deduct the estate tax attributable to it (Publication 559). Executor fees are different again: a personal representative who is paid for administering the estate reports that compensation as income.
Do I have to report an inheritance to the IRS?
Not as income. There is no federal form for reporting an ordinary inheritance from a U.S. estate, and you do not list the inheritance on your Form 1040. You report the related taxable income on the appropriate return, using documents you receive — Form 1099-R for retirement distributions, a Schedule K-1 from an estate or trust, Form 1099-INT or 1099-DIV for income after death, and Form 1099-S when you sell inherited real estate (the sale is then reported on Form 8949 and Schedule D). One reporting form applies to the inheritance itself: a U.S. person who receives more than $100,000 in a year from a nonresident alien individual or a foreign estate generally files Form 3520 (see inheritances from abroad).
The federal estate tax on a Florida estate in 2026
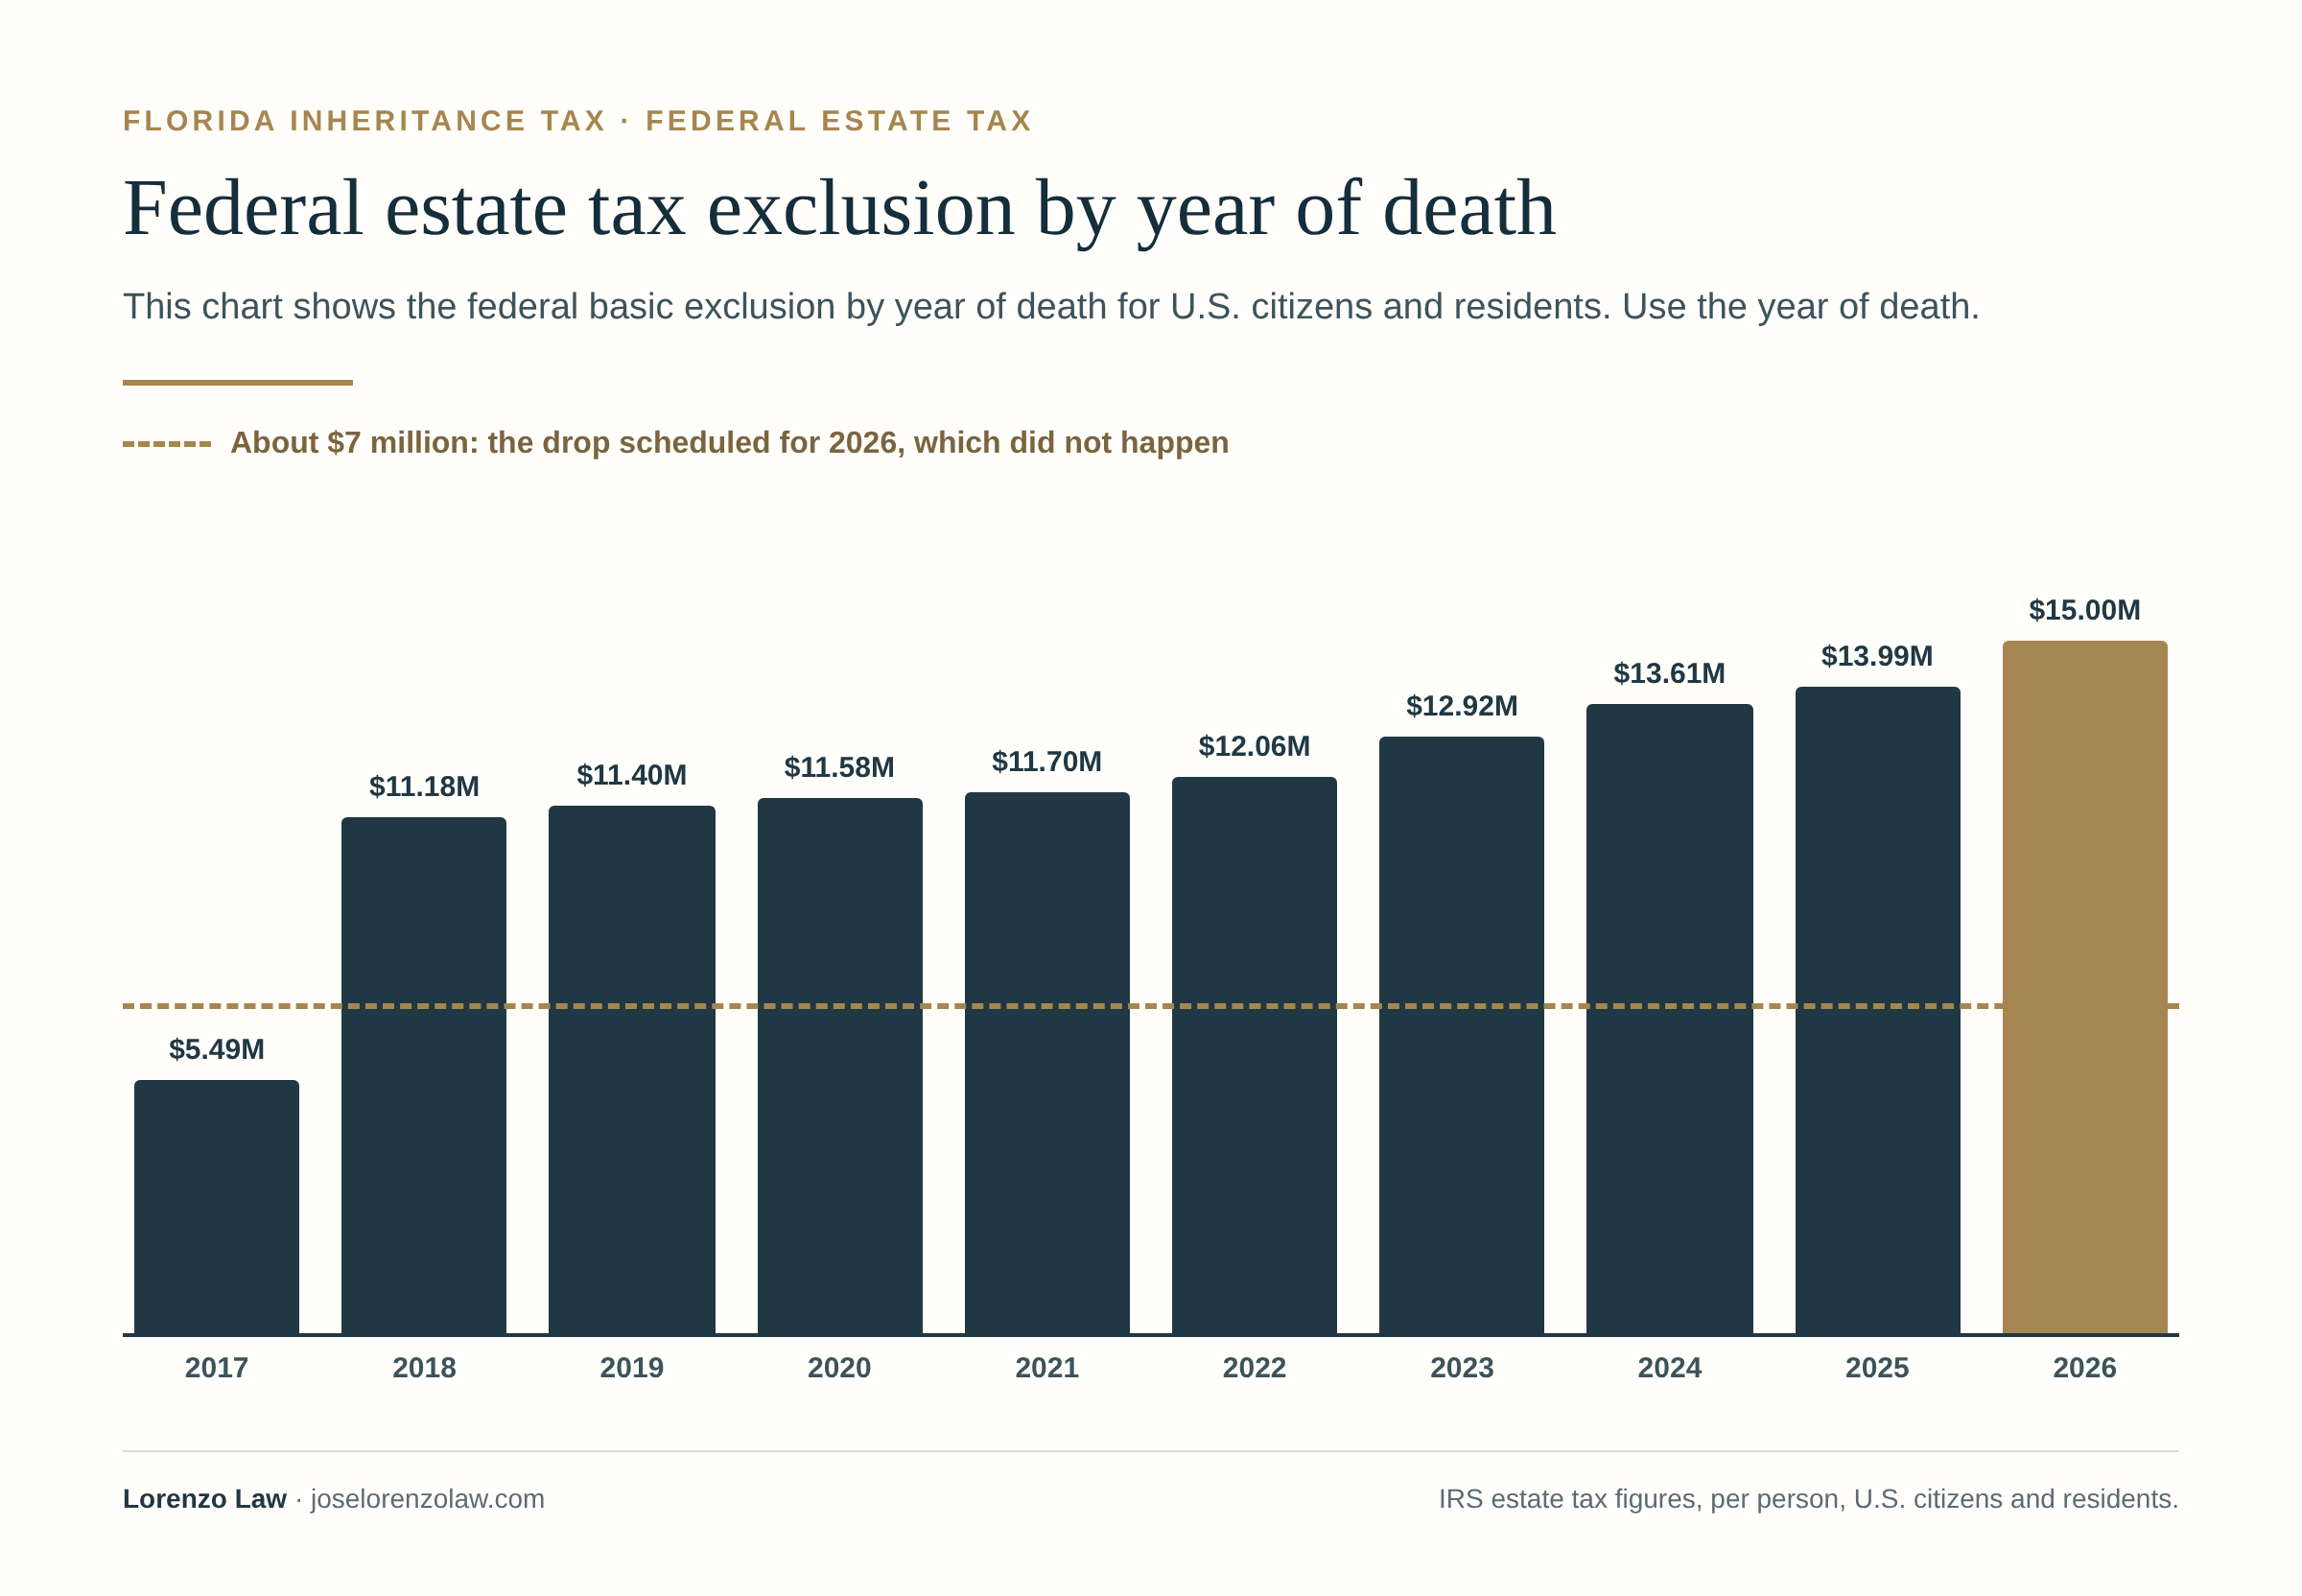
For a U.S. citizen or resident who dies in 2026, the federal basic exclusion amount is $15 million; for a death in 2025 it was $13.99 million (IRS). Federal law enacted in July 2025, the One Big Beautiful Bill Act, set the 2026 figure and removed the drop that had been scheduled for 2026; the amount is indexed for inflation for later years. Florida estates are subject to the federal estate tax like estates anywhere in the country. The tax is computed on the estate, paid by the personal representative from estate assets, and charged at graduated rates up to 40 percent on the taxable estate above what the exclusion covers.
For a 2026 death, the federal estate tax exemption 2026 figure is that $15 million basic exclusion. There is no separate Florida estate tax exemption 2026 or FL estate tax exemption 2026: Florida has no estate tax exemption of its own because it has no estate tax. The federal exclusion is a separate question, and another state’s rules can also matter. The figure belongs to the year of death: an estate of someone who died in 2025 uses $13.99 million, and a later year uses that year’s indexed amount, which should be checked when the time comes rather than assumed.
Did the estate tax exemption drop to $7 million in 2026?
No. Before July 2025, the temporarily doubled exclusion was scheduled to fall back to roughly half, about $7 million per person, on January 1, 2026. That “sunset” never took effect: the 2025 law set the basic exclusion at $15 million for 2026 deaths and indexes it afterward. Plans written in earlier years around the expected sunset, especially formula clauses that split assets between a family trust and a spouse, should be reviewed against current figures; a clause drafted for a $7 million world can produce a different division at $15 million.
Federal estate tax exemption by year of death
| Year of death or gift | Basic exclusion amount (per person) | Annual gift tax exclusion (per recipient) |
|---|---|---|
| 2026 | $15,000,000 | $19,000 |
| 2025 | $13,990,000 | $19,000 |
| 2024 | $13,610,000 | $18,000 |
| 2023 | $12,920,000 | $17,000 |
| 2022 | $12,060,000 | $16,000 |
| 2021 | $11,700,000 | $15,000 |
| 2020 | $11,580,000 | $15,000 |
| 2019 | $11,400,000 | $15,000 |
| 2018 | $11,180,000 | $15,000 |
| 2017 | $5,490,000 | $14,000 |
| 2016 | $5,450,000 | $14,000 |
| 2015 | $5,430,000 | $14,000 |
| 2014 | $5,340,000 | $14,000 |
| 2013 | $5,250,000 | $14,000 |
| 2012 | $5,120,000 | $13,000 |
Source: IRS estate-tax filing thresholds by year of death and the IRS gift-tax annual exclusion by year (IRS gift tax FAQs). The 2026 federal estate tax exemption is the top row; the 2012 estate tax exemption, for example, was $5.12 million. Use the row for the year of death (for the estate) or the year of the gift. An estate of someone who died in 2021, 2022 or 2023 that is still being settled uses that year’s figure, not today’s.
Who must file Form 706, and when it is due
The filing test is broader than the probate inventory. For a citizen or resident, add the gross estate, the decedent’s adjusted taxable gifts made after 1976 and any specific gift-tax exemption used before 1977, and compare the total with the basic exclusion for the year of death (IRC § 2001(b); Form 706 instructions, “Who Must File”). The gross estate includes real estate, investments and business interests, and, depending on the facts, life insurance the decedent controlled, jointly owned property, payable-on-death and transfer-on-death accounts, retirement accounts and property in a revocable trust. Passing outside probate does not take an asset out of the federal gross estate.
Shares in a private company, a family LLC or a partnership interest are included at fair market value on the date of death, and because there is no market price the value usually comes from a qualified business appraisal. Depending on the facts, an appraiser may apply discounts for a minority interest or for limited marketability, and the IRS can challenge them. When a closely held business interest exceeds 35 percent of the adjusted gross estate, federal law lets the estate tax attributable to that interest be paid in installments if the estate qualifies (Internal Revenue Code § 6166). A buy-sell agreement, option, or other transfer restriction is disregarded in valuing the interest (IRC § 2703(a)) unless it satisfies all three statutory tests — it is a bona fide business arrangement, it is not a device to transfer property to the decedent’s family for less than full and adequate consideration, and its terms are comparable to arm’s-length arrangements (IRC § 2703(b)); and for family-controlled entities, certain lapsing voting or liquidation rights are treated as transfers and certain liquidation restrictions are disregarded for valuation, which can limit discounts (IRC § 2704). Inheritance tax on shares in a private company is not a Florida question; the federal estate tax, the step-up in basis and the company’s own transfer restrictions are.
A required return does not mean tax is due: the marital deduction, the charitable deduction, debts and expenses can bring the taxable estate to zero. A small probate estate does not prove a return is unnecessary either. Form 706 is generally due nine months after the date of death. A timely Form 4768 obtains an automatic six-month extension of time to file, but a filing extension does not extend the time to pay; an extension of time to pay, or installment payments for certain closely held businesses, has separate requirements. Check any IRS disaster relief and confirm the actual due date with the preparer. Covered estates must also send Form 8971 basis statements to beneficiaries (see basis statements).
The federal estate tax rate
The federal estate tax rate schedule is graduated from 18 percent to 40 percent, but the exclusion absorbs the lower brackets. In practice, for a 2026 death, each dollar of taxable estate above what the exclusion covers is taxed at 40 percent. The 40 percent figure is a top rate on the excess, not a flat tax on every inheritance, and most Florida estates owe nothing. So what is the federal estate tax rate? A top rate of 40 percent on the excess. The estate tax percentage and the estate tax amount depend on how far the taxable estate exceeds the exclusion, and how much is estate tax in Florida, or what is the Florida estate tax rate, comes back to this federal schedule, because Florida’s own rate is zero. The worked examples show the arithmetic.
Portability: using a deceased spouse’s unused exclusion
Portability lets a surviving spouse add the deceased spouse’s unused exclusion, called the DSUE amount, to the survivor’s own exclusion. It is not automatic: the executor must elect it on a complete, timely filed Form 706, even when the estate owes no tax and would not otherwise have to file (Form 706 instructions, portability). An estate that missed the ordinary deadline may be able to elect late, within five years after the death, under Revenue Procedure 2022-32, if it meets every condition.
Is the exemption automatically $30 million for a married couple?
No. A married couple can shelter up to two exclusions, $30 million at 2026 figures, only if the first spouse’s unused amount is preserved: by a portability election on the first spouse’s Form 706, or by planning that uses the first spouse’s exclusion at the first death, such as a credit-shelter (bypass or family) trust. The usable amount depends on the first spouse’s taxable gifts and bequests, the date of death and the last deceased spouse rule. Portability applies to the estate and gift tax exclusion, not to the separate generation-skipping transfer tax exemption. And because a second marriage can change who the “last deceased spouse” is, a widow or widower who remarries should review the plan.
Portability matters even in a Florida estate far below $15 million. Electing it costs a return, but it can protect the survivor if assets grow, if the law changes, or if the survivor inherits more. A Florida surviving spouse who is deciding whether to file should weigh the cost of preparing the return against those risks with the preparer. See also estate planning for widows in Florida.
What if Form 706 was never filed? The five-year late election
Revenue Procedure 2022-32 provides a simplified method for a late portability election when the decedent died after December 31, 2010, was a U.S. citizen or resident at death, left a surviving spouse, and the estate was not otherwise required to file a return under the gross-estate-and-gifts test (Rev. Proc. 2022-32, §§ 3–5). A complete, properly prepared Form 706 bearing the required notation must be filed on or before the fifth anniversary of the death. The method does not help an estate that was required to file. After five years, some otherwise eligible estates may request a private letter ruling, and relief is not assured. There is no IRS user fee for the simplified method, but preparation is professional work. Refund limitation periods remain separate.
Who pays the estate tax: the estate or the beneficiaries?
The estate files and pays. The personal representative is responsible for the federal estate tax return and pays the tax from estate assets before distribution. Who ultimately bears that cost among the beneficiaries is a separate question, governed by the will and trust and, where they are silent, by Florida’s estate tax apportionment statute, § 733.817. The beneficiaries do not each receive a tax bill, but the tax can reduce what each receives, and nonprobate recipients can be required to contribute their share (see nonprobate property).
Who pays inheritance tax in Florida? No one, because there is none. Who pays estate tax? The estate, through the personal representative; and who is liable for inheritance tax in a state that has one is decided by that state’s law. Do beneficiaries have to pay the estate tax bill? Not directly, but the tax can reduce what each receives, and recipients of nonprobate assets can be required to contribute. Can an estate pay taxes instead of the beneficiary? For the federal estate tax, that is how it works. Does the estate tax come out of my share or off the top, and if federal estate tax is owed, which beneficiary pays it? The estate pays; the statute and the documents decide whose share it comes out of.
Florida’s estate tax apportionment statute
Unless a governing instrument effectively directs otherwise, § 733.817 apportions the tax among the interests that are included in the measure of the tax, generally in proportion to their value, and interests that generate a marital or charitable deduction generally bear none of it. The statute has detailed charging rules, including rules for property passing under a will, under a revocable trust and outside both, and for nonresiduary gifts. It does not divide every tax bill equally among the heirs, and it is not a rule that the residuary beneficiaries always bear everything.
Life insurance, joint accounts and other nonprobate property
Property passing outside probate can bear its share when it is included in the measure of the tax. A life insurance beneficiary, a joint-account survivor, a payable-on-death beneficiary or a retirement-account beneficiary can be asked to contribute, and federal law separately gives the estate rights to recover tax from certain recipients. Survivorship ownership is not an automatic exemption from apportionment. Personal representatives should identify nonprobate recipients early, because collecting from someone who has already spent a distribution is harder than reserving for it.
Tax clauses in wills and trusts
A will or trust can shift the burden, for example by directing that all estate taxes be paid from the residue, or that a particular gift bear its own tax. Florida requires a clear direction for some shifts (§ 733.817(4)(b)–(c)), and a general instruction to “pay all taxes” does not necessarily shift tax on property passing outside the will. Conflicting instruments, a will that says one thing and a trust that says another, and spouse-related interests need a reading of the actual documents and the current statute. Bring the complete will, trust and every amendment to the review.
Florida courts have applied § 733.817 in several decisions. A surviving spouse’s elective share that fully qualifies for the marital deduction generates no estate tax and bears none of it; the tax falls on the residuary beneficiaries whose property generated it (Tarbox v. Palmer, 564 So. 2d 1106 (Fla. 4th DCA 1990)). A surviving joint tenant is liable for the estate tax attributable to the decedent’s interest in jointly held survivorship property, unless the will directs otherwise (Pfeifer v. Varner, 452 So. 2d 622 (Fla. 3d DCA 1984)). To shift the tax to the estate for property passing outside the will, a tax clause must expressly refer to the apportionment statute or expressly state that the estate bears that tax; a general “pay all taxes” clause is not enough (Ferrone v. Soffes, 558 So. 2d 146 (Fla. 3d DCA 1990)). And where a will’s clause is insufficient under the statute, equitable apportionment governs — there, as to life-insurance proceeds (In re Estate of McClaran, 811 So. 2d 799 (Fla. 2d DCA 2002)). These decisions applied earlier subsection numbering; the express-direction rule now appears in § 733.817(4)(b)–(c).
When a surviving spouse’s share does not qualify for the marital deduction, as with an elective share passing to a spouse who is not a U.S. citizen without a qualified domestic trust, that share can be charged with estate tax (Boulis v. Blackburn, 16 So. 3d 186 (Fla. 4th DCA 2009)).
No will does not mean no tax direction
Dying without a will does not create a Florida inheritance tax, and it does not mean no instrument governs the tax. A person who dies intestate may still have a revocable trust, beneficiary designations or other documents with their own directions. Where nothing directs otherwise, § 733.817 applies. Can anyone shift the estate tax burden when there is no will? Only through those other instruments or as the statute provides.
Worked examples: what a Florida estate would owe at different sizes
These examples assume a U.S. citizen domiciled in Florida who dies in 2026, no taxable gifts during life, and no estate or inheritance tax in another state. Each dollar figure is the gross estate; the examples assume no debts or expenses, so the gross estate — the figure the Form 706 filing test uses — is the figure shown. The marital and charitable deductions shown reduce the tax, not the filing test. They are hypothetical and show arithmetic only. Real estates have deductions, valuation questions, prior gifts and elections that change the result, and the return should be prepared by a qualified tax professional.
| Estate | Who receives it | Form 706? | Federal estate tax | What heirs should still check |
|---|---|---|---|---|
| $1,000,000, single, including a $400,000 traditional IRA | Two children | Not required | $0 | Income tax on IRA withdrawals; the 10-year rule; Florida inheritance tax is $0 |
| $3,000,000, married | Surviving spouse | Not required, but filing to elect portability can preserve the unused exclusion | $0 | Portability decision within nine months (or the five-year late election) |
| $5,000,000, single, Florida home and investments | Three children | Not required unless prior taxable gifts push the total over $15,000,000 | $0 | Property-tax reset on the home; basis records for a later sale |
| $10,000,000, married | Surviving spouse | Not required; a portability election is worth weighing | $0 (marital deduction) | A $15,000,000 DSUE amount can carry to the survivor if elected |
| $20,000,000, single | Children | Required (gross estate above $15,000,000) | $2,000,000 (40 percent of the $5,000,000 above the exclusion) | Who bears the tax under the will, trust and § 733.817; liquidity to pay within nine months |
| $20,000,000 | $10,000,000 to a surviving spouse and $10,000,000 to a church | Required | $0 (marital and charitable deductions) | The return is still due even though no tax is owed |
| $25,000,000, surviving spouse who inherited from a spouse who died in 2026 with a portability election | Children, at the survivor’s death | Required | $0 if the survivor’s own exclusion plus the $15,000,000 DSUE amount covers $25,000,000; about $4,000,000 without portability | The election at the first death is what makes the difference |
How the $2,000,000 figure works: a $20,000,000 taxable estate less the $15,000,000 the exclusion covers leaves $5,000,000, and the top rate of 40 percent applies to that excess. The last row assumes, for simplicity, that the survivor also dies in a year with a $15,000,000 basic exclusion.
The same arithmetic answers the conversational questions people ask after “I live in Florida”: an estate of $3 million, $4 million, $5 million or $10 million owes no federal estate tax in 2026 unless prior taxable gifts are large, and a married couple filing jointly still has two separate estates, each with its own exclusion. The tax that more often reaches heirs in estates of that size is income tax on retirement accounts.
Inherited IRAs, 401(k)s, Roth IRAs and annuities
Florida does not tax an inherited retirement account, but federal income tax does. Distributions from an inherited traditional IRA, 401(k), 403(b) or 457(b) are ordinary income to the beneficiary to the extent they represent pretax money, and the account does not get a step-up in basis. Qualified distributions from an inherited Roth IRA are generally tax-free. How fast the money must come out depends on who the beneficiary is, when the owner died and whether the owner had reached the required beginning date (IRS Publication 590-B).
The sections below take the account questions one at a time for Florida beneficiaries: income tax, Roth accounts, the 10-year rule, the yearly distribution, successors, rule changes, eligible designated beneficiaries, spouses, trusts, annuities and missed distributions. Who receives the account is a separate question decided by the beneficiary designation; see beneficiary designations for retirement plans.
Do I pay income tax on an inherited IRA or 401(k)?
Yes. For an inherited traditional IRA or an inherited 401(k), you pay tax on the pretax part of each withdrawal, at your ordinary federal income tax rate for the year you take it, and no Florida income tax. If the owner made nondeductible contributions, part of each distribution is a tax-free return of that basis, which is why the owner’s Form 8606 records matter. Employer plans can also hold after-tax or Roth amounts. “Every dollar is taxable” is therefore too broad: obtain the account statements, the beneficiary designation and any basis records before choosing how to withdraw. Distributions to a beneficiary because of the owner’s death are generally not subject to the additional 10 percent tax on early withdrawals, even if the beneficiary is under 59½. Inherited IRA withdrawals are not earned income; they can, however, raise your taxable income for the year and affect means-tested benefits, so time large withdrawals with your tax adviser. That is the short answer on inherited IRA tax: are inherited IRAs taxable? Yes, to the extent of pretax money, and Florida adds no tax of its own to taxes on inherited IRA withdrawals. These beneficiary IRA tax rules apply to every beneficiary, while the non-spousal inherited IRA rules below decide how fast the money must come out.
Inherited Roth IRA rules
Distributions from an inherited Roth IRA are generally tax-free if the Roth account satisfied the five-year holding period, counted from the owner’s first Roth contribution. If the five years had not run, earnings withdrawn before they do can be taxable, though contributions come out first and tax-free. Tax-free does not mean the account can stay untouched forever: a non-spouse designated beneficiary who is not an eligible designated beneficiary generally must empty an inherited Roth IRA by the end of the tenth year after death, although annual withdrawals (RMDs) are generally not required under the IRS rules in the meantime because a Roth owner is treated as dying before the required beginning date. Does an inherited Roth IRA have to be emptied in ten years too? For many beneficiaries yes, for a spouse and other eligible designated beneficiaries the rules differ.
Can I wait ten years to empty an inherited IRA?
Not always. This is the inherited IRA 10 year rule. Under the SECURE Act, for many individual beneficiaries who are not eligible designated beneficiaries, an account inherited from an owner who died after December 31, 2019 must be fully distributed by December 31 of the year containing the tenth anniversary of the death. For an owner who dies in 2026, that is December 31, 2036, if the rule applies. If the owner died on or after the required beginning date, the beneficiary must also take annual required minimum distributions in years one through nine. If the owner died before that date, the 10-year rule generally does not require annual withdrawals before the final year. Any required distribution the owner had not taken in the year of death must be checked separately. The IRS waived penalties for some missed annual distributions during the transition years; do not assume that relief covers the current year. Spreading withdrawals over several years can keep income in lower brackets, but the right schedule is a tax-planning decision.
How the yearly inherited IRA distribution is calculated
The inherited IRA RMD follows the inherited IRA distribution rules above. When annual withdrawals are required, whether within the 10-year period or over an eligible designated beneficiary’s life expectancy, the amount is the prior-year-end account balance divided by a life-expectancy figure from the IRS Single Life Expectancy Table. A non-spouse beneficiary uses the figure for his or her age in the year after the owner’s death, then subtracts one each later year. When the owner had already reached the required beginning date, the beneficiary uses the longer of his or her own life expectancy or the owner’s remaining life expectancy (Publication 590-B, Appendix B). Each distribution is ordinary income to the extent it is pretax money, so the tax rate on an RMD from an inherited IRA is the beneficiary’s own federal bracket for that year. The custodian usually calculates the figure, but the beneficiary is responsible for taking it.
Successor beneficiaries: when the beneficiary dies too
If a beneficiary dies before emptying an inherited IRA, the successor beneficiary (determined under the plan or IRA agreement) takes over the remaining balance. The successor does not get a fresh start. If the first beneficiary was an eligible designated beneficiary taking life-expectancy payments, the rest generally must be distributed within 10 years after that beneficiary’s death; if the first beneficiary was already under a 10-year deadline, the successor generally inherits that same deadline, and any annual distributions continue (Publication 590-B, “Death of a beneficiary”). Can you inherit an already inherited IRA? Yes, but only on these shortened terms, so the IRA agreement’s successor terms, and any successor designation the first beneficiary files under them, deserve the same attention as the owner’s designation.
How the inherited IRA rules changed from 2020 to 2025
- 2020: the SECURE Act’s 10-year rule began to apply to owners who died after 2019, ending the lifetime “stretch” for most non-spouse beneficiaries.
- 2020: the CARES Act waived required minimum distributions for 2020, including for beneficiaries with inherited IRAs (IRS, coronavirus relief for retirement plans and IRAs).
- 2022: proposed IRS regulations read the 10-year rule to require annual distributions in years one through nine when the owner died on or after the required beginning date.
- 2021 to 2024: IRS Notices 2022-53, 2023-54 and 2024-35 said the IRS would not assert the excise tax for those “specified” annual distributions that beneficiaries missed in 2021, 2022, 2023 and 2024 (Notice 2024-35).
- July 2024: Treasury and the IRS issued final regulations (T.D. 10001, 89 Fed. Reg. 58907 (July 19, 2024)) that kept the annual-distribution requirement (IRS, IR-2024-190); they apply to distributions for 2025 and later years.
When did the inherited IRA rules change? The SECURE Act changed them for owners who died after December 31, 2019. The annual-distribution requirement came from IRS regulations: a proposed rule on inherited retirement accounts in 2022, yearly notices that gave relief for specified annual distributions missed in 2021 through 2024 (relief, not delays of the rule itself), and final regulations that apply from 2025. Questions about the latest IRS guidelines, rulings or new guidelines on inherited IRAs come back to that history. A past relief notice does not establish a waiver for a later year, and later IRS announcements concern other SECURE 2.0 rules that are still being finalized; check current IRS guidance for the year of the distribution.
Eligible designated beneficiaries: who is exempt from the 10-year rule
- A surviving spouse, who has the widest set of options (below).
- The owner’s minor child, who can take distributions over life expectancy until reaching the age of majority (age 21 under the regulations), after which the 10-year period begins.
- A disabled or chronically ill individual, as defined in the tax rules, with documentation.
- An individual not more than ten years younger than the owner, such as a sibling close in age.
An estate, a charity or a trust that does not qualify for look-through treatment is not a designated beneficiary at all and follows different payout rules, often five years if the owner died before the required beginning date. Some trusts qualify for look-through treatment and are treated as if the trust beneficiaries were named. Accounts inherited from owners who died before 2020 can still use the older “stretch IRA” rules for the original beneficiary. Plan terms can be stricter than the tax rules.
Options for a surviving spouse
A surviving spouse who is the sole beneficiary can usually treat an inherited IRA as the spouse’s own, roll it over into the spouse’s own IRA, or keep it as an inherited IRA. Treating it as one’s own delays required distributions to the spouse’s own required beginning date but subjects withdrawals before 59½ to the additional 10 percent tax; keeping it as an inherited account allows penalty-free access at any age. A sole surviving-spouse beneficiary may also elect to be treated as the deceased owner for required-distribution purposes (effective 2024). No choice is automatically better. Age, need for the money and the spouse’s own required distributions decide it. Confirm the route with the custodian and tax adviser before a rollover, because some choices cannot be undone.
Trusts and estates named as beneficiary
Naming a trust as the beneficiary of a retirement account can protect a young, disabled or financially vulnerable beneficiary, but the tax consequences depend on whether the trust qualifies as a see-through trust and whether it passes distributions out (a conduit trust) or keeps them (an accumulation trust). Income kept inside a trust is taxed at compressed trust brackets. An IRA left to the estate, by naming the estate or leaving no beneficiary so the account falls into the estate, usually shortens the payout period and brings the account into probate. Review the designation with the trust document; see what beneficiary designations override in Florida.
Inherited annuities
An annuity held inside an IRA or employer plan follows the retirement-account rules above. A non-qualified annuity, bought with after-tax money, is taxed differently: the beneficiary owes ordinary income tax on the gain above the owner’s investment, and the contract’s death-benefit rules, commonly a five-year payout or an annuitization over the beneficiary’s life that begins within a year, govern the distribution timing; a surviving spouse can often continue the contract. A non-spouse beneficiary cannot roll an inherited non-qualified annuity into an IRA, because it is not retirement-plan money and no rollover is available for it; whether the contract can be exchanged into another annuity on the same payout terms depends on the contract and the federal rules for beneficiaries, so ask the insurer and the tax adviser before surrendering it. An annuity that sits inside an IRA or employer plan can be moved by direct transfer to an inherited IRA like any other plan asset. Inherited annuity taxes are income taxes; Florida does not tax them.
What happens if a required distribution from an inherited IRA is missed?
Contact the custodian and the tax adviser promptly and take the missed amount. Federal law imposes an excise tax on a required distribution that is not taken, 25 percent of the shortfall, reduced to 10 percent if the error is corrected within the correction window, and the IRS can waive it for reasonable error when the shortfall is corrected and a waiver is requested on Form 5329. Do not assume past IRS transition relief eliminates a current-year obligation.
The deduction for estate tax paid on inherited retirement income
When an estate paid federal estate tax and the estate included an IRA, 401(k) or other income in respect of a decedent, the beneficiary who later reports that income may claim an itemized deduction for the estate tax attributable to it (Internal Revenue Code § 691(c)). The amount and timing depend on the taxpayer and the income, and the deduction matters only for estates that actually paid federal estate tax (Publication 559, “Estate Tax Deduction”).
Splitting, titling, converting and creditor protection
Several beneficiaries can usually split an inherited IRA into separate inherited accounts so each can follow his or her own schedule; doing it by December 31 of the year after death preserves the most flexibility. The account is retitled as an inherited or beneficiary IRA, typically in the decedent’s name for the benefit of the beneficiary, and moved only by trustee-to-trustee transfer: a non-spouse beneficiary cannot use a 60-day rollover, cannot add contributions, and cannot convert an inherited IRA to a Roth IRA, although an inherited employer-plan account can, in some cases, be converted by direct rollover to an inherited Roth IRA. A beneficiary who is at least 70½ can make qualified charitable distributions from an inherited IRA. Are inherited IRAs protected from creditors? Florida law separately protects an inherited IRA from creditors of the beneficiary (§ 222.21). Because Florida has opted out of the federal bankruptcy exemptions (§ 222.20), a Florida-domiciled debtor claims exemptions under Florida law, and § 222.21(2)(c) expressly exempts an inherited IRA — so Clark v. Rameker, which held only that an inherited IRA is not an exempt “retirement fund” under the federal exemption (11 U.S.C. § 522(b)(3)(C)), does not defeat the Florida exemption. Other states’ laws can differ. Inherited IRA distributions are reported on Form 1099-R, with distribution code 4 for death (code T or Q may appear for a Roth).
Opening the account, growth, withholding and other practical points
- How to open an inherited IRA. The beneficiary gives the custodian a death certificate and a claim form, and the custodian opens an inherited IRA titled with the decedent’s name for the beneficiary’s benefit; the money then moves by trustee-to-trustee transfer, not a check. The custodian files Form 5498 each year reporting the account’s value; the beneficiary does not file it.
- Do inherited IRAs continue to grow? Investments can remain in an inherited IRA, and their value can rise or fall; earnings are not taxed while inside a traditional account, and tax is owed only on withdrawal (Publication 590-B). Qualified Roth growth comes out tax-free.
- Withholding. Federal income tax is withheld from an IRA withdrawal at 10 percent unless you choose another rate, from 0 to 100 percent, on Form W-4R; a distribution from an employer plan that is eligible for rollover is subject to 20 percent withholding unless it goes by direct rollover to an inherited IRA (IRS, pensions and annuity withholding). Withholding is a prepayment, not the tax: how much to withhold from an inherited IRA depends on your bracket, and estimated payments are an alternative.
- A child beneficiary and the kiddie tax. Inherited IRA withdrawals are unearned income. For a child under 18, and some older students, unearned income above an annual IRS threshold ($2,700 on the IRS’s 2025 page) can be taxed at the parent’s rate on Form 8615 (IRS Topic 553).
- Pro rata rule and backdoor Roth. An inherited IRA is kept apart from your own IRAs: you cannot combine its basis with basis in your own traditional IRAs, and you file a separate Form 8606 for it (Publication 590-B). For that reason an IRA inherited from someone other than a spouse generally does not count toward the pro rata rule for a “backdoor” Roth conversion of your own IRAs, so it does not usually impact a backdoor Roth; a spouse who elects to treat the account as his or her own is different. Confirm the treatment with your tax preparer for the year of the conversion.
- Putting an inheritance into your own Roth IRA. Funding a Roth IRA with an inheritance, or investing inheritance money in a Roth IRA, is possible: inherited cash can pay for your own Roth contribution, but an inheritance is not compensation: contributions are limited to your taxable compensation for the year, up to the annual limit ($7,500 for 2026, or $8,600 at age 50 or older), and Roth income limits apply (IRS, IRA contribution limits). A nonspouse beneficiary cannot convert an inherited traditional IRA to a Roth IRA.
- Alternatives to the old stretch IRA. For owners planning now, the tools people consider include naming eligible designated beneficiaries where that fits the family, spreading withdrawals across the 10 years, lifetime Roth conversions, naming a charitable remainder trust as beneficiary, and life insurance to replace the tax. Each is a planning decision with trade-offs, not a way around the rules.
Inheriting a house in Florida: the taxes that can touch it
Florida charges no inheritance tax on an inherited house, condo or land. Four other things can: the property tax can increase when the Save Our Homes cap resets after the change of ownership; if you sell, federal capital gains tax applies only to gain above your basis, which generally starts at the value at death; documentary stamp tax applies to the deed when the property is sold; and rent from the property is income. If the estate is large enough, the house’s value also counts toward the federal estate tax, which the estate pays.
What is the inheritance tax in Florida on a house? None: there is no Florida inheritance tax on property, so the answer to “does Florida have an inheritance tax on property” is no. Do you pay taxes on inherited property in Florida? Not for receiving it. The inherited property taxes in Florida are the four listed above, and they are the tax implications of inheriting property in Florida; for inheriting a house in Florida, taxes come mainly from those sources; the estate may also owe federal estate tax, and another state’s tax can matter. How to avoid Florida inheritance tax on property? There is no inheritance tax to avoid; the planning questions are basis, the sale and the property-tax reset. The practical side of inheriting a home, from title to selling, is in Florida homestead property in probate, what the family does after a Lady Bird deed owner dies and when one sibling will not sell the inherited house.
Is there inheritance tax on a house in Florida?
No. Do I have to pay inheritance tax on my parents’ house in Florida? No: receiving the house is not taxed by Florida, and it is not income to you for federal purposes. What changes is the property tax going forward, and what matters later is your basis if you sell. If your parents lived in another state and owned the house in Florida, Florida still charges no inheritance tax; their home state’s rules are a separate question (see other states).
Step-up in basis: the value at death becomes your starting point
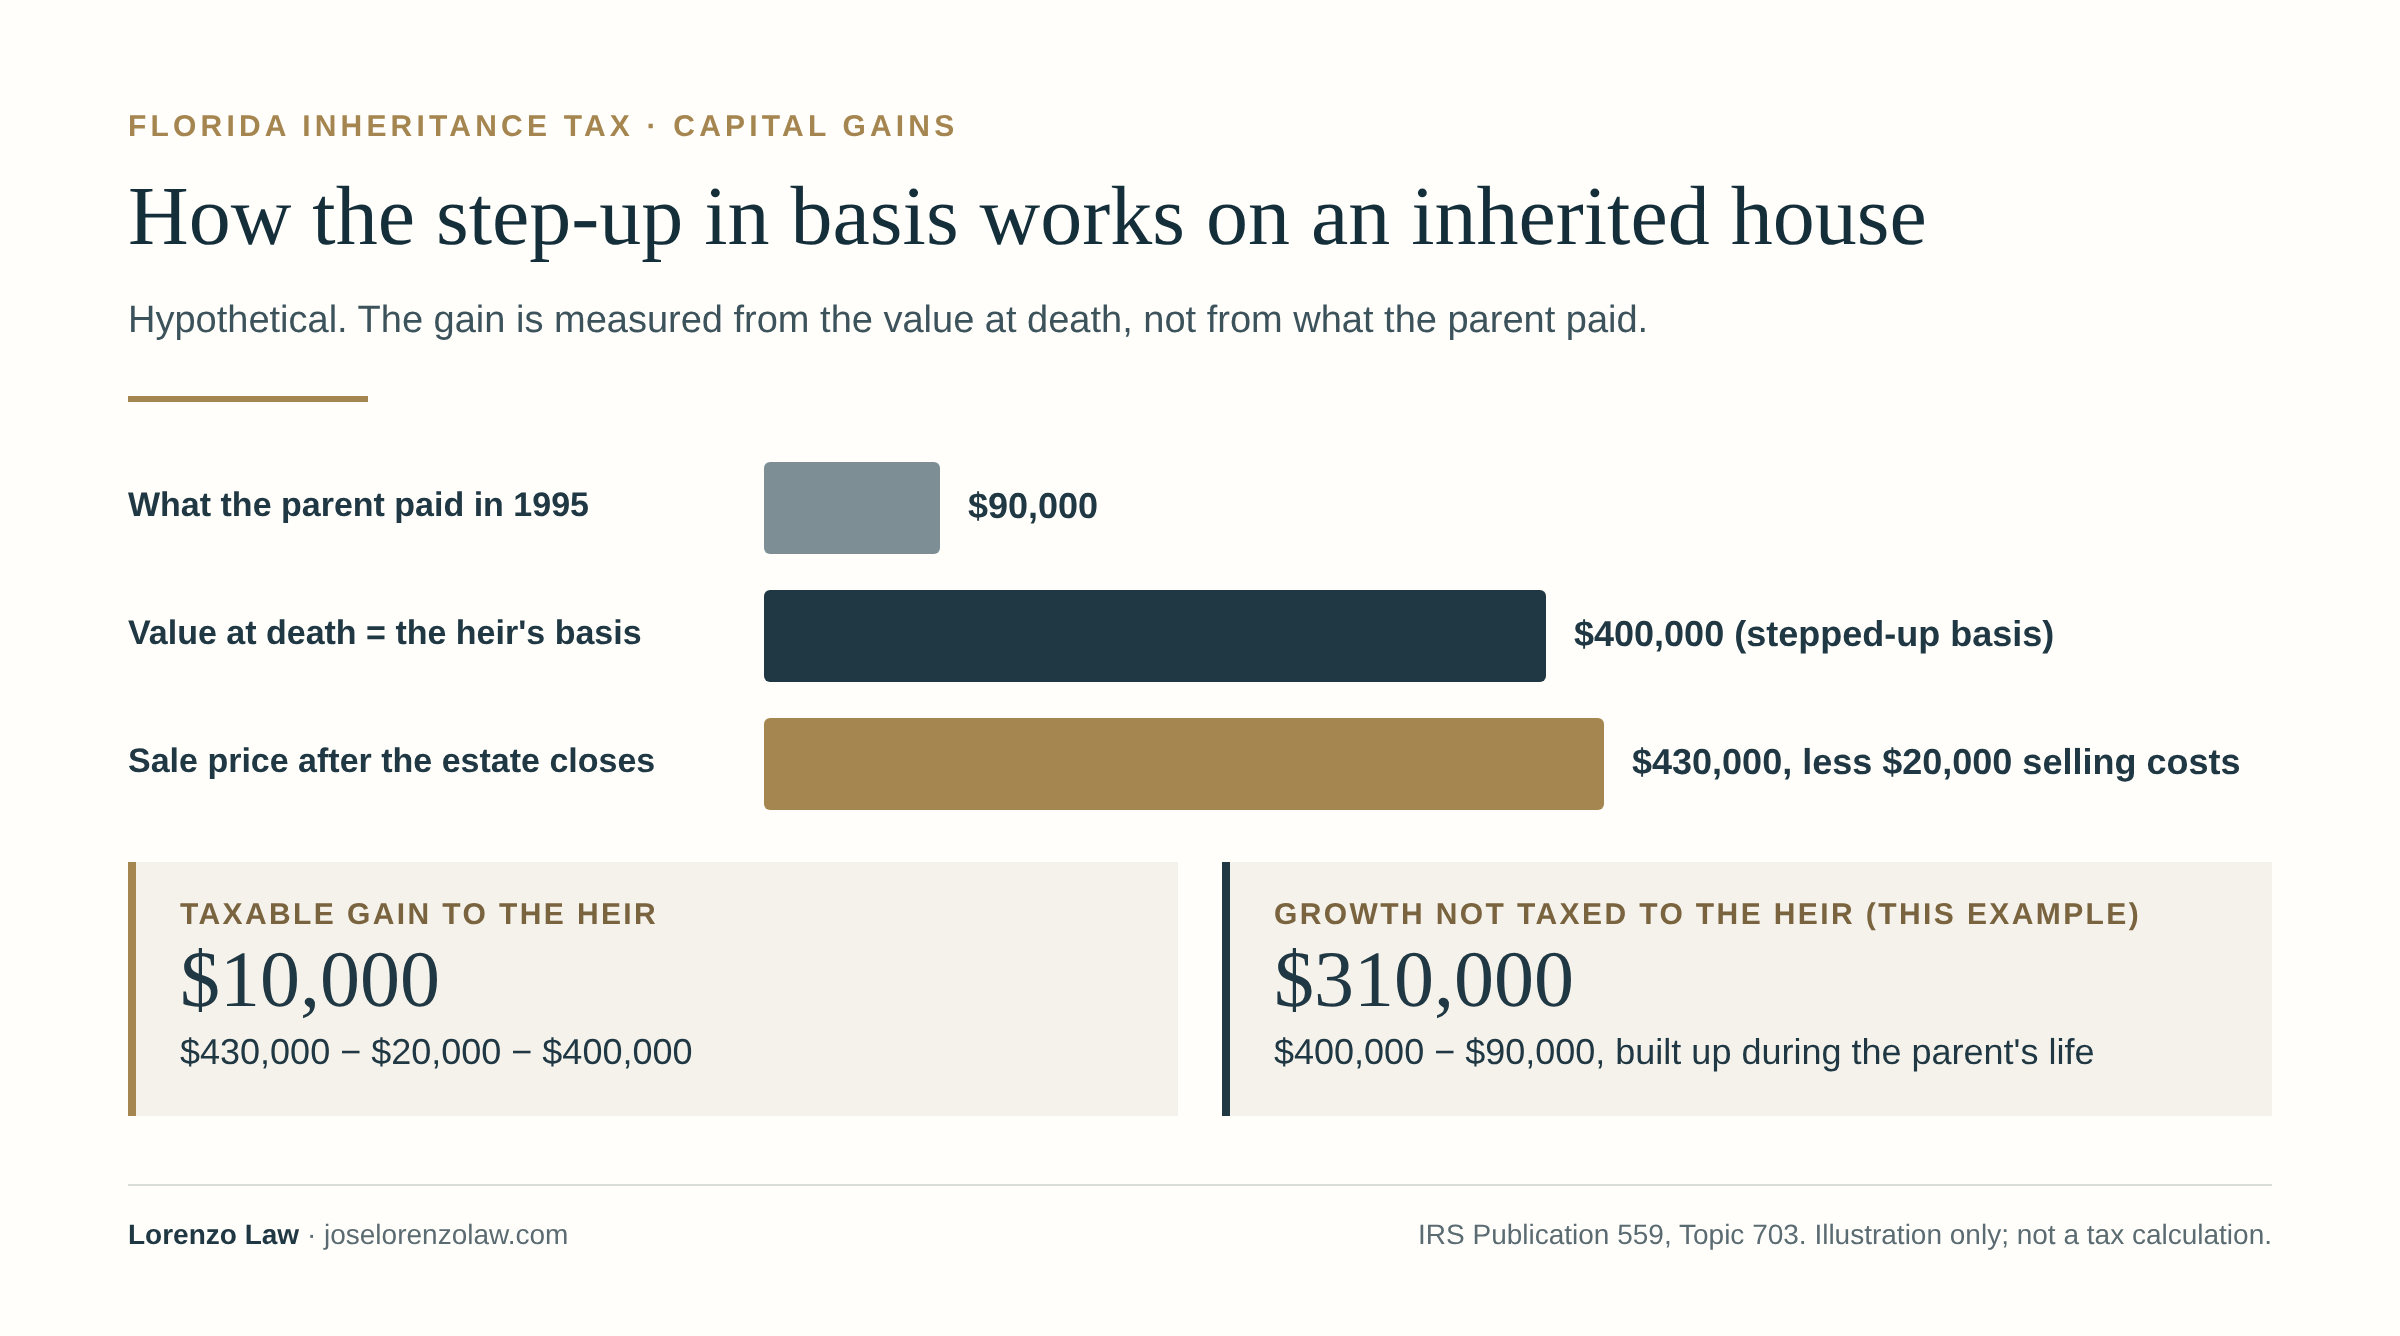
Basis is the figure used to measure gain or loss when property is sold. Inherited property generally takes a basis equal to its fair market value on the date of death, or on the alternate valuation date six months later if the estate elects it on Form 706, instead of what the decedent paid (Publication 559, “Inherited Property”). This is the stepped-up basis, or step-up in basis at death. If the property had lost value, the basis steps down: a step-down in basis means a loss on a later sale is measured from the lower value. Gain that built up during the decedent’s life is generally not taxed to the heir, subject to the limits below, which is why the step-up in basis on inherited Florida property is often worth more to a family than the estate-tax exclusion. Proposals in Congress aimed at eliminating the stepped-up basis at death, or at elimination of the step-up in basis for large gains, have been made from time to time; none applies to 2026 deaths, and this page describes the law in force rather than predicting changes.
The rule has limits. Income in respect of a decedent, such as a traditional IRA, does not step up. Property the decedent received as a gift within one year before death and that passes back to the original donor does not step up. Property in a trust steps up only if it is included in the decedent’s gross estate, which is true of a revocable living trust and of property under a Lady Bird deed but not of most irrevocable trusts. Inherited property is treated as held long-term, so any gain on a sale is a long-term capital gain however soon you sell. Get a written date-of-death appraisal for real estate, keep date-of-death statements for accounts, and do not use the county’s property-tax assessed value as your federal basis.
Surviving spouses, jointly owned property and community property
When spouses own a home as tenants by the entirety or as joint tenants with right of survivorship, generally half of the property is included in the first spouse’s estate, so under this spousal rule half steps up and the survivor keeps the original basis on the other half. Florida is not a community property state, so the full step-up that community property can receive in community-property states does not apply to ordinary Florida joint ownership. Florida’s Community Property Trust Act allows married couples to hold property in a qualifying community property trust (§§ 736.1501–736.1512), an option whose federal tax effect should be evaluated with a tax adviser. Whether assets in a Florida community property trust receive a full (double) basis step-up under federal law is unsettled. Property acquired while living in a community-property state may keep that character after a move to Florida. For joint owners who are not spouses, the part included in the estate is generally measured by the decedent’s contribution.
Gifting a house during life versus leaving it at death
A gift during life carries over the giver’s basis, so a child who receives a house as a gift and sells it can owe tax on all the appreciation since the parent bought it. The same house inherited at death would usually receive a stepped-up basis. That is why “should my parents put their house in my name” is usually a tax question as much as a probate question; see helping a parent with a Florida Lady Bird deed and Lady Bird deed tax consequences. A Lady Bird deed keeps the property in the owner’s estate, so the beneficiary generally receives the step-up, and it avoids probate for the home.
Do I pay capital gains tax if I sell an inherited house in Florida?
Capital gains tax applies to gain above your adjusted basis. Florida imposes no state income or capital gains tax because it has no personal income tax; if you live in another state, that state’s income tax may apply to the gain. When selling an inherited house in Florida, compare the amount realized, after qualifying selling expenses, with the adjusted basis, which usually starts at the value at death and increases with improvements you make. If you sell soon after death for about the date-of-death value, the gain is small or nothing. If you hold the house for years while it appreciates, the gain since death is taxable as a long-term capital gain. Selling quickly does not by itself establish zero gain or remove reporting duties.
Hypothetical example. You inherit a house with a properly established $400,000 date-of-death basis, sell it for $430,000 and pay $20,000 of qualifying selling expenses. With no other adjustments, the gain is $10,000: $430,000 minus $20,000 minus $400,000. If the house had sold for $370,000 with the same expenses, the result would be a $50,000 loss. This is an illustration, not a prediction of tax owed: improvements, depreciation, ownership shares, personal use and other rules can change the result (IRS Topic 703).
Living in the inherited home before selling: the home-sale exclusion
The federal home-sale exclusion, up to $250,000 of gain ($500,000 for many married couples), requires that you owned and used the home as your principal residence for at least two of the five years before the sale (IRS Publication 523). A child who inherits a parent’s house does not count the parent’s years, so the exclusion is available only after the heir has lived there long enough. A surviving spouse has special rules that can count the deceased spouse’s ownership and use and, for a sale within two years after the death, allow the higher married-couple limit.
Reporting the sale, losses, rentals and avoiding capital gains
The closing agent issues Form 1099-S, and the seller reports the sale on Form 8949 and Schedule D, or on the estate’s Form 1041 if the estate sells. When siblings inherit together, each reports his or her share. A loss on selling an inherited house that was never used personally by the heir is generally deductible as a capital loss; a loss on a home used as a personal residence is not. If you rent the inherited house, rent is income and depreciation starts from the stepped-up basis of the building. Ways families reduce capital gains tax on inherited property in Florida include selling soon after death, documenting improvements, using the home-sale exclusion after living in the home, an exchange of investment property under the like-kind exchange rules, or a charitable gift; each depends on the facts and should be planned with a tax adviser. A sale through probate, a partition action or a buyout among siblings has the same tax framework; see Florida partition actions.
Documentary stamp tax, the deed and a mortgage
Florida’s documentary stamp tax applies to deeds and is measured by the consideration paid (§ 201.02). A sale of the inherited home is taxed on the price, which the contract usually allocates to the seller. A personal representative’s or trustee’s deed distributing the house to a beneficiary for no consideration is exempt from the tax; only deeds reciting nominal consideration carry the minimum tax. Inheriting a house with a mortgage does not create a tax, and federal law generally prevents a lender from calling a residential loan due solely because the property passed to a relative at the owner’s death; the heir still has to keep the payments current. Debts of the decedent are covered in do you inherit debt in Florida.
Property taxes after inheriting a Florida home
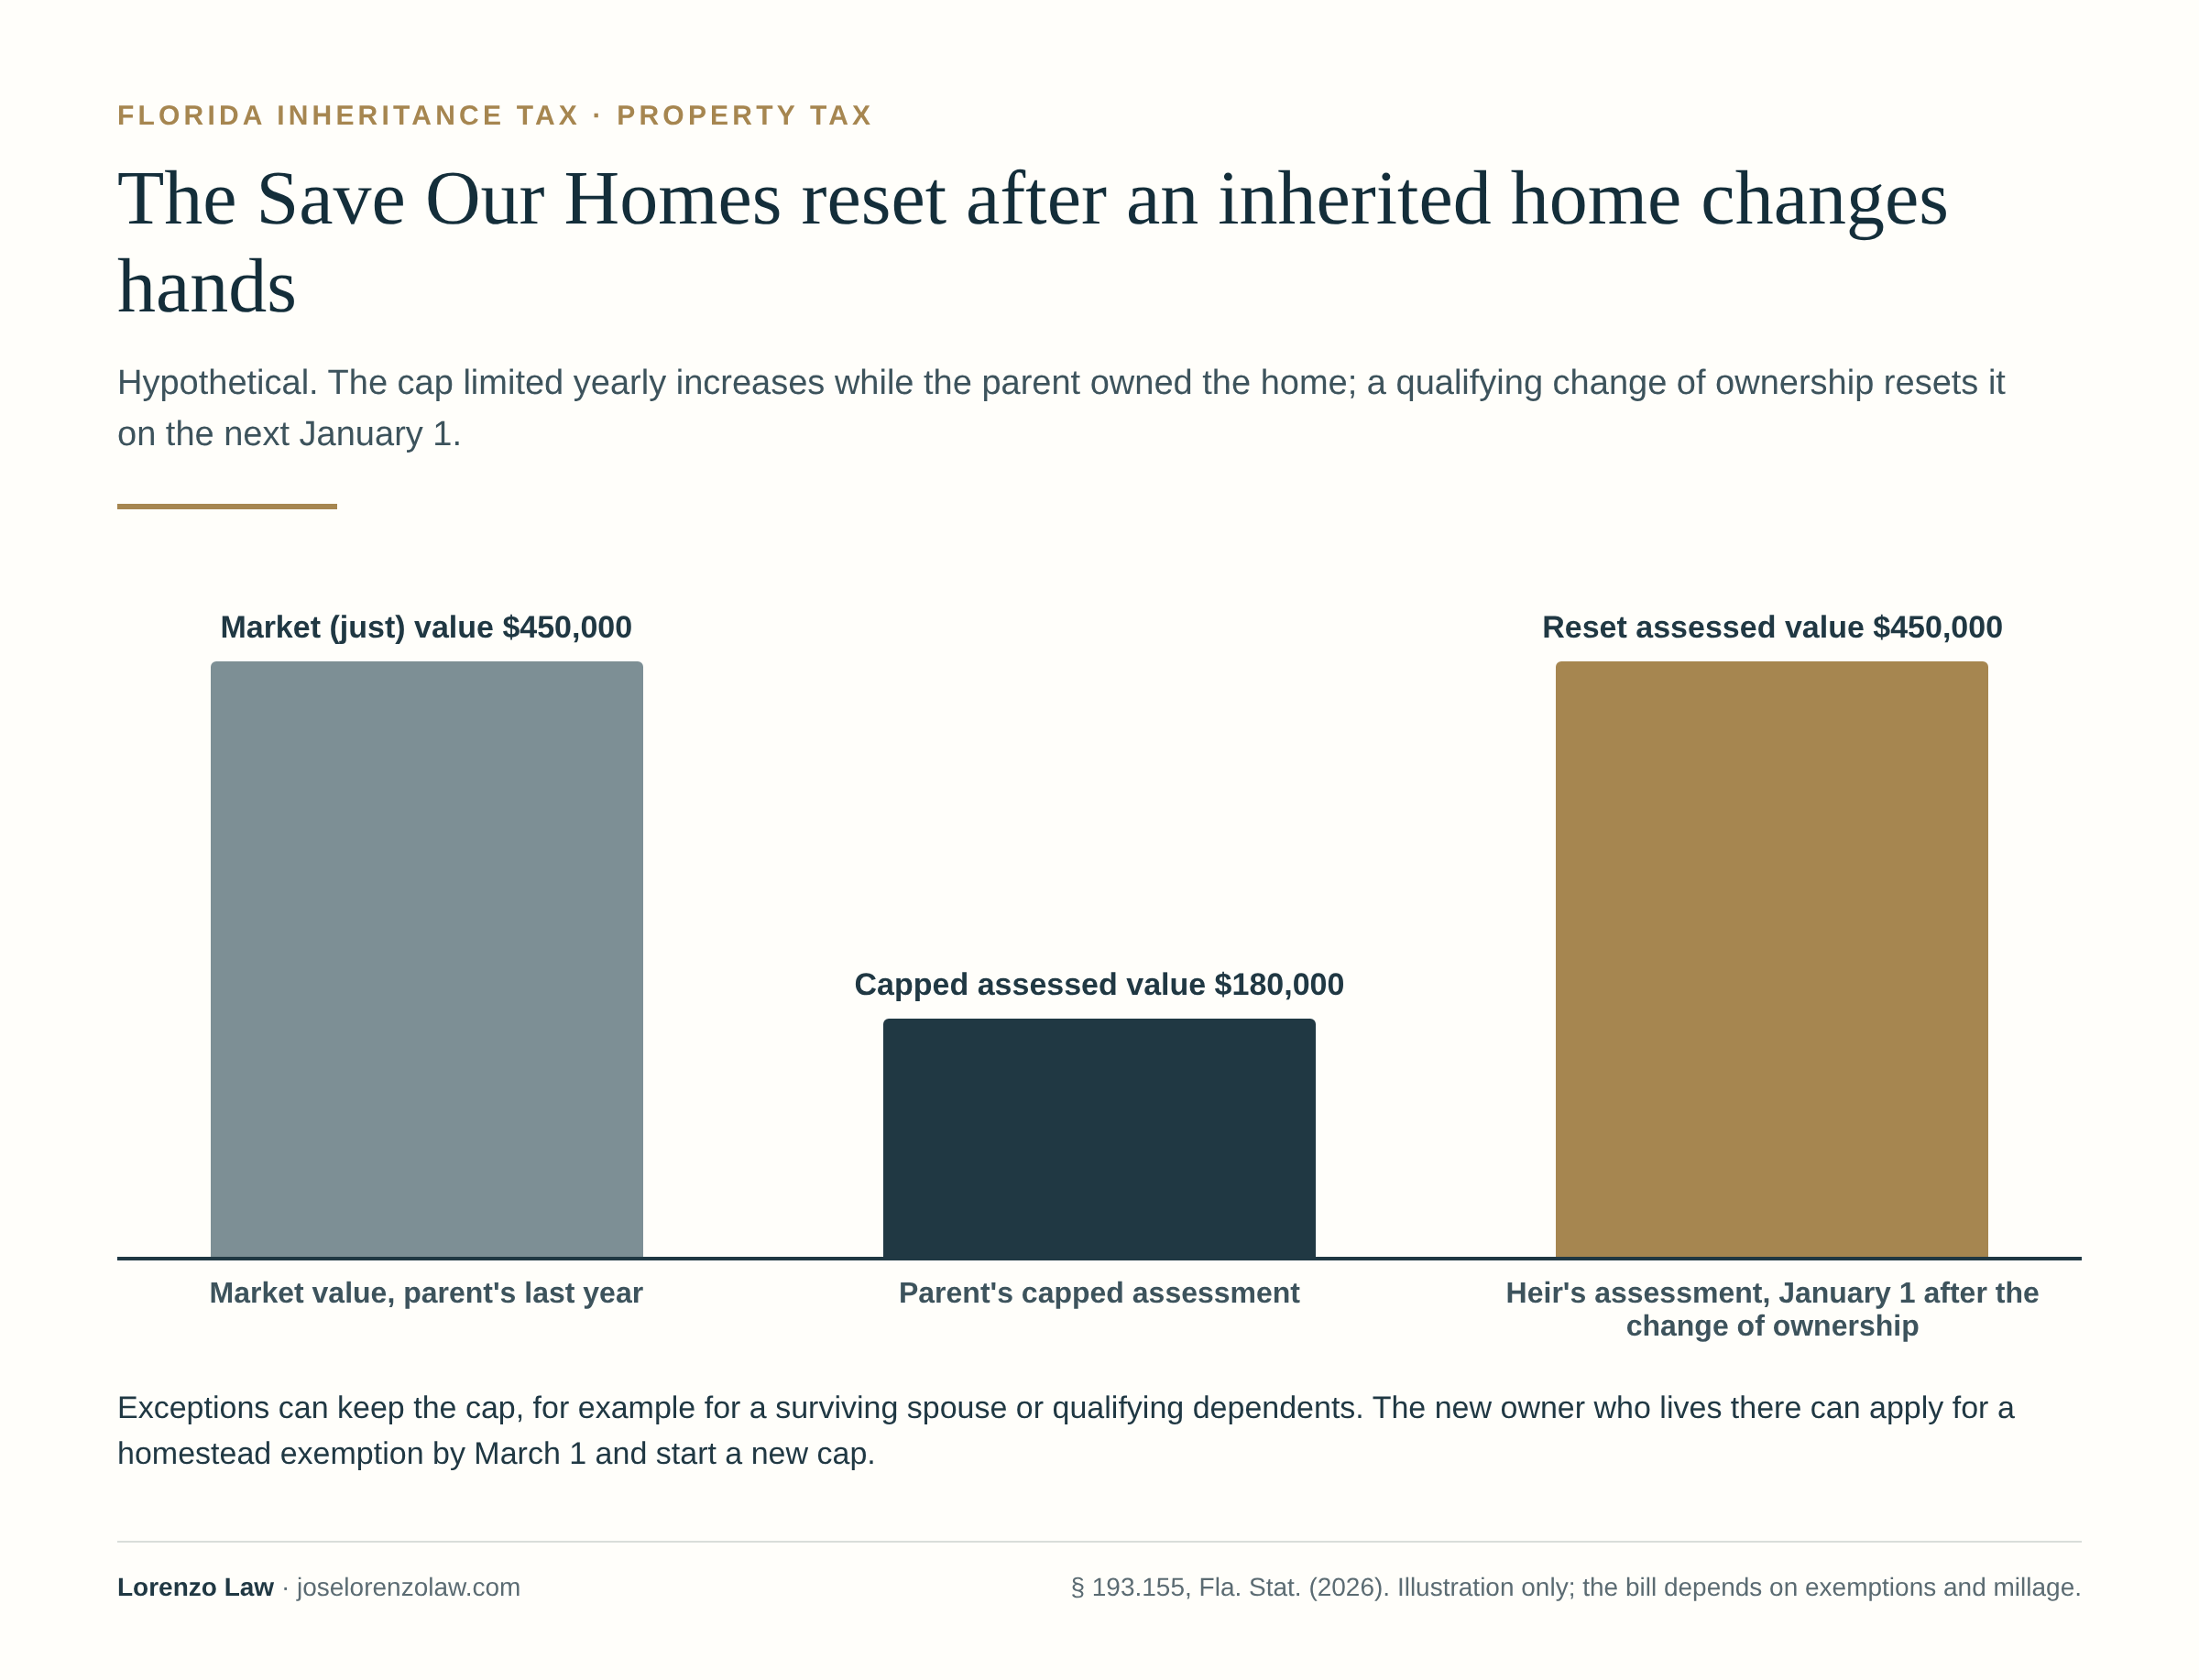
Florida’s Save Our Homes cap limits annual increases in the assessed value of a homestead to 3 percent or the change in the Consumer Price Index, whichever is lower. Under § 193.155(3), a homestead is generally reassessed at just value on January 1 of the year after a change of ownership, unless a statutory exception applies. The owner’s homestead exemption ends with the owner’s death; an heir who makes the home his or her permanent residence must apply in the heir’s own name. This is a property-tax change, not an inheritance tax.
Will my property taxes go up if I inherit my parents’ house in Florida?
Usually yes, if you are an adult child who does not fall within an exception. Does inherited property get reassessed in Florida? A qualifying change of ownership resets the capped assessment to market value on the next January 1, and the first higher bill arrives in November of that year after the TRIM notice in August. The longer your parents owned the home, the larger the gap between the capped value and just value, and the bigger the increase. Moving into the home does not preserve your parents’ accumulated benefit, although it can qualify you for your own homestead exemption and a new cap starting from the reset value.
The exceptions that keep the cap
Section 193.155 lists transfers that are not treated as a change of ownership for this purpose, each with conditions. They include specified transfers between spouses and to a surviving spouse, certain transfers by operation of law to a surviving spouse or minor children, a transfer at death to a permanent resident who is legally or naturally dependent on the owner, certain transfers to a surviving joint owner who already received the exemption, and changes in which the same person remains entitled to the exemption, such as placing the home in the owner’s own revocable trust. Does a surviving spouse lose the Save Our Homes cap? Generally not when the spouse qualifies under these exceptions. A family relationship or a trust label alone is not enough; ask the county property appraiser to review the actual transfer, and keep the deed, death certificate and trust documents ready.
The homestead exemption after death and your own application
Can I keep my parents’ homestead exemption after they die? No; the exemption belonged to the owner who lived there. An heir who owns the home and makes it his or her permanent residence on January 1 can apply for a new homestead exemption, generally by March 1 of that year (§ 196.011). A beneficiary of a revocable trust or a life estate can qualify in some cases. Florida homestead also has protections in probate that are separate from property tax; see Florida homestead probate questions and surviving spouse rights.
The TRIM notice and the deadline to challenge an assessment
Each August the property appraiser mails a notice of proposed property taxes, the TRIM notice. A value adjustment board petition challenging an assessment generally must be filed within 25 days after the TRIM notice is mailed; a petition challenging an exemption denial must be filed within 30 days after the denial notice (§ 194.011). Out-of-state heirs often miss it because the notice goes to the decedent’s address: update the mailing address with the property appraiser as soon as the estate is opened, and request an informal review first if the value looks wrong.
Rental, second home or vacant: the 10 percent non-homestead cap
If the inherited home will be rented, held as a second home or left vacant, it is non-homestead residential property. Its assessment increases are capped at 10 percent a year for levies other than school taxes, and that cap also resets after a change of ownership (§ 193.1554). Amendment 3 on the November 2026 ballot would lower the non-homestead assessment cap from 10 percent to 5 percent (art. VII, § 4(g)) and would also raise the non-school homestead exemption, with a residency requirement for new residents. It is not yet law; it would take effect January 1, 2027, only if at least 60 percent of voters approve it. Property-tax exemptions and caps can change by constitutional amendment or legislation, so confirm the current rules with the county property appraiser.
Two kinds of portability
Federal estate-tax portability transfers a deceased spouse’s unused exclusion (see portability). Florida homestead portability is different: it lets an owner who moves from one Florida homestead to another carry over up to $500,000 of the Save Our Homes difference, if the new homestead is established within three tax years (§ 193.155(8), Form DR-501T). An heir does not inherit a parent’s portability benefit by inheriting the house, although the heir’s own prior homestead may qualify. Can I use portability to keep my parents’ low assessment? No, not the parents’ benefit. For a neighborhood view of the same reset, see homestead and the tax reset.
The estate’s own income taxes: final Form 1040, Form 1041 and Schedule K-1
Florida has no estate income tax, but federal income tax returns can still be required after a death. The decedent’s final Form 1040 covers income from January 1 through the date of death. Income earned afterward by the estate, such as interest, dividends, rent and gains on assets sold during administration, belongs on the estate’s Form 1041 if the filing test is met, and a beneficiary who receives a distribution may receive a Schedule K-1 reporting his or her share (Form 1041 instructions).
Does an estate have to file a tax return in Florida?
Not a Florida return: Florida has no estate tax return for current deaths and no income tax on estates. Federal returns are the question. Under the current instructions, a domestic decedent’s estate generally must file Form 1041 if it has gross income of $600 or more for the tax year or has a beneficiary who is a nonresident alien, and the instructions add a filing requirement for an estate holding a qualified investment in a qualified opportunity fund. Trusts have their own tests. Did the estate have $600 or more of gross income after the date of death (or a nonresident-alien beneficiary)? If so, a Form 1041 is generally required. Separately, the decedent’s final Form 1040 is due on the usual April deadline of the year after death, and a surviving spouse can often file it jointly. Form 706 is the separate estate-tax return discussed in who must file Form 706. Filing taxes for a deceased person with an estate therefore can mean three different returns.
How estate income reaches beneficiaries: distributions and the K-1
An estate deducts the income it distributes, up to its distributable net income, and the beneficiaries report that income from their Schedules K-1; income the estate keeps is taxed to the estate at compressed rates. A cash payment to you is therefore not automatically all taxable income, and distributing sale proceeds does not automatically shift every capital gain to you: gains are often taxed to the estate except in its final year or when the governing instrument or local law allocates them to income. An executor can, by election, treat distributions made within 65 days after the tax year ends as made in that year, and an estate can choose a fiscal year. Is estate income taxable to the beneficiaries, and is a K-1 inheritance taxable? Your share of the estate’s income is; the inheritance itself is not.
Personal representative tax tasks
- Obtain an employer identification number for the estate before opening an estate bank account.
- File IRS Form 56 to notify the IRS of the fiduciary relationship.
- Collect the decedent’s Forms W-2, 1099 and prior returns for the final Form 1040.
- Track income received after death separately for Form 1041.
- Reserve for taxes before final distributions, and coordinate the income allocation, tax reserve and required statements with the preparer.
- Remember that personal representative compensation is taxable income to the personal representative who receives it (§ 733.617).
The broader administration steps are in what to do when someone dies in Florida and closing an estate in Florida.
Affidavit of No Florida Estate Tax Due: Forms DR-312 and DR-313
Beginning July 1, 2023, personal representatives of estates do not have to file Form DR-312, Affidavit of No Florida Estate Tax Due, or Form DR-313, Affidavit of No Florida Estate Tax Due When Federal Return is Required (Florida DOR). Chapter 2023-207, Laws of Florida, effective July 1, 2023, amended § 198.32 to remove the affidavit requirement and the Florida estate-tax lien for estates of people who died after December 31, 2004 (§ 198.32(3)). The companion return-filing relief in § 198.13(4) was already in place.
Do I still need Form DR-312 or DR-313?
Not under the current rules for a death after December 31, 2004. Form DR-312 historically certified that an estate owed no Florida estate tax and was not required to file a federal estate tax return; DR-313 did the same for an estate that was required to file federally but owed no Florida tax. Both were sworn, notarized affidavits recorded in the county’s official records to show that no Florida estate-tax lien encumbered the decedent’s Florida real estate. Older versions of the form, fillable PDFs and templates still circulate online; their existence does not make filing mandatory. The Department of Revenue’s rule applies the change to probate proceedings commenced on or after July 1, 2023, and to proceedings pending on that date in which no order of final discharge had been entered (Fla. Admin. Code r. 12C-3.0015).
What a title company may still ask for
A title insurer or closing agent selling inherited Florida real estate may still have its own underwriting requirements. If a closing agent asks for an affidavit, ask what specific title requirement it is meant to satisfy and have counsel review the requested document before anyone signs it. Do not assume an old form is a mandatory filing, that it clears every lien, or that its statements are accurate for the estate. The Florida change does not remove federal estate-tax liens or other title issues, which the personal representative and the title company address separately.
Older deaths and the old Florida estate tax return
Estates of people who died before January 1, 2005 were subject to Chapter 198 as it then applied, including the Florida estate tax return (Form F-706) when a federal return was required. An unresolved older estate, or a title defect traced to one, needs review under the rules for that date of death. Florida uses the term personal representative for the person who administers an estate; readers may know the role as executor or administrator. The absence of a Florida estate-tax filing does not eliminate probate, the final income tax return or any federal filing.
Does Florida require an inheritance tax waiver?
No. Florida does not issue inheritance tax waivers or estate tax clearance certificates, because it has neither tax. A bank, brokerage or transfer agent that asks for a “Florida inheritance tax waiver” is usually applying a checklist written for states that do require waivers. What it actually needs is proof of death and of your authority to receive or transfer the asset.
Depending on the asset and how it was titled, institutions typically ask for some of these: a certified death certificate; letters of administration issued to the personal representative, or an order of summary administration; the beneficiary’s claim form for a payable-on-death, transfer-on-death or retirement account; a certification of trust from the successor trustee for trust accounts; for securities, an affidavit of domicile and a medallion signature guarantee; and an IRS Form W-9. A Florida inheritance tax waiver form does not exist. If the decedent lived in, or owned an account governed by, a state that does use waivers, such as New Jersey, that state’s waiver can be required for assets connected to it, and the institution may hold the account until it is produced. Can a bank refuse to release an inheritance? It can hold the funds until it receives the documents it is entitled to; it cannot demand a Florida waiver that does not exist. See joint accounts and survivorship, when probate is not necessary and the Florida probate guide.
Inheriting property in another state or from abroad
Living in Florida does not settle another state’s tax. A state’s inheritance or estate tax usually reaches an estate in two ways: when the decedent was domiciled in that state, or when the decedent owned real estate or tangible property located there. Where the beneficiary lives is generally not the deciding factor. A Florida resident who inherits from a parent who lived in Pennsylvania, or who inherits a house in New Jersey, can face that state’s tax even though Florida charges none.
Which states still have an inheritance tax in 2026?
Five: Kentucky, Maryland, Nebraska, New Jersey and Pennsylvania. Iowa repealed its inheritance tax for deaths on or after January 1, 2025. Each state sets its own exemptions and rates, usually by the beneficiary’s relationship: spouses are exempt in all five, children and other lineal descendants are exempt or taxed at low rates in most, and siblings, nieces, nephews, friends and unrelated beneficiaries pay the highest rates. Maryland is the only state with both an inheritance tax and an estate tax. Confirm current rates and exemptions with the state’s revenue department for the year of death.
States with an estate tax
About a dozen states and the District of Columbia impose an estate tax, often with exemptions far below the federal figure: Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont, Washington and the District of Columbia. A Florida resident who still owns real estate in one of them can owe that state’s estate tax on the property located there, even when the federal estate tax does not apply.
Which state has the worst estate tax? There is no single ranking, because the result depends on the estate. Three features make a state’s tax heavier: a low exemption, which reaches estates far below the federal figure; a high top rate; and having both an estate tax and an inheritance tax, as Maryland does. Several states have changed their exemptions or rates in recent years, so check the state’s revenue department for the year of death. The most favorable states for estate taxes are the many, Florida among them, with neither tax.
Can another state tax an inheritance I receive in Florida?
Possibly. Identify where the decedent was domiciled, where each property is located, what kind of property it is, and your relationship to the decedent. State estate taxes and state inheritance taxes have different rules, and real estate is generally taxed where it sits, while bank and investment accounts are generally taxed, if at all, by the decedent’s home state. New Jersey example: its Division of Taxation explains that inheritance-tax treatment depends on the decedent, the assets and the beneficiaries’ relationships, and that where the beneficiaries live is not a factor. A nonresident decedent’s New Jersey real estate may also require nonresident inheritance-tax review, and New Jersey’s estate tax is no longer imposed for deaths on or after January 1, 2018, which shows why estate tax and inheritance tax must be checked separately (New Jersey Division of Taxation). A Florida estate that owns real property in another state usually also needs a probate proceeding there; see ancillary probate.
Inheritances from abroad and Form 3520
For an inheritance from abroad, tax and reporting are separate questions. A U.S. person who receives more than $100,000 in a tax year, in total, in gifts or bequests from a nonresident alien individual or a foreign estate generally must report them on Form 3520 (the $100,000 figure is set by IRS guidance), with aggregation rules for related foreign persons; different and lower thresholds apply to gifts from foreign corporations and partnerships, and distributions from foreign trusts have their own rules (IRS, gifts from foreign persons; Form 3520 instructions). Form 3520 is an information return, and penalties for late filing can be significant even when no tax is due. Receiving inheritance money from overseas is not automatically taxable, but the foreign country may impose its own inheritance tax, foreign accounts you inherit can trigger separate account-reporting forms, and selling inherited foreign property can produce a U.S. capital gain. Ask an international tax adviser about the asset, the payer and the forms. Spanish-speaking readers can start with herencia en Florida para extranjeros y no residentes.
Moving to Florida: when the former state can still tax the estate
Moving to Florida removes state estate and inheritance tax only if Florida becomes your domicile, your true, fixed and permanent home, and only for property that is not located in a taxing state. A former state such as New York, Massachusetts, Connecticut, Maryland or Illinois can argue that a person who spent winters in Florida never gave up domicile there, and it can tax real estate left behind regardless of domicile.
Does moving to Florida avoid a state estate tax?
It can, when the move is real and complete. Evidence of Florida domicile includes a recorded declaration of domicile (§ 222.17), a Florida homestead exemption, a Florida driver’s license, voter registration and vehicle registration, where you file tax returns and receive mail, and where you actually spend your time, keep valuables and see your doctors. A second home kept in the former state, a club membership or a business there can cut the other way. Florida domicile does not protect real estate in another state from that state’s estate or inheritance tax, and an estate with property in two states may need probate in both. See establishing a Florida domicile and Lady Bird deeds for out-of-state owners. Estate tax minimization for a household with ties to Miami and another state is a planning question for counsel in both states, not a form to fill out.
Noncitizen owners of Florida property and noncitizen spouses
Do not apply a $60,000 threshold to every non-U.S. citizen who owns Florida property. Federal estate-tax residence is based on domicile, which can differ from income-tax residence or immigration classification. The decedent’s citizenship and domicile, where each asset is located, how it is owned and any estate-tax treaty must be reviewed together (Form 706-NA instructions, Definitions).
The estate of a person who was neither a U.S. citizen nor domiciled in the United States can face a separate regime for U.S.-situated assets, reported on Form 706-NA, with a much lower filing threshold than the $15 million that applies to citizens and residents (IRS, estate tax for nonresidents). Florida itself taxes nonresidents no more than residents: there is no Florida estate or inheritance tax on anyone. A noncitizen surviving spouse raises a different question, the federal marital deduction, which generally requires a qualified domestic trust for property passing to a spouse who is not a U.S. citizen. Neither question is answered by the beneficiary’s citizenship alone.
See the Florida ancillary administration and noncitizen estate-tax guide for the topics to raise with counsel, including situs, treaties and ancillary probate. Obtain individual advice before retitling property, forming an entity or relying on a treaty; this overview does not recommend an LLC, a foreign corporation or a particular trust.
Probate costs are not a tax, and dying without a will does not create one
Florida does not impose a probate tax or a separate tax because an estate goes through probate. Probate does involve costs: the clerk’s filing charges, which are set by statute and the clerk’s fee schedule (§ 28.2401), personal-representative compensation (§ 733.617), attorney fees, appraisals, publication of the notice to creditors, recording charges and bond premiums where required. They are administration expenses, paid by the estate, and they reduce what remains for distribution. They are not a tax rate on what each heir receives.
Is there a probate tax in Florida?
No. There is no Florida probate tax, so probate taxes in Florida and a Florida probate tax rate do not exist; what people usually mean by them, or by “probate and inheritance tax,” is probate fees, which are costs, not taxes. A will does not itself avoid probate; properly arranged beneficiary designations, survivorship ownership, a Lady Bird deed or a funded revocable trust can keep particular assets out of probate, but that does not automatically exclude them from the federal gross estate. For the actual costs, see how much probate costs in Florida; for which assets go through probate, see what are probate assets.
Dying without a will
Dying without a will does not create a Florida inheritance tax. It changes who receives the property: Florida’s intestacy statute decides the shares, and a surviving spouse does not always inherit everything (§ 732.102). Homestead follows its own constitutional and statutory rules: protected homestead generally passes outside the probate estate, and where the decedent leaves a spouse and descendants it descends to the spouse as a life estate with a vested remainder in the descendants (McKean v. Warburton, 919 So. 2d 341 (Fla. 2005); § 732.401). Does dying without a will change the tax on an inheritance? Not the Florida tax, which is zero either way. The identity of the recipients can still affect federal deductions, retirement-account payout rules and who bears any estate tax, so intestacy is not tax-neutral in every practical respect. Start with the Florida probate guide for administration and inheritance questions.
Does Florida have a gift tax?
No. Florida has no gift tax; Florida has never enacted a gift tax. The federal gift tax applies to gifts of any size, but the annual exclusion lets a person give up to $19,000 per recipient in 2026 without using any of the lifetime exclusion, and gifts above that amount use part of the same unified exclusion that shelters the estate (the estate tax lifetime exemption, $15 million for 2026). A giver who exceeds the annual exclusion files Form 709; gift tax is owed only after the lifetime exclusion is used up (IRS gift tax FAQs).
Can my parents gift me $100,000 without paying gift tax? Usually yes: no tax is due, the recipient owes neither gift tax nor income tax, and the giver files Form 709 reporting the amount above the annual exclusion. Spouses can combine their annual exclusions to give up to $38,000 per recipient in 2026, but making the gift-splitting election generally requires filing a Form 709 to record both spouses’ consent, even if no tax is due. Tuition paid directly to a school and medical bills paid directly to a provider are excluded without limit, and gifts to a spouse who is a U.S. citizen are generally unlimited. Is an early inheritance or a living inheritance taxable? Not to the recipient. Gifting money before death reduces the estate but does not give the recipient a stepped-up basis on property, which is the trade-off explained in gifting a house versus leaving it. Gifts made while the exclusion was higher are not later “clawed back” into estate tax under the federal regulations on that question, although the details of a large gift program belong with the preparer.
Planning: what actually reduces taxes for heirs
Because Florida has no death tax, planning for a Florida family is about four other things: keeping a large estate below the federal tax through deductions, portability and lifetime gifts; keeping assets eligible for a stepped-up basis; managing income tax on retirement accounts; and preserving Florida property-tax benefits where the law allows. None of these is a universal exemption, and none should be chosen only because someone says it will “avoid inheritance tax.”
How do I avoid the death tax in Florida?
There is no Florida death tax to avoid. For the federal estate tax, which reaches only large estates, the main tools are the unlimited marital deduction for a U.S. citizen spouse, portability, the charitable deduction, annual-exclusion and direct tuition or medical gifts, and irrevocable trusts that move future growth out of the estate. For heirs’ income tax, the tools are coordinated beneficiary designations, lifetime Roth conversions in some cases, and naming a charity as the beneficiary of pretax retirement money if charity is part of the plan. For capital gains, holding appreciated property until death preserves the step-up. Which of these fits depends on the size of the estate, the family and the assets; the Florida estate planning guide explains the broader framework.
Does a revocable trust avoid estate tax?
No. A revocable living trust can avoid probate for property properly titled in it, depending on its terms and the circumstances, but the person who can revoke it still owns it for federal estate-tax purposes, so the assets remain in the gross estate. That is also why trust assets generally receive a stepped-up basis at death. Trust funding, estate-tax inclusion and income taxation are distinct issues; see living trusts in Florida.
Irrevocable trusts, life insurance trusts and charitable gifts
For estates near or above the federal exclusion, planners commonly consider irrevocable trusts that remove property and its future growth from the estate, such as a spousal lifetime access trust (SLAT), a grantor retained annuity trust (GRAT), an irrevocable life insurance trust (ILIT) that keeps policy proceeds out of the gross estate, a dynasty trust that uses the generation-skipping transfer tax exemption, and charitable remainder or charitable lead trusts. Each has costs and trade-offs, including the loss of a step-up for property removed from the estate. See Florida irrevocable trusts and dynasty trusts. Using life insurance to pay estate tax, or a trust fund to avoid estate tax, is a planning choice to review with counsel and the tax adviser, not a product to buy. Gifts to charity at death are covered in the guide to charitable bequests in a Florida will.
Disclaiming an inheritance
A beneficiary can refuse an inheritance by a qualified disclaimer, so that the property passes as if the beneficiary had died first. To be a “qualified disclaimer” that avoids gift-tax consequences, federal law requires a written disclaimer delivered within nine months after the death (or after the beneficiary turns 21), before the beneficiary accepts any benefit (IRC § 2518). Florida’s disclaimer statute (chapter 739) sets no deadline of its own. A Florida disclaimer is barred only by a written waiver of the right to disclaim, acceptance of the interest or its benefits, a voluntary assignment or transfer (or encumbrance or pledge) of the interest, a judicial sale of the interest, or the disclaimant’s insolvency when the disclaimer becomes irrevocable (§ 739.402). A disclaimer can place property beyond some creditors, but not an insolvent disclaimant’s creditors and not a federal tax lien. Disclaimers are also used to move property to a spouse or a credit-shelter trust, or to the next generation. A disclaimer is irrevocable, so review it before signing.
Which form or record answers which question
This routing table matches each common form to its purpose and its main limit. It is not a complete filing checklist, and the instructions for the relevant death or tax year control.
| Form or record | Purpose | Important limit |
|---|---|---|
| Form 706 | Federal estate tax return and the portability election | Required-return test and tax due are different; generally due nine months after death |
| Form 4768 | Extension of time to file and, separately, to pay | An automatic filing extension does not extend the time to pay |
| Form 706-NA | Estate tax return for a nonresident noncitizen decedent | Determine estate-tax domicile, U.S. situs and treaty effects first |
| Form 8971 and Schedule A | Basis reporting by covered estates to the IRS and beneficiaries | Exceptions apply; a return filed only to elect portability does not itself require it |
| Final Form 1040 | The decedent’s income through the date of death | Separate from income the estate earns after death |
| Form 1041 and Schedule K-1 | Estate or trust income and each beneficiary’s share | $600 gross income test for estates; distributions carry out income, not principal |
| Form 56 and an EIN | Notice of the fiduciary relationship; the estate’s tax identification number | Obtain before opening the estate account |
| Form 1099-R, Form 8606 and Form 5329 | Retirement distributions, after-tax basis, and a missed-distribution waiver request | Verify pretax, after-tax and Roth amounts; do not assume every dollar is taxable |
| Form 1099-S, Form 8949 and Schedule D | Sale of inherited real estate and the gain or loss | Basis is usually the value at death, supported by an appraisal |
| Form 709 | Federal gift tax return for gifts above the annual exclusion | Filing does not mean tax is due |
| Form 3520 | Reporting large gifts and bequests from foreign persons | An information return; penalties can apply even when no tax is due |
| Forms DR-312 and DR-313 | Historical affidavits of no Florida estate tax due | Not required under the current rules for post-2004 deaths; review any title request |
| Homestead application (DR-501) and portability (DR-501T) | An heir’s own homestead exemption and Florida assessment portability | File with the county property appraiser, generally by March 1 |
| Valuation, deed and closing records | Basis and ownership evidence | The property-tax assessed value is not automatically the federal basis |
Sources: Form 706, Form 1041, Form 8971, Publication 590-B, Form 3520 and the Florida Department of Revenue.
Before you withdraw, sell or distribute: a records checklist
Bring what you have; you need not resolve every question before asking for help. Avoid irreversible withdrawals, sales or transfers based only on the phrase “Florida has no inheritance tax,” because the federal and property-tax questions are still open.
- Record the date of death and the relevant places. Include the decedent’s domicile, citizenship if relevant, where each property is located and where the beneficiaries live for tax purposes.
- Identify each asset and how it passes. Separate probate assets, trust property, joint and payable-on-death accounts, accounts with designated beneficiaries, life insurance and foreign assets.
- Collect the documents. The will, trust and all amendments, deeds, beneficiary designations, recent statements, prior gift-tax returns, and any prior spouse’s Form 706 or portability records.
- Preserve valuation and basis evidence. Date-of-death values, real estate appraisals, retirement-account basis records (Form 8606), improvement receipts and closing statements.
- List the deadlines already running. Form 706 at nine months, a portability decision, required retirement distributions, the March 1 homestead filing and the TRIM petition window, tax notices and any pending closing. Ask the responsible professional to confirm each exact date.
- Separate legal and tax work. Florida probate or planning counsel handles authority, title, distributions, apportionment and the governing documents. A CPA, enrolled agent or other qualified tax professional handles return preparation, income allocation, basis and tax calculations. International or other-state facts may need counsel there too.
More questions about Florida inheritance and estate tax
Does Florida have an inheritance tax?
No. Florida has no inheritance tax on anyone who receives property from a person who died, whatever the amount and whatever the relationship. Is there an inheritance tax in Florida for heirs who live elsewhere? No: Florida is not one of the states with inheritance tax listed in other states. There is no Florida inheritance tax rate, return or waiver. Federal estate tax, income tax on inherited retirement accounts and income after death, capital gains on a later sale, Florida property tax and other states’ taxes are separate questions answered above.
Does Florida have an estate tax?
No, for anyone who died after December 31, 2004. Florida’s estate tax was measured by a federal credit that was phased out, and since July 1, 2023 personal representatives do not file the old Florida affidavits, Forms DR-312 and DR-313. A Florida estate can still owe the federal estate tax if the taxable estate exceeds what the federal exclusion covers, which is $15 million for a 2026 death.
Is there a death tax in Florida?
No. “Death tax” is an informal name for an estate or inheritance tax, and Florida has neither, nor a gift tax. So what is the death tax in Florida? The only death tax that can reach a Florida estate is the federal estate tax, paid by the estate when it is large enough, plus any estate or inheritance tax imposed by another state where the decedent lived or owned real estate.
What is the Florida inheritance tax rate?
Zero. Florida does not tax inheritance or charge inheritance tax at any rate, so there is no rate, bracket or percentage to apply, and no calculator is needed for a Florida inheritance tax. The federal estate tax has a top rate of 40 percent on the taxable estate above what the exclusion covers, and states with inheritance tax set their own rates by relationship.
Is there inheritance tax in Florida for a spouse or children?
No. A surviving spouse, children, grandchildren, siblings and unrelated beneficiaries all owe no Florida inheritance tax. A spouse also generally inherits free of federal estate tax because of the marital deduction, if the spouse is a U.S. citizen. Children and other heirs may still owe income tax on inherited retirement accounts as they withdraw from them.
Do beneficiaries have to pay taxes on an inheritance in Florida?
Not on receiving it. Beneficiaries in Florida pay no state inheritance tax, and an inheritance is not federal taxable income. Beneficiaries do pay income tax on pretax retirement withdrawals, on income such as interest, dividends and rent after the date of death, and capital gains tax applies on any gain when they sell inherited property for more than its basis (generally its value at death). Any federal estate tax is paid by the estate before distribution.
Is life insurance taxable to the beneficiary in Florida?
Generally not. Life insurance proceeds paid because of the insured’s death are generally not taxable income to the beneficiary, and Florida does not tax them. Interest paid on the proceeds is taxable. A policy the decedent owned, or in which the decedent held any incident of ownership at death — or whose proceeds were payable to the estate — is included in the federal gross estate, which matters only if the estate is large enough to owe federal estate tax.
Does an inherited IRA get a step-up in basis?
No. A traditional IRA, 401(k) or other pretax retirement account is income in respect of a decedent, so it keeps its tax character and does not get a stepped-up basis. The beneficiary pays income tax on pretax withdrawals. If the owner made nondeductible contributions, that after-tax basis carries over and comes out tax-free.
What is the federal estate tax exemption for 2026?
$15 million per person for a U.S. citizen or resident who dies in 2026, up from $13.99 million in 2025; that is the current estate tax exemption. A married couple can shelter up to $30 million only by preserving the first spouse’s unused amount, through a portability election or planning at the first death. The figure is indexed for inflation in later years, and the year of death controls which figure applies.
When is Form 706 due, and can the deadline be extended?
Form 706 is generally due nine months after the date of death. Filing Form 4768 by that date obtains an automatic six-month extension of time to file, but not of time to pay; the tax is still due at nine months unless a separate extension to pay or an installment election applies. An estate filing only to elect portability may have the five-year late-election option if it qualifies.
What is the deadline to elect portability late?
Under Revenue Procedure 2022-32, an estate that was not otherwise required to file Form 706 can elect portability by filing a complete return, with the required notation, on or before the fifth anniversary of the death, if every condition is met. Estates that were required to file, or that miss the five-year date, cannot use that simplified method; a private letter ruling may be possible in some cases, but relief is not assured.
Does Florida tax nonresidents who own Florida property?
Not with an estate or inheritance tax: Florida has none for residents or nonresidents. A nonresident still pays Florida property tax on Florida real estate, and a nonresident who was not a U.S. citizen can face the federal estate tax regime for nonresident noncitizens on U.S.-situated property. A nonresident’s Florida real estate usually needs a Florida ancillary probate if it was not titled to avoid one.
Do beneficiaries have to receive basis statements?
Sometimes. An estate that is required to file Form 706 generally must file Form 8971 with the IRS and give each beneficiary a Schedule A statement of the estate-tax value of the property the beneficiary receives, within the deadlines in the instructions. Exceptions apply, and a return filed only to elect portability does not itself trigger the requirement. Every beneficiary still needs reliable basis records, such as appraisals and date-of-death statements.
Is Florida a community property state?
No. Florida is a common-law property state, so ordinary property owned by a married couple does not receive the full double step-up in basis available to community property at the first spouse’s death. Florida does allow married couples to create a community property trust under the Florida Community Property Trust Act, and property acquired as community property in another state can keep that character after a move to Florida.
Does a will avoid probate or estate tax in Florida?
No to both. A will takes effect through probate, and it does not reduce the federal estate tax by itself. Probate can be avoided for particular assets with beneficiary designations, survivorship ownership, a Lady Bird deed or a funded revocable trust, but those assets still count in the federal gross estate. Florida has no estate tax for a will or a trust to avoid.
Who inherits in Florida if there is no will?
Florida’s intestacy statute decides. In general, a surviving spouse receives the entire estate if the decedent left no descendants, or if all of the decedent’s descendants are also the spouse’s and the spouse has no other descendants; otherwise the spouse receives one-half and the descendants share the other half. Homestead follows separate rules. Dying without a will creates no Florida inheritance tax. The Florida probate guide covers the shares in detail.
Do I need a lawyer or a CPA for estate tax questions in Florida?
Often both, for different parts of the work. A Florida probate or estate planning attorney handles authority to act, title, distributions, homestead, apportionment of taxes among beneficiaries and the governing documents. A CPA, enrolled agent or other qualified tax professional prepares Form 706, Form 1041 and the final Form 1040 and calculates basis and income tax. Bring both the documents and the deadlines to the first meeting.
Discuss the Florida legal questions with Lorenzo Law
Jose M. Lorenzo, Jr. is Lorenzo Law’s sole attorney (Florida Bar No. 107002). Clients work directly with Jose: the attorney you speak with at the first call is the attorney who handles any matter the firm accepts.
If you need help with Florida probate administration, estate planning, title to an inherited home, homestead, distributions to beneficiaries, or who bears an estate tax under a will or trust, request an initial consultation and mention any approaching deadline, such as a nine-month Form 706 date, a pending closing or a March 1 homestead filing. Tax-return preparation and tax calculations should be handled with a CPA, enrolled agent or other qualified tax professional; the scope of any legal engagement is agreed separately. Families looking for a Florida inheritance lawyer can start with the same consultation.
Consultations are available statewide in English and Spanish, by phone or video. The principal office is in Kissimmee, Florida, with by-appointment meeting locations in Coral Gables and Fort Lauderdale. Representation depends on conflict review, acceptance and a written engagement; an inquiry alone does not create an attorney-client relationship.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing.
Request a free initial consultationCall (305) 224-6811
¿Prefiere español? Jose M. Lorenzo, Jr. atiende consultas en español sobre herencias en Florida, el impuesto sobre herencias (Florida no tiene) y los impuestos federales que pueden aplicar. Lea también herencia en Florida para extranjeros y no residentes.
Explore estate planning for coordinating a complete plan, probate administration for handling an estate after death, and a Florida estate planning attorney for planning around the federal estate tax.
This page provides general information about Florida law and federal tax rules as they apply to Florida estates, not tax or legal advice about a particular inheritance. Figures and rules were checked against the sources listed below for deaths in 2026 and can change. Reading this page or requesting a consultation does not create an attorney-client relationship.
Sources and authorities cited
Statutes cited are the 2026 Florida Statutes unless noted. Federal figures are for the year stated. The text of the law and the current IRS instructions control over any summary on this page.
Statutes and official sources 46 entries
Talk to a Florida probate attorney
Briefly describe your matter and mention any upcoming deadline. Jose Lorenzo responds within 24 to 48 hours. Submitting this form does not create an attorney-client relationship.

