Beneficiary Designations in Florida: What They Override, and What They Don’t
Does a beneficiary designation override a will in Florida? Generally, yes: a valid beneficiary designation usually controls the account or policy it covers, even when your Florida will names someone else. The answer still depends on the asset, the form that actually took effect and the law that governs it, and a spouse’s rights, a divorce, a beneficiary who died first or a form the institution never accepted can change the result.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing. Consultations are available statewide in English and Spanish, by phone or video.
Request a free initial consultationCall (305) 224-6811
Go straight to: Will vs. designation · Florida rules · Filling out the form · Review worksheet
By situation: planning ahead, start with which document controls and the worksheet; after a death, start with records and claims and challenges; after a divorce, start with the divorce rules.
All guide sections 18 sections
Short answer. In Florida, a valid beneficiary designation generally overrides a will for the asset it covers, because the account agreement, policy, plan or statute transfers that asset directly at death and the will governs only property that passes through the probate estate. Updating the will does not update the beneficiary form. The designation may not control if it was never effective, if no named beneficiary survives, if a divorce, a spouse’s protected rights, federal law, a court order or the slayer statute applies, or if the asset is real estate or another kind of property that does not use an account-style beneficiary form.
| What a designation covers | Only the account, policy or plan it is attached to: for example, a payable on death (POD) bank account, a transfer on death (TOD) brokerage account, life insurance, an IRA, a 401(k) or an annuity. Which document controls |
|---|---|
| What the will controls | Probate property: assets in the decedent’s sole name with no surviving co-owner, no effective beneficiary and no trust ownership, plus anything payable to the estate, subject to special rules such as protected homestead. A will cannot change a beneficiary form. Will vs. designation |
| When the form may not control | The change was never accepted; every named beneficiary died first; a divorce voided the designation (§ 732.703); spouse protections, federal plan rules, a court order or the slayer statute apply. Florida rules |
| Your home | A bank or brokerage beneficiary form does not transfer a house. Florida does not have a general transfer on death deed statute; owners often consider an enhanced life estate (Lady Bird) deed, subject to homestead rules. Real estate |
| Creditors | Avoiding probate is not the same as creditor protection. Protection depends on the specific exemption and whose creditor is asking. Creditors |
| Who can change it | The owner, through the institution’s own process. An agent under a power of attorney needs specific authority; a guardian generally needs court approval. Nobody can update it after the owner dies. Who can change it |
| After a death | The institution pays under its own records and the governing contract and law, not under a copy of the will. Request its claim requirements and current designation record. After a death |
| Consultation | Principal office in Kissimmee; Coral Gables and Fort Lauderdale by appointment; statewide by phone and video, in English and Spanish. |
Does a beneficiary designation override a will in Florida?
Usually, yes, for the particular asset that has a valid, effective designation. Florida law and the institution’s contract treat the designation as its own transfer mechanism at death, so the beneficiary form generally takes precedence over the will for that asset. The will governs the probate estate. A newer will does not supersede, trump or update the form.
A will ordinarily directs the distribution of probate property. A beneficiary designation supplies a separate transfer mechanism under an account agreement, insurance policy, retirement plan or applicable statute. The institution pays under its own records and the governing contract and law; the will is not the instrument that directs that payment. Updating the will generally does not update that mechanism, and the will cannot rewrite it.
For example, suppose a life insurance policy validly names one adult child, while a later will leaves the probate estate equally to two children. Assuming no controlling spouse, divorce, validity or other legal issue, the policy generally pays its designated beneficiary. The will’s equal division does not automatically divide the insurance proceeds. The same logic applies when people ask whether a beneficiary on a bank account overrides a will, or whether a 401(k), IRA, pension, annuity, brokerage or investment account beneficiary overrides a will, or whether being a beneficiary overrides a will: the account’s own designation is the starting point.
Florida’s POD account statute and TOD securities law illustrate why the asset matters. Section 655.82 addresses deposit accounts, including surviving owners and beneficiaries. Section 711.509 treats transfers through securities registration in beneficiary form as contractual and nontestamentary. An insurance policy or retirement plan requires its own analysis.
What a will still does when you have beneficiary designations
In the beneficiary designation vs. will comparison, the will is still essential. It can address probate property, nominate a personal representative and a contingent (successor) executor, express a guardian preference for minor children and provide trusts or backup provisions. It also becomes important if a designated asset ends up payable to the estate. Nor does every asset without a beneficiary form necessarily enter probate: valid survivorship ownership and property already held in trust can supply other transfer routes.
National articles often describe the rule in general terms, sometimes using the Uniform Probate Code’s language about nonprobate transfers. Consumer resources from the Consumer Financial Protection Bureau (CFPB), FINRA, AARP, Nolo and state bar associations can provide general background, but the rule for a particular Florida asset needs a separate check. Florida applies its own statutes to deposit accounts, securities, divorce, homestead, minors and spousal rights, and federal law governs many employer plans. That is why a Florida answer starts with the specific asset and the Florida or federal rule that governs it.
The same is true when there is no will, the situation people describe when they ask whether a beneficiary designation outweighs intestacy. A valid beneficiary designation generally controls its covered asset even when there is no will; being an intestate heir does not, by itself, displace that designation. If no effective designation applies, check the asset’s default rules. Protected homestead has separate descent rules. The residuary estate, meaning the probate property left after specific gifts, debts and expenses, does not include an asset that passes by beneficiary designation.
Four questions that should be kept separate
Ownership, entitlement at death, probate and creditor treatment are four different questions. A beneficiary designation answers only part of the second one.
| Question | What to check | What the answer does not establish |
|---|---|---|
| Who owns the asset now? | Account title, deed, trust ownership and co-owner rights | Naming a future beneficiary does not necessarily make that person a current owner |
| Who is entitled to receive it at death? | Effective designation, surviving beneficiaries, contract defaults and controlling law | The person named in the will does not automatically receive every asset |
| Does it pass through probate? | Whether a valid transfer mechanism operates outside the estate | Avoiding probate does not settle tax, creditor or spousal rights |
| Is it protected from a particular claim? | The specific exemption, whose debt is involved, the recipient and applicable jurisdiction | “Nonprobate” is not a universal creditor exemption |
For the broader inventory of property that does and does not require probate, see Florida probate and non-probate assets.
Florida beneficiary rules at a glance
These are the Florida beneficiary laws that most often change what a beneficiary form appears to say. Each row names the statute so the rule can be read in full.
| Subject | Florida rule, in summary | Where to read more |
|---|---|---|
| POD bank accounts | A POD beneficiary has no right to the deposit while an account party is alive; surviving account parties take before POD beneficiaries (§ 655.82). | Joint owner vs. POD |
| TOD securities | Registration in beneficiary form is contractual and nontestamentary; institutions may set terms for descendant substitution (§§ 711.507, 711.509, 711.51). | Beneficiary died first |
| Divorce | A qualifying designation of a former spouse made before the divorce is generally void for covered assets of a Florida resident, with significant exceptions (§ 732.703). | Divorce |
| Elective share | The surviving spouse of a Florida domiciliary may elect 30 percent of an elective estate that includes many designated assets (§§ 732.201, 732.2035, 732.2065). | Spouse rights |
| Homestead | Devise of homestead is restricted when a spouse or minor child survives (§ 732.4015; Fla. Const. art. X, § 4(c)). | Real estate |
| Minors | Natural guardians have specified authority without court appointment when aggregate amounts do not exceed $15,000 (§ 744.301(2)); FUTMA allows a nominated custodian (§ 710.104). | Minors and trusts |
| Powers of attorney | An agent may create or change a beneficiary designation only with specific authority in the power of attorney (§ 709.2202). | Agents |
| Florida Retirement System | FRS plans use their own beneficiary forms under Chapter 121; if no beneficiary is named, Florida law determines who receives the benefit. | FRS |
| Slayer statute | A person who unlawfully and intentionally kills the decedent can be disqualified, including from specified contractual and survivorship arrangements (§ 732.802). | Challenges |
| Digital assets | Directions for disclosure of digital assets follow a statutory order, starting with a qualifying online tool (§ 740.003). Disclosure is not ownership. | Digital accounts |
Summaries only. The statutes contain conditions and exceptions not repeated here.
Which document controls each kind of asset?
Start with the asset, not with a contest between documents. Each kind of account or policy has its own controlling document, and the comparison below shows which records to request. POD bank accounts and TOD securities start with the institution’s records; life insurance starts with the policy and effective designation; retirement plans require their own plan and beneficiary records; trust-owned property requires the trust and ownership records; probate property is administered under a valid will or intestacy, subject to applicable rights and claims.
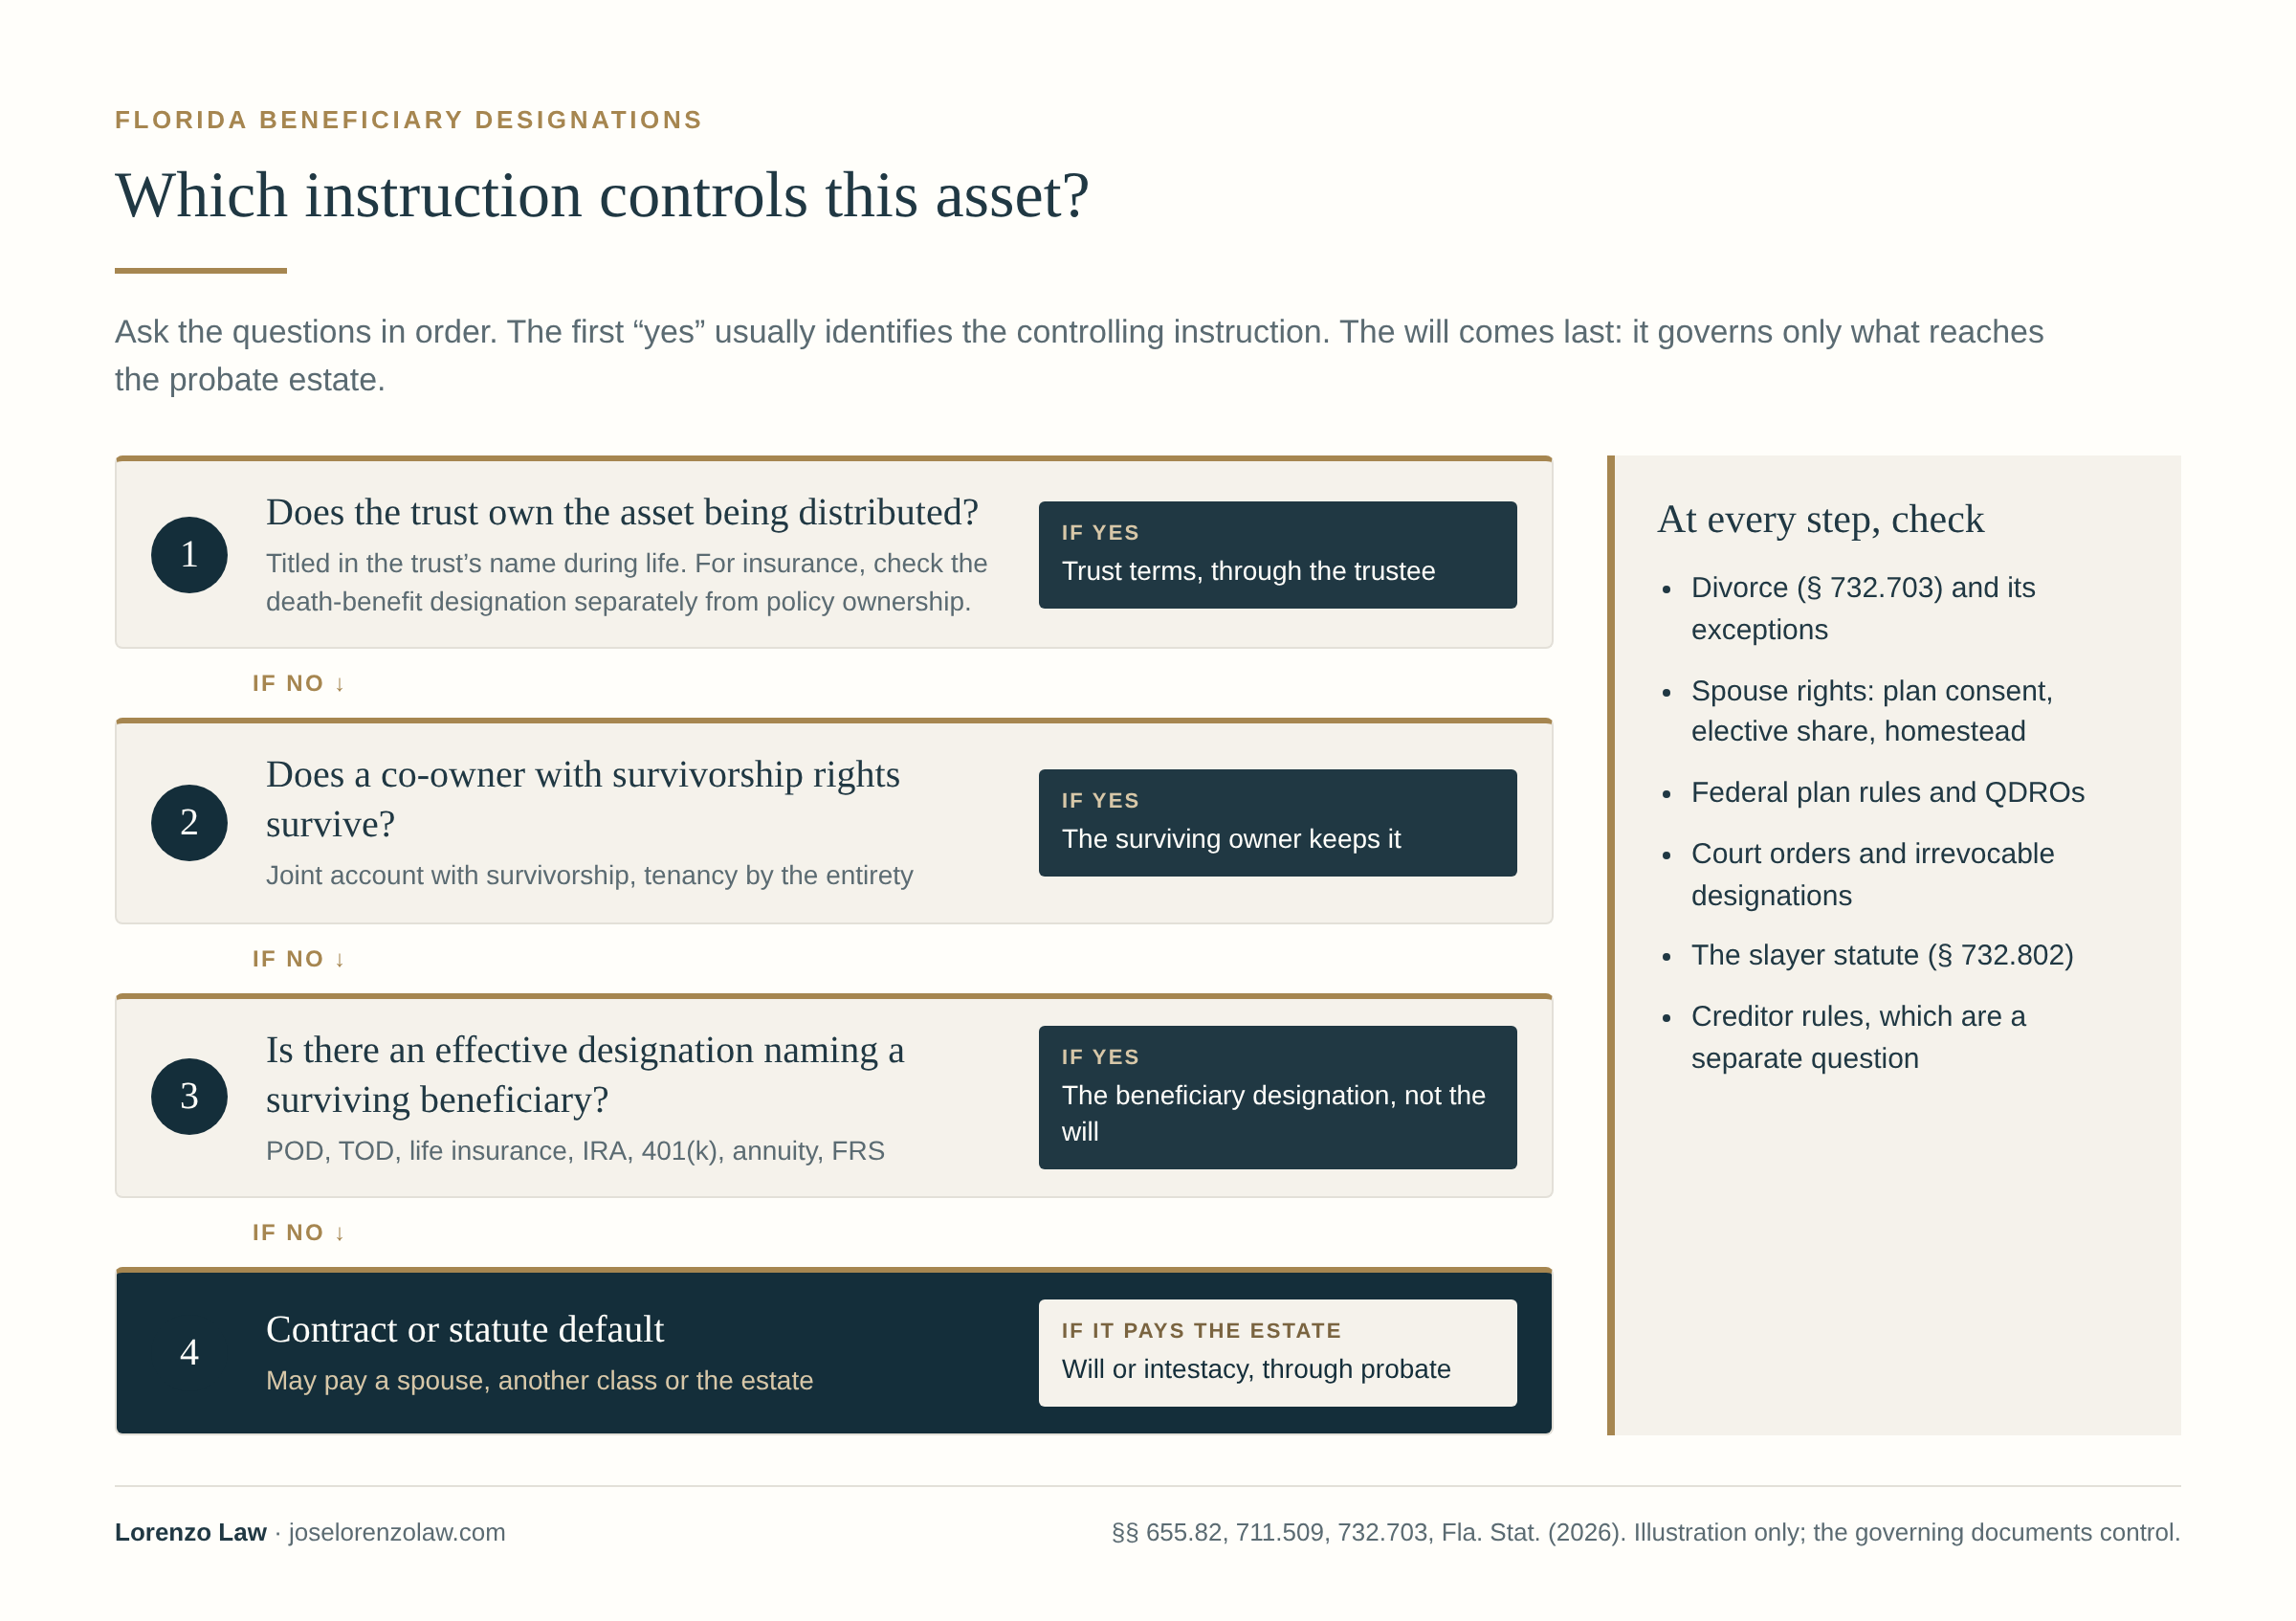
See the chart “Which instruction controls this asset?” (opens the full-size image; the details are also in the text).
Asset-by-asset comparison
Use this comparison to identify the records to request. It summarizes common arrangements; it does not replace the actual contract or title review.
| Asset or arrangement | Starting point for who receives it | Important qualification |
|---|---|---|
| Life insurance | Policy, effective beneficiary designation and applicable law | Employer-provided coverage may raise federal-law issues; an estate designation changes the route |
| Group life insurance through work (basic life or group term life) | The employer plan, the group policy and the designation filed through the employer or insurer | Often governed by federal ERISA rules; coverage can end or convert when employment ends |
| IRA (traditional or Roth); the IRA beneficiary form | Custodial agreement and effective designation | Do not import every employer-plan spouse rule; Florida family rights and contract defaults still need review |
| 401(k), 403(b) or other employer retirement plan | Plan documents, designation, applicable federal or other governing law | Spousal benefits, consent and a qualified domestic relations order may matter |
| Florida Retirement System (FRS) | FRS beneficiary form for the Pension Plan or Investment Plan and Chapter 121 | If no beneficiary is named, Florida law determines the beneficiary; see FRS |
| Federal employee plans: Federal Employees’ Group Life Insurance (FEGLI), the Thrift Savings Plan (TSP), FERS and the Civil Service Retirement System (CSRS) | The program’s own designation form (for example SF 2823 for FEGLI, or the Thrift Savings Plan’s current beneficiary designation process) and federal law. For CSRS and FERS, the current SF 3102 designates beneficiaries of a payable lump-sum death benefit; survivor-annuity rights and elections are separate. Confirm the current form and filing instructions with OPM or the employing agency. An older designation is not invalid merely because OPM updated the form; confirm that it remains effective under the applicable program rules. | A will or a Florida-only form does not change them; the program’s rules govern |
| Annuity | Annuity contract, owner and annuitant roles, and designation | Payment choices and spousal continuation options vary by contract |
| Florida POD deposit account | Account agreement and § 655.82 | Surviving account owners come before POD beneficiaries; no surviving beneficiary can mean payment to the last owner’s estate |
| Checking, savings or CD account with a POD or in trust for (ITF) designation | The bank’s POD or ITF record for that account and § 655.82 | Joint owners still take first; adding POD to a bank account requires the bank’s own form |
| Securities registered TOD (a TOD brokerage or investment account) | Registration, the institution’s terms and Chapter 711 | Surviving owners, substitute beneficiaries and accepted descendant provisions matter |
| Individual stocks held with a transfer agent | TOD registration of the shares, made on the transfer agent’s or broker’s stock transfer on death form, and Chapter 711 | A single or individual TOD account and a joint (JTWROS) account with TOD both pass to the TOD beneficiary only after the last owner dies |
| 529 plan or Florida Prepaid plan | Plan agreement, account owner, successor owner and student beneficiary | The student “beneficiary” and the successor owner perform different roles |
| HSA, U.S. savings bonds and other special accounts | The product’s own designation or registration rules | Tax and transfer rules differ; review each one separately |
| Jointly owned property | Ownership instrument and governing survivorship rules | A co-owner is different from a beneficiary; not every form of joint ownership has survivorship |
| Property already held in a trust | Valid trust ownership and trust terms | Signing a trust without coordinating the asset does not necessarily place the asset under those terms |
| Real estate, vehicles and other titled property | The deed or title and Florida law | An account beneficiary form does not transfer them; see real estate and vehicles |
| Solely owned probate property | Valid will, or intestacy where no effective will provision applies | Administration, claims and protected family rights may affect distribution |
Other arrangements, such as business interests or digital accounts, also need separate review. A 529 plan’s education beneficiary and successor account owner perform different roles; a generic “name a beneficiary” instruction is not enough for every product.
Group life insurance through work. Basic life and group term life insurance from an employer is usually designated through the employer’s benefits portal or the insurer’s group form, not through a personal policy file. The group insurance beneficiary designation on file with the plan controls, not the will, and employer group life insurance is often governed by federal ERISA rules. Federal employees use the FEGLI form. Recheck the group term life insurance beneficiary designation after any job change, because coverage can end or convert when employment ends.
Is a joint owner the same as a POD beneficiary?
No. A POD beneficiary has no right to the deposit merely because of that designation while an account party remains alive. For an account governed by § 655.82, when one of multiple parties dies, the surviving parties take before the POD beneficiaries. Beneficiaries take when the sole party or last surviving party dies, subject to the statute and account arrangement.
Section 655.79 separately addresses survivorship presumptions and married depositors. Read the ownership paperwork before assuming that one spouse can redirect jointly held funds by completing a personal beneficiary form. For more detail, see Florida right of survivorship.
To add a POD beneficiary to a checking, savings or CD account, use the bank’s POD or “in trust for” (ITF) form (an ITF account is treated the same as a POD account, § 655.82(1)(h)2); a CD payable on death follows the same rules as other deposit accounts. A joint account with right of survivorship (JTWROS) can also carry a POD or TOD beneficiary, who takes only after the last joint owner dies. Deposit insurance is a separate question from inheritance: the FDIC treats POD and ITF accounts as informal revocable trust accounts. Since April 1, 2024, trust-account coverage is generally $250,000 per owner for each unique eligible beneficiary, up to $1,250,000 per owner across all of that owner’s trust accounts at the same FDIC-insured bank. Naming the same beneficiary on several accounts at one bank does not multiply coverage, and not every named beneficiary is eligible (see the FDIC’s deposit insurance summary).
| Method | How it transfers | Goes through probate? | Common surprise |
|---|---|---|---|
| Will | Directs probate property after administration | Yes | It does not reach accounts with beneficiaries, survivorship or trust ownership |
| Beneficiary designation (POD, TOD, insurance, retirement) | The institution pays under the effective designation | Usually not, unless it pays the estate | An old form can contradict the will |
| Trust | The trustee distributes property the trust owns or receives | Not for property the trust already owns | Signing a trust does not move accounts into it |
| Joint ownership with right of survivorship, or tenancy by the entirety | The surviving owner keeps the property by survivorship | Not at the first death | Tenants in common have no automatic survivorship. A deceased individual’s share generally requires estate administration unless a trust, protected homestead rule or another applicable arrangement changes the route. |
Can I put a beneficiary on my house in Florida?
Not with an account beneficiary form. A bank or brokerage beneficiary form does not transfer your house. Florida real estate requires a review of the deed, ownership, homestead status and any trust or other transfer instrument. Florida does not have a general transfer on death deed statute of the kind some other states use, so a “beneficiary deed” or “TOD deed” form found online for another state is not a Florida solution. If you are looking for a beneficiary deed lawyer in Florida, or wondering whether you need a lawyer for a beneficiary deed, the Florida instrument to discuss is usually a Lady Bird deed.
A properly prepared enhanced life estate deed, often called a Lady Bird deed (and sometimes misheard as an “early bird deed”), may be an option in suitable circumstances, but it is a deed with legal consequences, not an account designation. Lorenzo Law prepares Lady Bird deeds for a $675 flat fee that includes supervised signing, recording and the minimum documentary stamp; see Florida Lady Bird deeds and what happens to a Lady Bird deed after death.
People also ask whether they can add a beneficiary to a mortgage. A mortgage is a loan secured by the property, not an ownership document, so it has no beneficiary line for the house. Who receives the home depends on the deed and Florida law; the loan generally remains a lien on the property that whoever takes the home must address. Federal law, the Garn-St Germain Act, bars due-on-sale enforcement on certain at-death transfers to a relative, spouse or children (12 U.S.C. § 1701j-3).
Homestead has separate protections. Section 732.4015 restricts devise when a spouse or minor child survives, while allowing a devise to the spouse when there is no minor child. Certain trust dispositions are included. Do not assume that a trust or other label eliminates the restriction. See Florida homestead and probate.
Florida Retirement System and other public plans
Florida Retirement System members designate beneficiaries through FRS, not through a bank or brokerage form, and the plan’s own rules govern. According to the FRS beneficiary brochure, if you do not name a beneficiary, Florida law will determine your beneficiary. That is the meaning of the “per Florida law” language people see in connection with FRS forms: the statutory order in Chapter 121 decides who receives the benefit, not the member’s will. That order is spouse, then children, then parents, then the estate (§ 121.091(8)(a) for the Pension Plan; § 121.4501(20)(a) for the Investment Plan). For the Pension Plan, naming a beneficiary does not by itself fix what is paid: the member’s elected payout option decides whether any benefit continues after death — one option pays only during the member’s life, while others continue a benefit to a beneficiary or joint annuitant (§ 121.091(6)). The FRS Investment Plan beneficiary form also states that a married member who names someone other than the spouse as primary beneficiary needs the spouse’s signed acknowledgment (§ 121.4501(20)(b)); that acknowledgment is not the same as the spousal consent an ERISA plan requires. State-administered Chapter 121 plans are also listed among the exceptions to Florida’s divorce-revocation statute, so a divorced FRS member should check the FRS record directly.
Federal programs require separate review. FEGLI life insurance and the Thrift Savings Plan have their own beneficiary-designation procedures. Under CSRS and FERS, a designation for a payable lump-sum death benefit is different from an election or entitlement to a survivor annuity. Confirm the program, benefit and required filing with the agency or plan; a will does not substitute for that process. For FEGLI and for the CSRS, FERS and TSP lump-sum death benefits, the order-of-precedence statutes provide that a designation “in a will or other document not so executed and filed has no force or effect” (5 U.S.C. §§ 8705(a), 8424(d), 8342(c); § 8433(e)(1) for the TSP).
Cars, boats and other titled property
A vehicle title is not changed by a bank or brokerage beneficiary form, and a Florida title does not carry an account-style beneficiary line. How a car passes at death depends on how the title is held, including how any co-owners are listed (“or” versus “and,” § 319.22(2)(a)), and on Florida’s title-transfer rules (§ 319.28). A boat with a Florida title follows the separate vessel-title rules in Chapter 328 — co-ownership form under § 328.01(7)(d)2 and transfer at death under § 328.01(7)(c) and § 328.24. A surviving spouse or heirs may be able to transfer a vehicle without full probate in some situations. Florida titles are handled by county tax collector offices for the Florida Department of Highway Safety and Motor Vehicles (FLHSMV, often called the DMV); ask that office which title form applies rather than looking for a Florida DMV beneficiary designation form like the ones banks use. See selling or transferring a car after a death in Florida.
How should a beneficiary designation form be filled out?
To fill out a beneficiary designation form, complete the institution’s current beneficiary designation form or online process, identify each beneficiary precisely, and confirm which shares and backup arrangements that product and the governing law allow. Where the form permits percentage allocations, make each required group total 100 percent. Confirm what happens if a beneficiary dies first, and keep the institution’s written acceptance. A form that is ambiguous or never accepted is a common reason a designation fails.
- Use the current form and process. Each bank, insurer, custodian and plan has its own change form or online process. A beneficiary designation letter, will wording, a blank or “simple beneficiary form” downloaded from the internet, or a form for a different account does not change the designation.
- Adding a beneficiary. To add a beneficiary to life insurance, the policy owner submits the insurer’s change form or uses its online portal; to add one to a bank account, use the bank’s POD form. The earliest a designation can be made is usually when the account or policy is opened.
- Give complete beneficiary information. Life insurance and account forms usually ask for each beneficiary’s full name, relationship, date of birth and contact or tax information, and the beneficiary type: an individual, a trust, an estate or a charity such as a foundation. Give that information to the institution directly, not through a public web form.
- Do not confuse an assignment with a designation. A beneficiary assignment form transfers rights in a policy or its proceeds, for example to a lender or a funeral home, and it can take priority over the beneficiary for the assigned amount.
- Insurable interest. When a life insurance policy is bought, the owner generally must have an insurable interest in the insured, so you cannot simply buy life insurance on anyone. Choosing the beneficiary is a separate step.
- Identify people precisely. Use full legal names and the identifying details the form requests, and update the form after a name change. Avoid nicknames and shared family names that could point to two people.
- Use the allocation method the form permits. Fixed dollar amounts can leave a remainder or fall short if the value changes. Whole percentages that total 100 percent for each level are what many forms require. On a Florida bank POD account, surviving beneficiaries share equally and undivided; that form does not take unequal percentages or the backup elections insurance and retirement forms allow (§ 655.82(3)(b)).
- Be careful with class designations. “All my children” or “my grandchildren” can raise questions about adopted children, stepchildren and children born later. Naming each person, or confirming how the institution reads the class, reduces disputes.
- Name primary and contingent beneficiaries. A primary beneficiary is the first intended recipient. A contingent (secondary) beneficiary is a backup who takes under the form’s stated conditions, often only if every primary beneficiary has died. Some forms allow a third, tertiary level. You can usually name several primary beneficiaries, and the same person generally should not be listed at two levels without a reason.
- Decide what happens if a beneficiary dies first. Choose, if the form allows it, between passing that share to the beneficiary’s descendants (per stirpes) or to the surviving beneficiaries. See the comparison below.
- Identify a trust exactly. If a trust is the beneficiary, use the trust’s name, date and trustee as the institution requires. “My trust” is not enough.
- Collect required signatures. Spousal consent rules differ by plan. Many employer plans, and some other plans such as the FRS Investment Plan, require a spouse’s written consent or acknowledgment when someone else is named.
- Know whether the designation is revocable. Most designations can be changed by the owner. An irrevocable beneficiary designation, sometimes required by a divorce settlement or loan, cannot be changed without that beneficiary’s consent or a court order.
- Keep the confirmation. Ask the institution for written confirmation or a copy of the accepted designation, and store it with your estate planning records.
Beneficiary terms that forms use
Forms do not all use beneficiary labels the same way. Check the form’s instructions before deciding whether an “additional beneficiary” or a “2nd beneficiary” line adds another primary beneficiary or a backup. When people ask about the three types of beneficiaries, they usually mean primary, contingent and tertiary; a particular form may offer fewer levels.
- Primary and additional beneficiaries. You can name a single beneficiary for the whole account, or add a 2nd or additional beneficiary to share it, if the form treats that line as another primary beneficiary.
- Contingent beneficiary. Also called a secondary, alternate or backup beneficiary.
- Tertiary and remote contingent beneficiaries. A remote contingent beneficiary takes only if several earlier beneficiaries cannot.
- Successor beneficiary. Someone who inherits an account, such as an inherited IRA, from a beneficiary who had already inherited it.
- Owner or insured, and beneficiary. In everyday speech, the “benefactor” is the owner or insured and the beneficiary is the person who receives. On a husband’s life policy, naming his wife as primary beneficiary is a designation choice; the relationship alone does not show what the insurer has on file.
Per stirpes vs. per capita on a beneficiary form
“Per stirpes” commonly describes a deceased beneficiary’s descendants taking that beneficiary’s branch share. On many forms, the alternative sends a deceased beneficiary’s share to the surviving named beneficiaries; some forms call that alternative per capita, but institutions define these terms differently, so read the form’s own definition. Writing those words in a will does not automatically add them to an account.
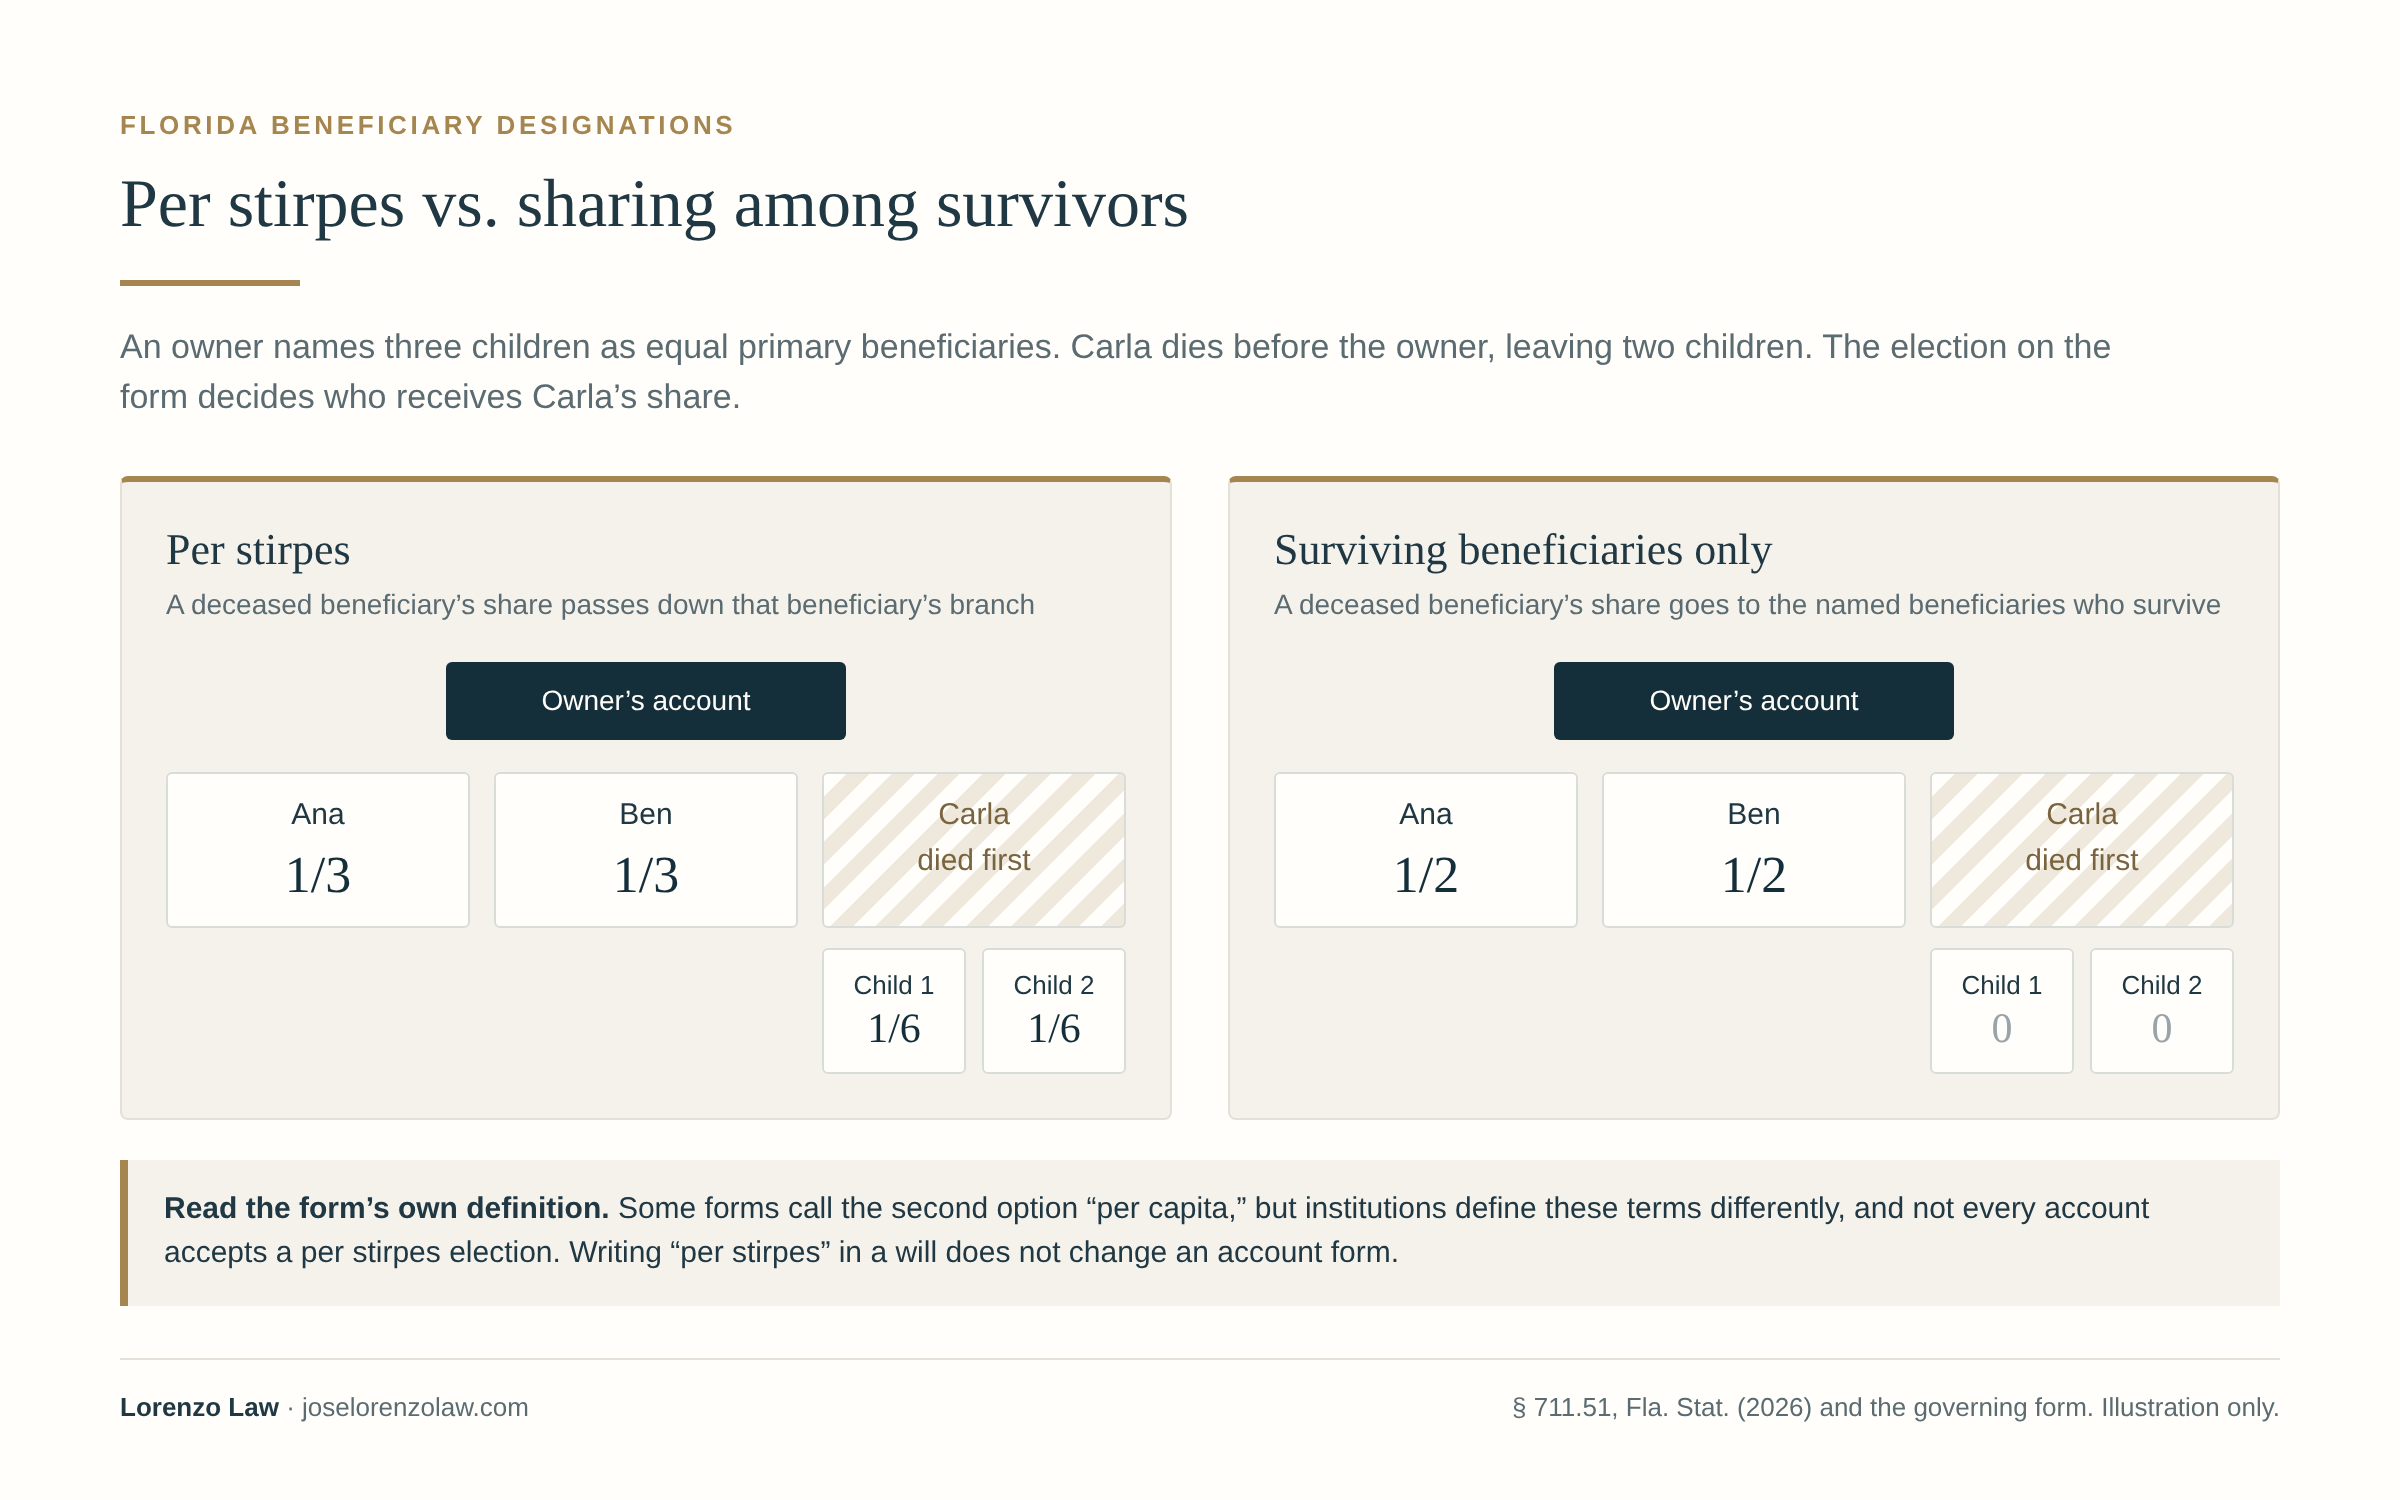
See the chart “Per stirpes vs. sharing among survivors” (opens the full-size image; the details are also in the text).
| Recipient | Per stirpes (share passes down Carla’s branch) | Surviving beneficiaries only |
|---|---|---|
| Ana | 1/3 | 1/2 |
| Ben | 1/3 | 1/2 |
| Carla’s two children | 1/6 each | Nothing |
Section 711.51 permits institutions to establish TOD terms covering contingencies and descendant substitutions. Confirm what the particular institution accepts and how it applies the language. Do not assume that an IRA option is available on a Florida POD deposit account.
What if a beneficiary dies first, or no beneficiary is named?
The next recipient depends on the asset’s rules. Check for a surviving co-owner, other primary beneficiaries, contingent beneficiaries, accepted descendant-substitution language and the institution’s default provisions. There is no universal rule that every empty beneficiary line sends the asset to “next of kin” or automatically to the estate.
Naming a backup does not necessarily mean that backup receives a deceased primary beneficiary’s individual share while other primary beneficiaries survive. On many forms, a contingent beneficiary takes only if all primary beneficiaries have died; the FRS Investment Plan form, for example, says a deceased primary beneficiary’s share is paid equally among the surviving primaries. Ask how the institution handles that exact situation.
| Situation | What needs to be resolved |
|---|---|
| One of several primary beneficiaries dies before the owner | Does the share go to surviving primaries, descendants, a contingent beneficiary or another recipient under the applicable terms? |
| All primary beneficiaries die first | Is an effective contingent or substitute designation available? |
| No effective beneficiary remains on a Florida POD deposit account | § 655.82 provides for the estate of the last surviving account party when no beneficiary survives |
| No beneficiary survives all owners of TOD securities | § 711.507 directs the security to the estate of the sole or last surviving owner; review authorized substitution terms |
| An IRA, life insurance policy, 401(k) or other plan has no effective designation | Read its default order and governing law; a plan may pay a surviving spouse, the estate or another class. Do not substitute a general bank-account rule |
| An FRS member names no beneficiary | Florida law determines the beneficiary under Chapter 121 |
| A beneficiary survives the owner but dies before payment | The beneficiary may already have acquired an interest; distinguish this from dying before the owner |
Florida’s will antilapse statute, § 732.603, is not a universal replacement-beneficiary provision for financial contracts. Likewise, verify any survival-period requirement in the governing instrument. Section 732.601 addresses insufficient evidence of the order of death; it should not be replaced with an assumed universal 120-hour rule. When the owner and beneficiary die close together, the form, the governing law and the evidence of who died first all need review.
If the asset ends up payable to the estate, it generally goes through probate and then passes under the will or, without a will, under Florida’s intestacy rules. See contingent beneficiaries under Florida estate law for the focused backup-beneficiary discussion.
Does divorce remove a former spouse as beneficiary?
Sometimes, but relying on divorce alone is risky. If an ex-spouse is still listed as a beneficiary, Florida’s statute can void (in effect, revoke) a pre-divorce designation of a former spouse, but it has significant exceptions, and federal law can control employer plans. File new beneficiary forms after the divorce, within the limits of the judgment.
For covered assets of a Florida resident at death, § 732.703 generally voids a qualifying designation made before dissolution or invalidation of the marriage in favor of the former spouse. The interest passes as if the former spouse died first. The statute contains significant exceptions and separate protections for paying institutions.
The exceptions include controlling federal law, qualifying post-divorce instruments expressly benefiting the former spouse, specified divorce-order obligations or restrictions, irrevocable designations, assets governed by a will or trust under § 732.507(2) or § 736.1105, instruments governed by another state’s law, survivorship co-ownership, remarriage to the same person and state-administered Chapter 121 retirement plans. Each exception has its own conditions; a divorce order requiring coverage, for example, requires attention to the statute’s other-assets qualification.
For ERISA-covered benefits, federal law can preempt state automatic-revocation law. In Egelhoff v. Egelhoff, 532 U.S. 141 (2001), the U.S. Supreme Court rejected application of a state divorce-revocation rule to the covered benefits. In Kennedy v. Plan Administrator for DuPont Savings and Investment Plan, 555 U.S. 285 (2009), the administrator followed the plan documents despite a waiver in a divorce decree. These decisions are not a rule that an ex-spouse always wins every employer-plan dispute. Plan terms, federal survivor rights and qualified domestic relations orders (QDROs) require separate review.
A separation agreement or marital settlement agreement can require a spouse to keep the former spouse, or the children, as life insurance beneficiary. Before changing a designation after divorce, review the judgment, settlement, any support or insurance obligations, plan requirements and any qualified domestic relations order. Submit permitted changes through the institution’s process and retain confirmation. After a death, ask about both entitlement and the proper recipient and method for a claim notice; the institution’s payment protection and a recipient’s ultimate entitlement are not necessarily the same question.
Marriage, a new child, blended families and other life events
Divorce is not the only event that leaves a form out of date. A marriage or remarriage does not by itself rewrite an existing IRA, POD account or life insurance designation, and a child born or adopted after a form was signed is not automatically added unless the form uses a class designation that includes the child. In a blended family, a form naming only a current spouse, or only the children of one marriage, can produce a result the will never intended, and step-children who were not adopted generally inherit only if named. Update beneficiary designations after having a child, and review every designation after a marriage, divorce, birth or adoption, a beneficiary’s death, a move, a new job, a rollover or a significant change in the family’s finances.
For planning that accounts for children from different relationships or partners who are not married, see estate planning for parents and estate planning for unmarried couples.
Can a beneficiary designation bypass a spouse’s rights?
Do not assume so. Employer-plan survivor rules, Florida’s elective share and homestead protections can each apply, even when a form names someone other than the spouse.
Employer-plan survivor benefits and consent. Many employer retirement plans give a surviving spouse protected benefits and require qualifying consent to a different arrangement. The detailed requirements and exceptions depend on the plan and governing law, including 29 U.S.C. § 1055. A private agreement or an ordinary beneficiary form may not satisfy them. Government and other plans can follow different rules.
IRAs. An IRA generally does not carry the same federal spousal-consent regime as an ERISA-covered employer retirement plan. That does not mean an IRA is beyond all spousal claims or court orders. Review the account, the applicable state law and the estate plan before drawing that conclusion.
Florida elective share. A surviving spouse of a Florida domiciliary may have a right to elect 30% of the elective estate. That is not simply 30% of the probate account balance or every insurance death benefit; life insurance generally enters the elective estate only at its net cash surrender value immediately before death. Sections 732.201, 732.2035 and 732.2065 address the right, included property and percentage. Valuation, exclusions, satisfaction, waivers, federal law and timely election also matter.
Ownership and homestead. A spouse’s existing ownership and protected homestead rights are separate from being named as an account beneficiary. See Florida elective share and surviving spouse rights for those subjects. Retirement-specific consent and distribution questions belong in the IRA and 401(k) beneficiary guide.
Does avoiding probate protect the asset from creditors?
Not automatically. First identify whose creditor is asserting the claim: the deceased owner’s, the surviving beneficiary’s or someone else’s. Then identify the exemption or other protection that actually applies. The phrase “beneficiary designation” does not answer either question.
| Asset or arrangement | Relevant distinction |
|---|---|
| Life insurance death proceeds | § 222.13 generally protects qualifying proceeds designated for another beneficiary from creditors of the insured, subject to policy and assignment provisions; it does not by itself establish immunity from every creditor of the beneficiary |
| Insurance cash value and annuity proceeds | § 222.14 addresses specified property, persons and claims; do not treat it as the same rule as life insurance death proceeds |
| Qualifying retirement funds, including certain inherited arrangements such as an inherited IRA | § 222.21 provides substantial Florida protection subject to its requirements and exceptions; federal bankruptcy and other applicable law require separate review |
| POD bank deposits or TOD securities | The transfer method alone does not supply a blanket creditor exemption |
| Revocable trust property | A revocable trust generally does not shield the settlor from the settlor’s own creditors; after-death liability has statutory conditions and exclusions |
| A beneficiary’s interest in a properly structured trust | Spendthrift protection may apply before receipt, but has exceptions and does not make every distribution permanently protected |
Sources: § 222.13, § 222.14, § 222.21, § 736.0505, § 736.0502 and § 736.0503.
Naming the estate can change both administration and protection. For example, § 222.13 provides that life insurance payable to the insured’s estate becomes an estate asset administered through probate. That insurance rule should not be presented as the universal rule for every retirement account or contract. An estate designation may sometimes be deliberate, but it should follow an asset-specific review rather than a guess. For debts after a death more generally, see what happens to debt when someone dies in Florida.
Should a minor child or a trust be the beneficiary?
A minor child (under 18) can be named, but a child cannot manage the money, so the real decision is who will. A Florida Uniform Transfers to Minors Act (FUTMA) custodian or a properly drafted trust usually provides that management; naming the child directly can require a guardianship of the property for larger amounts.
Naming a minor directly
A minor can be named, but receiving and managing the property is a separate issue. Section 744.301(2) gives natural guardians specified authority without appointment, authority or bond when aggregate amounts do not exceed $15,000, subject to the chapter. Above that authority, a guardianship or another legally available arrangement may be needed. Do not assume a parent can simply sign for any amount, or that every larger payment inevitably requires the same court procedure. The same question arises when a minor is named on a 401(k), an IRA or a life insurance policy, when grandchildren are named as life insurance beneficiaries, and when a single parent’s minor children are the natural beneficiaries of a policy.
Naming a FUTMA custodian
The Florida Uniform Transfers to Minors Act, Florida’s version of the uniform act often called UTMA, provides a way to nominate a custodian for certain future transfers, including contractual beneficiary rights. Section 710.104 addresses nomination and substitute custodians. The designation must fit the asset, statutory mechanism and institution’s requirements.
FUTMA is not an indefinitely managed trust. Under § 710.123, custodianships for transfers under §§ 710.105–710.106 end when the minor turns 21, though the transferor may set them to end at 25; for a custodianship created by irrevocable gift or irrevocable inter vivos exercise of a general power of appointment and set to end at 25, the minor can compel full distribution at 21 — a right the transferor may limit only through the written notice and fixed-period mechanism in § 710.123(3). Transfers under §§ 710.107–710.108 end at 18, and the minor’s death also ends the custodianship. The right endpoint depends on how the property was transferred. Discuss who will manage the money, the intended duration and the consequences before selecting it. Do not name an adult personally on the assumption that the adult is legally required to hold the money for the child.
Naming a trust
A properly drafted trust can provide management, backup trustees and instructions for distributions over time. The beneficiary form must identify the intended trust or trustee accurately in a manner the institution accepts. Creating a trust while leaving the account payable directly to a child generally does not place that account under the trust’s distribution terms. A trust named as a contingent beneficiary for minors is a common way to cover the case where a parent and child both need a backup.
Naming a trust as beneficiary at death is also different from retitling an asset into the trust during life. Retirement accounts require particular care: changing ownership and naming a death beneficiary are not interchangeable instructions. Ask about the trust’s terms and applicable retirement-distribution rules before completing a form. Section 733.808 addresses certain death benefits payable to a trustee.
A beneficiary designation can name the trustee of a living (revocable) trust or, if the institution accepts it, a testamentary trust created under a will. Putting life insurance in a trust, by having an irrevocable life insurance trust own the policy, is a different step with tax and control consequences, and setting up a trust for life insurance proceeds should be planned together with the policy and the beneficiaries. See Florida trusts and irrevocable trusts in Florida.
For someone receiving means-tested benefits, such as SSI or Medicaid, an outright inheritance may affect eligibility. A properly designed third-party special needs trust may be appropriate, depending on the benefit program, funding and distributions. See Florida third-party special needs trusts. A general trust or a label on a form does not guarantee benefit eligibility or protection from every creditor or divorce claim.
Who can change a beneficiary designation?
The owner, during life, through the institution’s own process. Others can act only with specific legal authority: an agent under a power of attorney needs authority that specifically covers beneficiary designations, and a guardian of the property generally needs court approval. After the owner dies, the designation can no longer be updated.
- The owner. For most revocable designations, the account owner, policy owner or plan participant may change the beneficiary at any time while competent, subject to spousal-consent rules, an irrevocable designation or a court order such as a divorce judgment.
- Irrevocable beneficiaries. If a beneficiary was designated irrevocably, the owner generally cannot remove that beneficiary without consent.
- A guardian. A guardian of the property generally needs court approval before taking this kind of action for a ward (§ 744.441).
- Executors and personal representatives. A personal representative administers the probate estate. A personal representative cannot override a valid beneficiary designation on an asset that passes outside the estate.
- After death. Family members, the personal representative and the institution cannot rewrite the designation once the owner has died. What remains are claims about the designation’s validity, a beneficiary’s disclaimer or a court proceeding.
Can an agent under a power of attorney change a beneficiary?
Only in limited circumstances. Under Florida law, an agent may create or change a beneficiary designation only with specific beneficiary-designation authority, with the required signature or initials next to that specific grant of authority (§ 709.2202), subject to limited statutory exceptions, such as ordinary deposits to or withdrawals from a survivorship or POD account by an agent already authorized to conduct banking or investment transactions (§ 709.2202(5)). General language granting broad powers is not enough. A change made without that authority, or one made for the agent’s own benefit, can be challenged, and the institution’s change form and its date are key evidence. A power of attorney also ends at the principal’s death (§ 709.2109(1)(a)). See Florida power of attorney and undue influence.
How should beneficiary forms coordinate with a will and trust?
Coordination means the combined result matches the intended plan. It does not require every asset to name the same person or every account to name a trust. The test is what each person actually receives once every form, title, trust and the will are added together.
Suppose a parent wants two children to receive comparable inheritances, with one child’s share managed in trust. A will dividing probate property equally does not necessarily equalize an IRA payable to one child and insurance payable to the other. Values, tax treatment and distribution conditions can differ. Review the complete allocation and the management goal rather than just the percentages on one form.
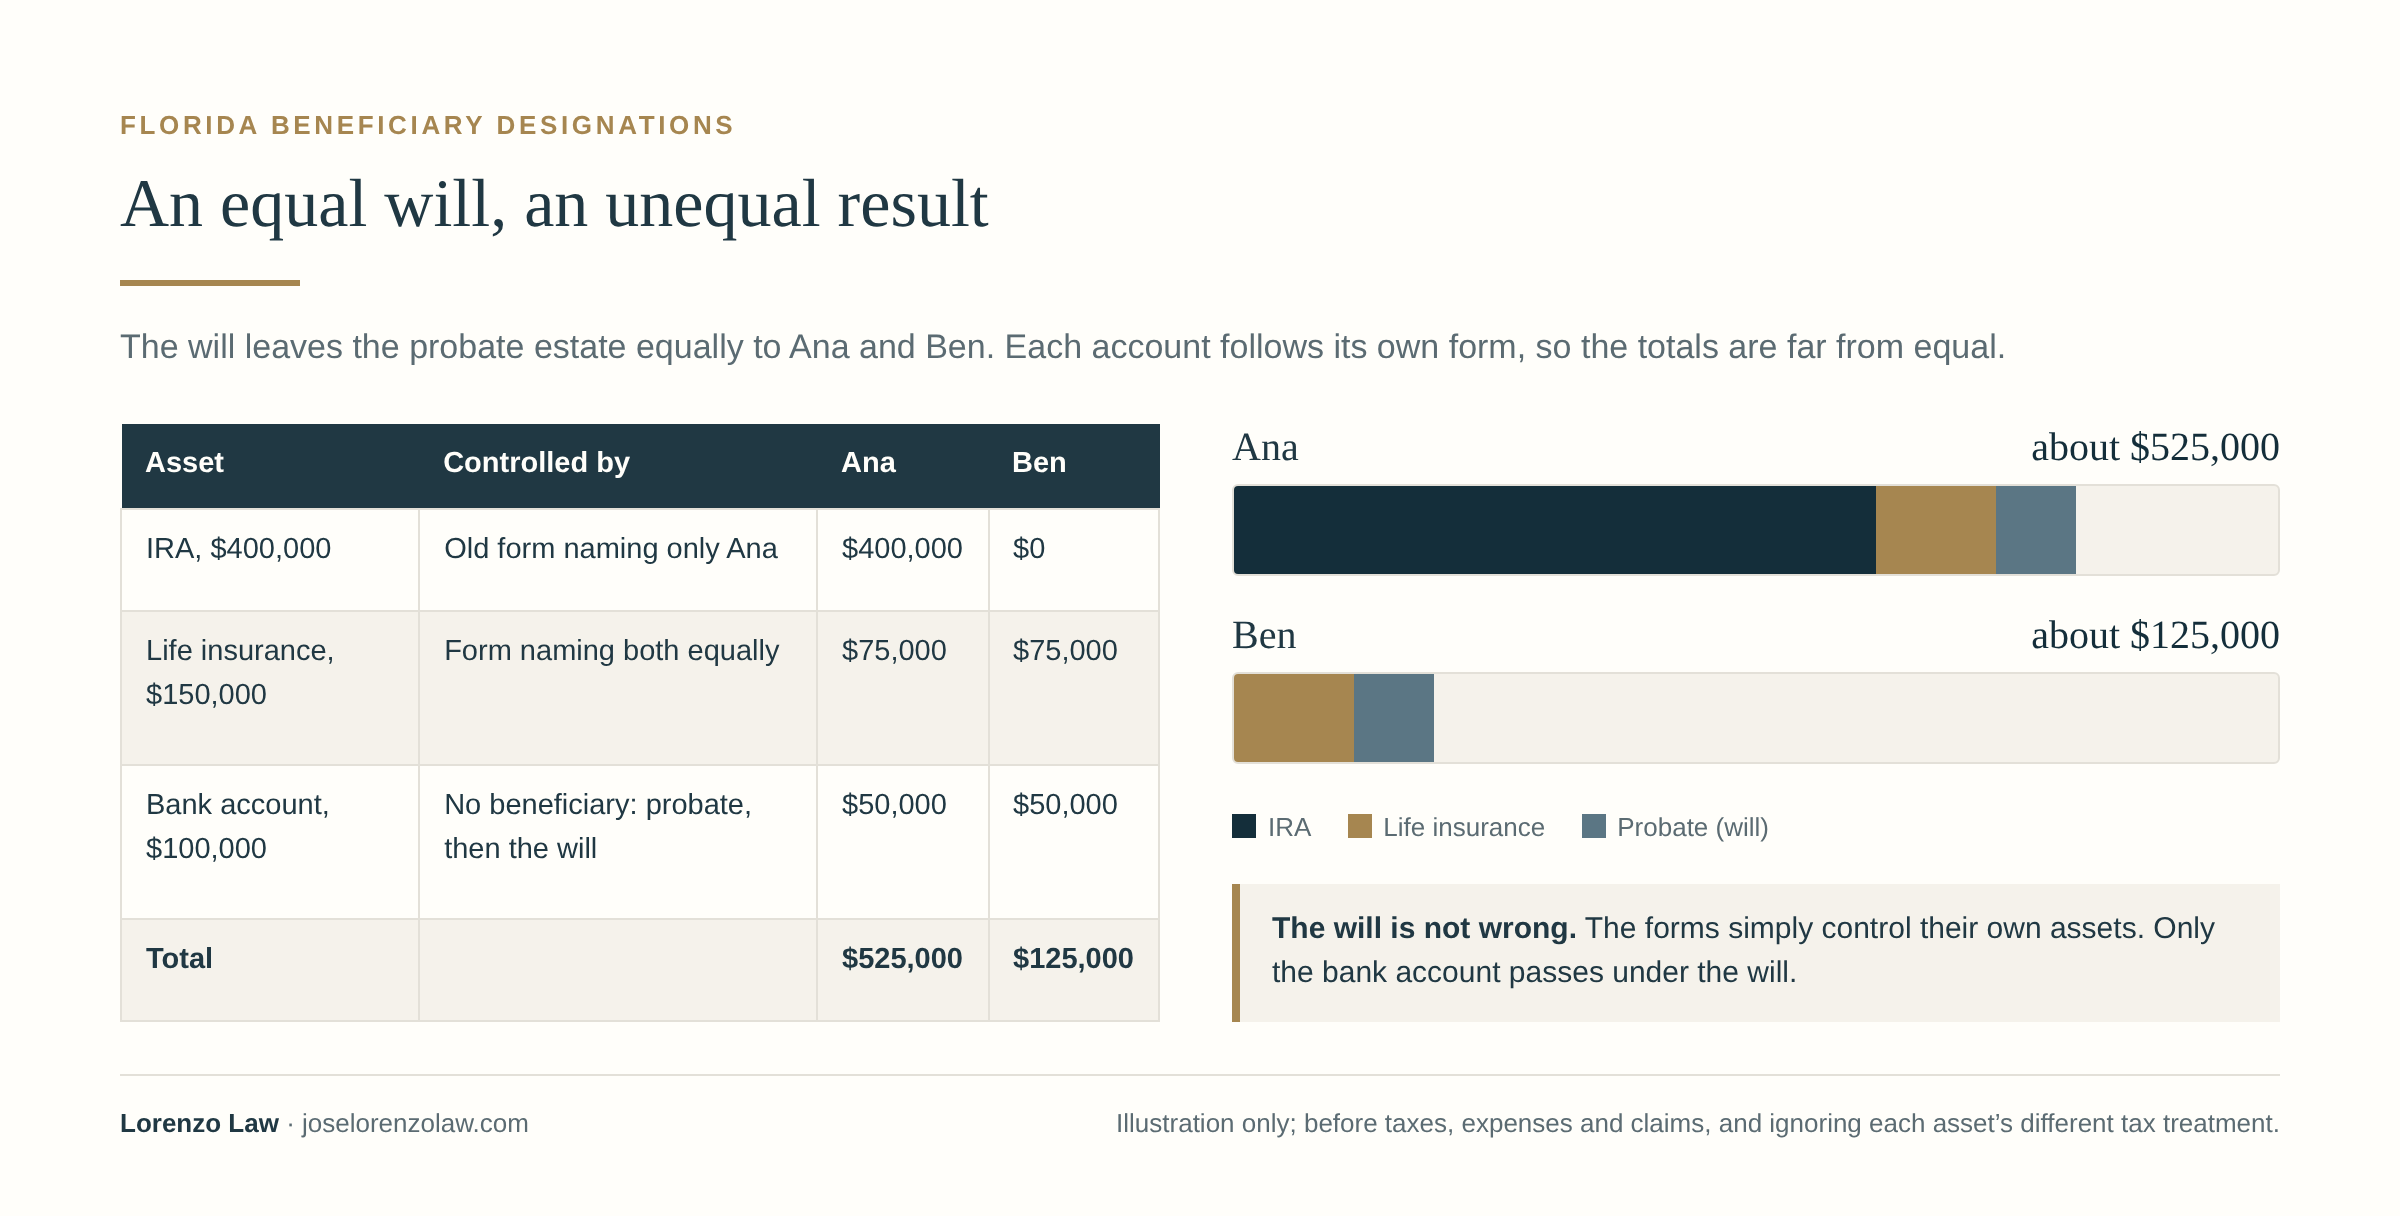
See the chart “An equal will, an unequal result” (opens the full-size image; the details are also in the text).
In the illustration, the will treats Ana and Ben equally, but an IRA worth $400,000 still names only Ana on a form signed years earlier, a $150,000 policy names both equally, and only a $100,000 bank account passes under the will. Before taxes, expenses and claims, Ana receives about $525,000 and Ben about $125,000. The will is not wrong; the forms simply control their own assets.
Check these common beneficiary designation mistakes, mismatches and oversights:
- The will says equal shares, but a major account names only one child.
- The trust provides staged distributions, but the account pays the child directly.
- An old designation names a deceased person or a former spouse.
- A trust amendment changes intended recipients, but a separate account still names individuals.
- A rollover, job change or institution transfer leaves the new account with different beneficiary records.
- The will names someone to administer the estate, but that person is mistakenly listed personally to receive funds intended for estate expenses.
Naming someone individually normally gives that person the designated benefit; it does not automatically impose an obligation to share it or pay family expenses. If the goal is managed distribution, use an appropriate legal arrangement instead of an unwritten expectation.
Beneficiary records that change without you noticing
Beneficiary records can be lost or replaced when a bank merges, a brokerage changes custodians, an employer changes plan providers, or an account is rolled over into a new IRA. A new account may start with no beneficiary or with a default. Request the current designation record from each institution rather than relying on the copy in your files, and confirm it again after any rollover, transfer or change of employer.
Avoiding probate is one goal, not the only one
Beneficiary designations can move assets quickly and outside probate, but avoiding probate is not always the right result for every asset. An outright payment may be wrong for a minor, a person with special needs, a beneficiary facing creditors or divorce, or a family that needs one person to manage and divide assets. Sometimes a trust, or deliberately letting an asset pass through the estate, serves the plan better.
Taxes, retirement distributions and charities
Beneficiary choice can affect taxes and distribution timing, but “outside probate” does not mean “tax-free.” Florida has no state inheritance tax, but federal income tax can still apply to some inherited assets. Life insurance death proceeds are generally excluded from federal gross income, with exceptions; interest can be taxable, so the tax implications for a life insurance beneficiary are usually narrower than for an inherited IRA. Moving an asset by POD or TOD designation, including an individual TOD account, does not by itself create or avoid tax. Traditional IRA distributions can be taxable, while basis and other rules can change the amount. Roth and inherited-account rules require separate analysis. See the IRS life insurance explanation, Publication 590-B and Florida inheritance tax.
The applicable inherited-retirement deadline depends on the account, the owner’s death, the beneficiary category and other facts. Under the SECURE Act, many beneficiaries face a ten-year rule, while eligible designated beneficiaries, such as a surviving spouse, a minor child of the owner, a disabled or chronically ill beneficiary, or a beneficiary not more than 10 years younger than the owner, may have other options. An individual who is not in those categories is a non-eligible designated beneficiary and generally follows the ten-year rule. A beneficiary that is not an individual, such as an estate, a charity or certain trusts, is a non-designated beneficiary and generally faces a different payout rule. According to IRS Publication 590-B, the designated beneficiary is officially determined on September 30 of the year after the owner’s death, and only someone who was a beneficiary at death can qualify. A ten-year rule does not mean every beneficiary follows the same payment schedule. For detailed retirement questions, use the IRA and 401(k) beneficiary resource and obtain advice for the particular account before taking distributions or attempting a rollover.
A charitable designation can be part of a coordinated plan, but the appropriate asset depends on the charity’s status, the account and the family’s objectives. One benefit of naming a charity rather than family members as beneficiary of a traditional IRA is that a qualified charity generally pays no income tax on the distribution, while family members generally do. This page does not recommend a particular investment, allocation, rollover or tax strategy. Review those decisions with the appropriate legal and tax advisers. See charitable bequests.
Digital accounts and cryptocurrency
Authority to access a digital account is not necessarily ownership of its contents or underlying assets. Section 740.003 addresses directions for disclosure of digital assets, including qualifying online tools and estate documents. Do not assume a legacy contact inherits cryptocurrency or that a power of attorney remains usable after death. Review ownership, platform terms, permitted disclosure and lawful access separately. Never include passwords, recovery phrases or private keys in a public worksheet or inquiry.
Want the forms checked against your will or trust? The review starts with the asset list and the current designation records. Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing.
Who should you not name directly as a beneficiary?
There is no universal list, but some choices often create avoidable problems when made without review: your estate, a minor child, a person who receives means-tested benefits, a person who needs help managing money, and a deceased or outdated beneficiary. In each case an alternative may fit better.
| Naming directly | Why it can cause problems | Alternative to consider |
|---|---|---|
| Your estate | Can bring the asset into probate and change creditor and tax treatment | Named individuals or a trust, after an asset-specific review |
| A minor child | A child cannot manage the money; larger amounts may need a guardianship of the property | A FUTMA custodian or a trust |
| A person receiving SSI or Medicaid | An outright inheritance may affect eligibility | A properly designed third-party special needs trust |
| A person with creditor, addiction or money-management concerns | An outright payment arrives with no management | A trust with appropriate distribution terms |
| One child, expecting that child to share | The named person generally has no legal duty to share | Name each intended person, or a trust |
| A deceased person or former spouse | The share may lapse, pass to a default or lead to a dispute | A current form with primary and contingent beneficiaries |
After a death: records, claims and timing
Notify each institution through its official process, request its claim requirements and the current designation record, and do not assume the will, an old copy of a form or a relative’s expectation controls. A valid designation often avoids probate for that asset, but timing varies.
Depending on your role and authority, relevant records can include the current designation, change history, policy or account agreement, plan documents, death certificate, trust identification and any spouse-consent or divorce documents. The institution may limit what it can disclose until authority is established.
The documents determine whether payment goes directly to a beneficiary, to a trustee, through an estate or into a disputed-claim process. There is no universal two-to-four-week payment guarantee. Missing records, identity checks, trust questions, competing claims and court orders can affect timing.
If the estate is entitled to receive the asset, a will alone does not necessarily establish authority to collect it. The appropriate administration or other lawful collection procedure must be determined. For deposit-account procedures and transferring money from a deceased person’s bank account, see what happens to a bank account when someone dies in Florida, and for the first steps generally, what to do when someone dies in Florida.
How to find out whether you are a beneficiary
An insurer may not learn of a death, or find the beneficiary, on its own. Family members can search for unknown policies and annuities through the NAIC Life Insurance Policy Locator, and unclaimed accounts or benefits turned over to the State of Florida can be searched at FLTreasureHunt.gov, the Florida Chief Financial Officer’s unclaimed property site. Old statements, tax forms, employer benefits records and mail are also good leads.
Life insurance claims and competing claimants
To claim life insurance as a beneficiary, you usually submit the insurer’s claim form and a certified death certificate. A beneficiary payout upon death is often a lump sum, though some policies offer installments or other settlement options, and proceeds due to a minor beneficiary follow the rules in the minors section. A beneficiary who lives in another country, or who is out of the country, can generally still be paid, but insurers usually ask for additional identity and tax documents.
If the insured died during the policy’s contestability period, the insurer may review the application before paying. Florida law also governs interest on lump-sum death-claim payments (§ 627.4615). Questions about a delayed or denied claim can also be raised with the Florida Department of Financial Services, the state’s insurance consumer agency.
When two people claim the same proceeds, for example a former spouse and the current family, an insurer may hold payment or ask a court to decide who is entitled. If you are disputing a life insurance beneficiary designation, contesting a payout, or believe the company paid the wrong beneficiary, preserve the records and get advice promptly, because payor-protection rules can limit claims against an insurer once it has paid.
Can a beneficiary designation be challenged?
Yes, a beneficiary designation can be contested, and a judge can set it aside (overturn it) on a recognized ground, but a disappointing result is not enough. Potential issues include an ineffective change, forgery, fraud, lack of required capacity, undue influence, an agent’s change made without specific authority, competing ownership, spouse rights or a controlling court order. Florida courts have set aside a payable-on-death designation procured by undue influence (Keul v. Hodges Blvd. Presbyterian Church, 180 So. 3d 1074 (Fla. Dist. Ct. App. 2015)). A disappointing result or a conflicting will alone does not establish a successful challenge. The cause of action, legal standard, claimant’s rights, proper parties and deadline depend on the asset and facts.
Will-contest statutes are not automatically the governing rules for an insurance or retirement designation dispute. A paying institution may seek a court determination, but interpleader is not the inevitable first step in every case. Preserve complete records and seek advice promptly about notice, available relief and any plan claim or appeal procedure. An informal objection or consultation request does not necessarily stop payment or preserve a deadline.
Florida’s slayer statute, § 732.802, can disqualify someone who unlawfully and intentionally kills the decedent, including in specified contractual and survivorship arrangements. Federal-law questions and the statute’s notice and payor-protection provisions still require review; do not assume every institution follows the same notice rule.
For a disputed transfer, start with Florida estate litigation or challenging transfers made before death so the appropriate claim and forum can be evaluated.
A beneficiary review worksheet to use privately
Review every designation when you sign or update a will or trust, after any major life event, and periodically as part of your planning review. Use the worksheet below privately, one row per asset.
Keep the completed worksheet in your private records. Use an asset nickname, not an account number. Do not enter Social Security numbers, dates of birth, passwords, policy numbers or financial documents into a public form. Ask the firm how to provide necessary records securely after intake.
| Asset nickname and type | Current owner(s) and controlling document | Primary beneficiary and percentage | Backup beneficiary and deceased-beneficiary rule | Confirmation date and next action |
|---|---|---|---|---|
| Example: savings | Sole owner; deposit agreement and POD record | Intended adult recipient, 100%; verify | Ask what happens if the recipient dies first | Request current record |
| Example: workplace plan | Participant; plan, designation and any spouse or QDRO records | Verify accepted designation and spouse consent | Verify the plan’s backup and default provisions | Ask the administrator |
| Example: policy | Policy owner, insured and policy terms | Person or identified trust; verify | Confirm contingent beneficiary, per stirpes election and survival terms | Retain insurer confirmation |
| Your asset: |
For each row, answer: Does this asset go where the will or trust assumes it goes? Is the recipient able to receive it outright? Are spouse, divorce, disability, tax or creditor issues relevant? Are all shares and contingencies valid for this particular product? Who will complete any needed follow-up?
Beneficiary review checklist, before you consider the review complete:
- Obtain the institution’s current beneficiary record, rather than relying only on an old copy.
- Identify ownership and the controlling agreement or plan.
- Compare primary and backup recipients with your current intentions and trust terms.
- Review restrictions before submitting changes, especially after marriage or divorce.
- Use the institution’s required process and retain its confirmation; investigate any rejection or mismatch.
- Revisit the records after family changes, beneficiary deaths, trust changes, employment changes, rollovers and institution transfers, and periodically as part of your planning review.
This worksheet is an inventory aid, not a beneficiary designation, change request, financial recommendation or legal instrument.
Questions readers ask about Florida beneficiary designations
What takes precedence, a will or a beneficiary designation?
For an asset with a valid, effective beneficiary designation, the designation generally takes precedence over the will, because the asset passes under the contract or statute and not through the probate estate. The will controls probate property and anything that ends up payable to the estate. Exceptions include an ineffective form, no surviving beneficiary, divorce, spouse rights, federal plan rules and court orders.
Can a newer will change my life insurance beneficiary?
Generally, a newer will does not replace an effective policy designation. Use the insurer’s permitted change procedure while authorized to do so, and consider any irrevocable designation, spouse rights or court order. If the policy pays the estate, the will may affect distribution through the estate.
Does a beneficiary on a bank account override a will?
Generally, yes, for that account. A POD beneficiary on a Florida deposit account takes the funds when the sole or last surviving account party dies, under § 655.82 and the account agreement, regardless of a contrary will. Surviving joint owners take first, and if no POD beneficiary survives, the funds go to the last account party’s estate.
Does naming a beneficiary mean I no longer need a will?
No. The designation addresses only the covered asset. A will can address probate property and other planning needs, while a trust or survivorship arrangement may control other property. Review the plan as a whole.
Does a living will override a beneficiary designation?
No. A living will is a health care document that states end-of-life medical wishes; it does not transfer property or change a beneficiary. A last will and testament controls probate property, and a beneficiary designation controls the asset it covers. See what a living will is in Florida.
Can an executor override a beneficiary designation?
No, an executor cannot simply redirect an asset governed by a valid beneficiary designation. The executor and beneficiary have different rights and responsibilities; this is not a general ranking of who has more power. A personal representative, often called an executor, administers the probate estate and cannot redirect an asset that passes to a named beneficiary outside the estate. The personal representative becomes involved only if the asset is payable to the estate, or if there is a legal basis to challenge the designation.
Can a beneficiary designation be changed after the owner dies?
No. Only the owner, or someone with proper legal authority during the owner’s life, can change a designation. After the death, the remaining options are a claim that the designation was invalid, a beneficiary’s disclaimer or a court proceeding.
Is a spouse automatically the beneficiary?
Not automatically on most IRAs, POD accounts or life insurance policies; the form controls. Many employer retirement plans governed by federal law do protect a surviving spouse unless the spouse gave valid consent, and a plan’s default rules may favor a spouse when no beneficiary is named. Florida’s elective share and homestead rights are separate protections.
Can a spouse override a life insurance beneficiary?
A surviving spouse cannot simply override a valid life insurance designation. But the Florida elective share counts life insurance at its net cash surrender value, employer-provided coverage can raise federal-law issues, and a divorce judgment or settlement can require specific coverage. Each needs to be reviewed against the policy.
Does life insurance go to next of kin?
Not simply because someone is the closest relative. If no beneficiary is named, who gets life insurance depends on the policy’s default terms. The effective designation, policy defaults and governing law determine entitlement. If proceeds become payable to the estate, the will or intestacy rules may then affect their distribution.
How do I add a beneficiary to a life insurance policy or bank account?
Ask the insurer or bank for its current beneficiary-change or POD form, or use its online process. For life insurance, identify the primary and contingent beneficiaries and percentage allocations that the policy and form permit. For a Florida POD bank account, identify the beneficiaries under the deposit agreement and § 655.82; surviving beneficiaries share equally under that statute, so do not import insurance-form allocation or backup options. Obtain any required signatures, submit the request through the institution’s process, and retain confirmation. A will or generic letter is not a substitute for that process.
What is the difference between POD and TOD in Florida?
Payable on death (POD) designations are used on bank deposit accounts and are governed in Florida by § 655.82. Transfer on death (TOD) registrations are used on securities and brokerage accounts and are governed by the Florida Uniform Transfer-on-Death Security Registration Act in Chapter 711. Both pass the asset outside probate to the named beneficiary, but the rules on surviving owners, substitutes and descendants differ.
What are the disadvantages of a POD account?
The pros and cons are worth weighing: a POD account is simple and usually avoids probate for that account, but a POD arrangement may not provide ongoing management, staged distributions or a substitute for a deceased beneficiary in the way you expect. It must also coordinate with surviving owners, spouse rights and the rest of the estate plan. Probate avoidance alone does not resolve those issues.
Do Florida beneficiaries pay tax on what they inherit?
Florida has no state inheritance tax. Federal income tax can still apply: life insurance death proceeds are generally excluded from federal gross income, but distributions from an inherited traditional IRA or 401(k) are generally taxable to the beneficiary, and interest is taxable. Large estates may also face federal estate tax. Ask a tax adviser about the particular account.
Does Florida have a transfer on death deed?
Florida does not have a general transfer on death deed statute for real estate. Florida owners who want a home to pass outside probate often consider an enhanced life estate (Lady Bird) deed or a revocable trust, subject to homestead restrictions. A beneficiary form on a bank or brokerage account does not transfer real estate. Articles about the downside of a TOD deed usually describe other states’ deeds; in Florida the comparison is with a Lady Bird deed or a trust.
What does “per Florida law” mean on a Florida Retirement System beneficiary form?
It refers to the beneficiary order set by Florida law. According to FRS, if you do not name a beneficiary, Florida law will determine your beneficiary, so the statutory order in Chapter 121 applies instead of a person you choose: spouse, then children, then parents, then the estate (§ 121.091(8)(a) for the Pension Plan; § 121.4501(20)(a) for the Investment Plan). To control who receives FRS benefits, complete the FRS beneficiary designation for your plan and keep the confirmation.
Should I name my estate as beneficiary?
That can be a deliberate choice, but it can bring the asset into estate administration and affect creditor or tax treatment. Life insurance payable to the estate has a specific statutory consequence under § 222.13. Review the actual asset before choosing an estate designation or rejecting one automatically.
Can I name a trust and still avoid probate for that asset?
A valid designation to an eligible, properly identified trust can direct payment to its trustee outside the probate estate. Whether it works depends on the contract, trust and applicable law. It does not guarantee creditor protection, favorable tax treatment or acceptance of an incorrectly completed form.
Are IRA and 401(k) beneficiary rules identical?
No. Employer-plan spouse protections, consent requirements, plan defaults and federal preemption can differ from IRA rules. Review the specific plan or custodial agreement; do not assume a rollover preserves the former beneficiary arrangement or every protection.
Can a beneficiary refuse (disclaim) an inheritance?
Often, yes. Florida’s disclaimer law, Chapter 739, allows a beneficiary to refuse all or part of an interest if the disclaimer meets its requirements for form, delivery and timing; the disclaimed interest then generally passes as if the disclaimant had died first (§§ 739.104, 739.201(3)(a), 739.301(1), 739.401, 739.402(2)(a)). Tax rules for a qualified disclaimer are separate, and accepting benefits first can prevent a valid disclaimer.
How often should beneficiary designations be reviewed?
Whenever you sign or update a will or trust, after a marriage, divorce, birth, adoption or death in the family, after a rollover, job change or bank merger, and periodically in between. Request the institution’s current record each time rather than relying on your own copy.
Can a beneficiary live in another country?
Generally, yes. A life insurance or account beneficiary can live outside the United States, but the institution may require additional identification, tax forms and payment arrangements, and tax withholding can apply. Ask the institution what it requires before naming someone abroad, and keep current contact information on file.
Will I be notified if I am a life insurance beneficiary?
Not necessarily. An insurer may not learn of a death or locate a beneficiary on its own. Families can use the NAIC Life Insurance Policy Locator and Florida’s unclaimed property search, and should review the decedent’s records for policies, employer benefits and annuities.
Can Lorenzo Law review forms together with my will or trust?
You can request an initial consultation about coordinating your estate plan or evaluating a disputed transfer. The firm will assess the proposed work and agree on any representation separately. Account changes, institution acceptance, tax advice and post-death representation should not be assumed to be included in every planning engagement.
Discuss your beneficiary designations with Lorenzo Law
Jose M. Lorenzo, Jr. is Lorenzo Law’s sole attorney (Florida Bar No. 107002). Clients work directly with Jose: the attorney you speak with at the first call is the attorney who handles any matter the firm accepts.
If you are looking for a beneficiary lawyer, a trust beneficiary lawyer or a life insurance beneficiary dispute lawyer in Florida, or comparing beneficiary designation attorneys and estate planning attorneys, ask who will actually review your forms. If you searched for a “beneficiary lawyer near me,” phone and video consultations are available statewide, and a free initial consultation is available on the terms stated below.
Consultations are available in English and Spanish, by phone or video, with in-person meetings by appointment. The principal office is in Kissimmee, Florida, with by-appointment meeting locations in Coral Gables and Fort Lauderdale.
For planning, explain the asset types and what you want the combined plan to accomplish; wills start at $675, all-inclusive, and current planning options are on the Florida estate planning page. For a post-death issue, identify your role, the institution, the disputed designation and any notice or deadline. Provide sensitive records only through the agreed intake process. Representation depends on conflict review, acceptance and a written engagement; an inquiry alone does not create an attorney-client relationship.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing.
Request a free initial consultationCall (305) 224-6811
¿Prefiere español? Jose M. Lorenzo, Jr. atiende consultas en español sobre designaciones de beneficiarios, cuentas pagaderas al fallecer y la relación entre el testamento y los formularios de beneficiario. Lea también qué pasa con la cuenta bancaria de un fallecido.
This page provides general information about Florida law, not advice about a particular account, tax decision or dispute. Reading it, using the worksheet or requesting a consultation does not create an attorney-client relationship.
Sources and authorities cited
Statutes cited are Florida Statutes unless noted. The text of the law, the governing contract and the plan documents control over any summary on this page.