Charitable Bequest in a Florida Will: How to Leave Money or Property to Charity
A charitable bequest in a Florida will is a gift of money, property or a share of your estate to an organization, made in a will that meets Florida’s signing rules.
To leave money to charity in your will, identify the organization by its exact legal name, choose the amount or share, decide what happens if the charity cannot take the gift, and confirm that the will actually controls the asset, because a will generally does not redirect an account that passes under a beneficiary designation. This guide covers the five gift structures, the wording, the limits Florida law places on giving everything away, what happens if the charity closes, and the tax questions to settle first.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing. Consultations are available statewide in English and Spanish, by phone or video.
Request a free initial consultationCall (305) 224-6811
Go straight to: Gift structures · Wording · If the charity closes · Taxes
By role: someone writing a first will should start with which document controls the gift; someone adding a charity to an existing plan, with how to add or change a gift; a personal representative or a charity’s planned-giving office, with what happens after death.
All guide sections 20 sections
Short answer. What is a charitable bequest in a Florida will? It is a gift of money, a particular asset or a share of what remains in your estate, directed to an organization in a will that meets Florida’s signing rules. To make the gift work, name the organization by its exact legal name, say what it receives and from which fund, decide what happens if it cannot take the gift, and confirm that the will actually controls the asset. A will generally does not redirect an account that passes under an effective beneficiary designation.
| What it is | A gift at death to an organization, made in a will (Florida’s probate statutes call it a devise) or, with different mechanics, in a trust or on an account form. What a charitable bequest means |
|---|---|
| Ways to structure it | A fixed dollar amount, a particular asset, a percentage of a defined fund, all or part of the residue, or a gift that takes effect only if another beneficiary cannot inherit. The five gift structures |
| What the wording must do | Identify the organization (legal name, address, EIN), the property or share, any purpose restriction, and the backup if the charity has changed, merged or closed. Illustrative language |
| What can defeat it | An account that passes outside the will, a sold or missing asset, an estate too small to pay every gift, a charity that no longer exists, or a spouse’s or minor child’s protected rights. If the charity closes · Limits |
| Taxes | Florida has no estate or inheritance tax. A qualifying gift may support a federal estate-tax deduction; a revocable bequest creates no income-tax deduction during life. Taxes |
| How it is signed | In writing, signed at the end by the testator before two attesting witnesses who sign in the presence of the testator and of each other (§ 732.502). A codicil follows the same rule. Adding or changing a gift |
| Consultation | Principal office in Kissimmee; Coral Gables and Fort Lauderdale by appointment; statewide by phone and video, in English and Spanish. Only the initial consultation is free. |
Jose M. Lorenzo, Jr. prepares and reviews Florida wills and trusts that include gifts to charity, coordinates those gifts with account designations, and advises personal representatives administering estates in which a charity is a beneficiary. Wills start at $675 per person, all-inclusive for the agreed will service; the scope of any charitable-gift work is confirmed in writing before it begins.
According to Giving USA 2026, Americans left an estimated $62.2 billion to charity through bequests in 2025, roughly one dollar in ten of all giving in the United States. The rest of this guide explains how to include a charitable bequest in a Florida will.
What a charitable bequest means
What is a bequest? The bequest definition is short: a gift made at death through a will. When the recipient is a charity, it is a charitable bequest, and leaving money to charity in your will is one form of planned gift. People use the same word for gifts at death under a trust, although the trust’s terms govern that transfer. Florida’s probate statutes use the term devise for any testamentary disposition, whether of land, money or other property. The recipient is a beneficiary; for a charitable gift, that recipient should be the intended organization, not an informal project name or a person who works there.
A bequest to charity, then, is simply a devise whose beneficiary is an organization; to remember a charity in your will is to make one. The main difference between a donation and a bequest is timing and control: donating to charity in your will gives nothing now and can be changed, while a completed lifetime donation is gone. Leaving a bequest to charity therefore differs from a completed lifetime donation. With an ordinary revocable will, signing the document does not transfer anything now. You keep the property, you can spend it, and you can revise the plan while you have the required capacity (§ 732.501). A binding pledge, a contract to make a will, or an irrevocable arrangement raises different questions and should be reviewed separately. Nonprofits call such a gift a planned gift or a legacy gift, describe the practice as legacy giving or leaving a legacy to charity in your will, and use the phrase legacy society for the group of donors who have told the organization that it is in their plans. Giving to charity in your will should be coordinated with the rest of your estate plan.
The gift need not be large. What matters is whether its terms fit the resources likely to remain and the recipient’s acceptance policies. A small unrestricted gift may be easier to administer than an endowment that requires a substantial minimum funding level.
The words a Florida will uses for these gifts
- Devise, bequest, legacy
- Florida law uses devise for any testamentary gift, that is, any gift made by a last will and testament. Bequest and legacy are the traditional words for gifts of money or personal property. On this page, bequests and legacies mean the same thing, and what it says about Florida wills and bequests applies equally to legacies in wills.
- Specific devise (specific bequest)
- A gift of an identified item or asset: a described painting, a particular account, a parcel of land.
- Pecuniary (fixed dollar) gift, or general bequest
- What is a pecuniary bequest? A stated sum of money. A gift of “$10,000” is a general gift payable from the estate’s assets, not a specific devise, unless the will ties it to an identified source.
- Demonstrative gift (demonstrative bequest)
- A sum payable first from a named source, such as “$10,000 from my account at a named bank,” with the balance from general assets if that source is short.
- Residuary gift (residuary bequest) and residuary clause
- The residue, also called the residuary estate or the remainder of the estate, is what remains after debts, expenses, taxes and the specific and general gifts. The residuary clause says who receives it; a charity can take all of it or a fraction.
- Percentage gift
- A stated fraction of a defined fund. The wording must say what the fraction is of: the residue, a particular account, or another defined pool.
- Contingent (conditional) bequest
- A gift that takes effect only on a stated condition, usually that another beneficiary does not survive or cannot take.
- Bequest vs inheritance
- An inheritance is what a person receives from an estate, under a will or, without one, under Florida’s intestacy rules. A bequest is the gift the will itself makes. A charity receives bequests; it does not inherit by intestacy.
- Lapse
- When does a bequest lapse? When the beneficiary cannot take it, for example because the person died first or the organization no longer exists. Who receives a bequest that lapses is then a question for the will and the statute. Florida has default rules for where a failed gift goes (§ 732.604). Florida’s antilapse statute, which can substitute a deceased relative’s descendants, does not apply to a gift to an organization (§ 732.603).
- Ademption
- What happens when specifically devised property is no longer in the estate at death, subject to statutory exceptions (§ 732.606).
- Abatement
- The order in which gifts are reduced when the estate cannot pay everything (§ 733.805).
- Cy pres
- A court’s power to redirect a charitable gift whose purpose or recipient has failed to a use as near as possible to the original. Florida’s statute covers charitable trusts (§ 736.0413); courts also apply the doctrine to outright gifts in wills when the will shows a general charitable intent and names no workable alternative.
Are bequests revocable? In an ordinary will, yes: every gift can be changed while you have the required capacity (§ 732.501), until death. A binding pledge, a contract to make a will, or an irrevocable arrangement is different. Which label applies to a gift is not a formality. Classification decides how the gift is treated if the estate is short, if the asset is gone, or if the charity cannot take it, so the review of any charitable clause starts by asking which of these it is.
Which document controls the gift?
Start with ownership and existing beneficiary instructions before choosing a clause. A will controls property that passes through probate. It generally does not override an account’s beneficiary form, a deed with survivorship rights, or property already titled in a trust.
| Asset or arrangement | Document to check | Planning issue |
|---|---|---|
| Individually owned property without a direct-transfer arrangement | Will, title and estate administration requirements | A bequest in the will may govern; debts, expenses and protected rights still come first. |
| Property already owned by a trust | Trust and amendments, plus proof of ownership | The trustee follows the trust (§ 736.0602). Amend it by the method the trust provides — which the trust itself could allow to be a will. Only if the trust provides no method may a later will or codicil that expressly refers to the trust, or specifically devises trust property, change it (§ 736.0602(3)(b)). Review the trust and the proposed will together. |
| IRA, retirement plan or life insurance | Current beneficiary form and the provider’s rules | Use the provider’s process and check spouse-consent or plan restrictions where applicable. |
| Bank or brokerage account with POD or TOD instructions | Account agreement and accepted designation | Confirm that the institution permits the intended organization and records the designation correctly. |
| Jointly owned property | Deed or account agreement | An effective survivorship right can control at death; a will cannot simply give away the survivor’s ownership. |
| A donation completed during life | Transfer records and any gift agreement | A present transfer with different control and tax consequences. |
Naming a charity in your will and on an account may create two gifts. Conversely, a will clause may receive nothing if all the assets expected to fund it pass outside the estate. Reconcile both possibilities. For the fuller explanation, read whether a beneficiary designation overrides a will in Florida.
Hypothetical example. You intend a charity to receive 10 percent of what remains in your probate estate. Your largest account instead passes directly to a family member under its beneficiary form. The charitable percentage normally applies to the defined probate residue, not automatically to that separate account. Review the plan as a whole before assuming the percentages reflect your total wealth.
The five gift structures compared
The main options for leaving a legacy to charity through a will are five: you can plan a fixed gift, a particular asset, a percentage of a defined fund, a share of the residue, or a gift that takes effect only if another beneficiary cannot inherit. The structures overlap: a gift of 15 percent of the residue is both a percentage gift and a residuary gift. Each needs its own backup instruction.
| Structure | What it describes | What Florida law calls it | What to decide before drafting |
|---|---|---|---|
| Fixed dollar gift | A stated amount, such as $5,000 | A general (pecuniary) devise, unless tied to an identified source | How it will be funded if the estate becomes smaller or lacks cash. A dollar gift is not a legally “specific” devise just because the amount is specific. |
| Specific asset gift | Identified property, such as a particular painting or parcel | A specific devise | Whether the charity accepts it, and what should happen if you sell or no longer own it. |
| Percentage gift | A stated fraction of a clearly defined fund or share | Depends on the fund named: a fraction of the residue is a residuary devise | Whether the percentage applies to the residue, a particular account, or another defined pool. |
| Residuary gift | All or a share of what remains after obligations and prior gifts | A residuary devise | Who receives the rest, and what happens if a residuary recipient cannot take. |
| Contingent gift | A gift that applies on an identified condition | A conditional devise; the primary gift keeps its own classification | Define the condition and the final backup; do not rely on vague instructions such as “if needed.” |
A charity can be a primary or an alternate beneficiary under any of these structures. Can a specific bequest be a percentage? A fraction of an identified asset or account can be drafted as a specific devise of that share; a fraction of the residue is a residuary gift. The label follows what the percentage is taken from. A gift of a fraction of the whole estate is generally treated as a general gift, not part of the residue, so the residue is used up before that gift is reduced (§§ 731.201(35), 733.805); state this expressly to avoid dispute.
Fixed amounts and specific property
A fixed amount makes the intended gift easy to understand, but its share of your remaining estate grows if your assets decline, and it is paid in money even if the estate has to sell something to raise it. A particular asset raises a different question: will that property still exist and still belong to you when the gift takes effect?
Florida law distinguishes specific devises from other gifts when assets must be reduced to meet obligations (§ 733.805). It also protects certain rights tied to specifically gifted property — some unpaid sale, condemnation, or insurance proceeds, and sales by a court-appointed guardian of the property (§ 732.606). The exact language and the facts matter.
Percentages and the residue
Naming a charity as residuary beneficiary, for all or a fraction of the residue, is one way to give a share rather than a sum. A percentage adjusts as the value of the defined fund changes. Specify the denominator: “10 percent” without stating what it is 10 percent of invites uncertainty. Coordinate all shares so that the entire intended fund is disposed of, and name who takes a share that fails.
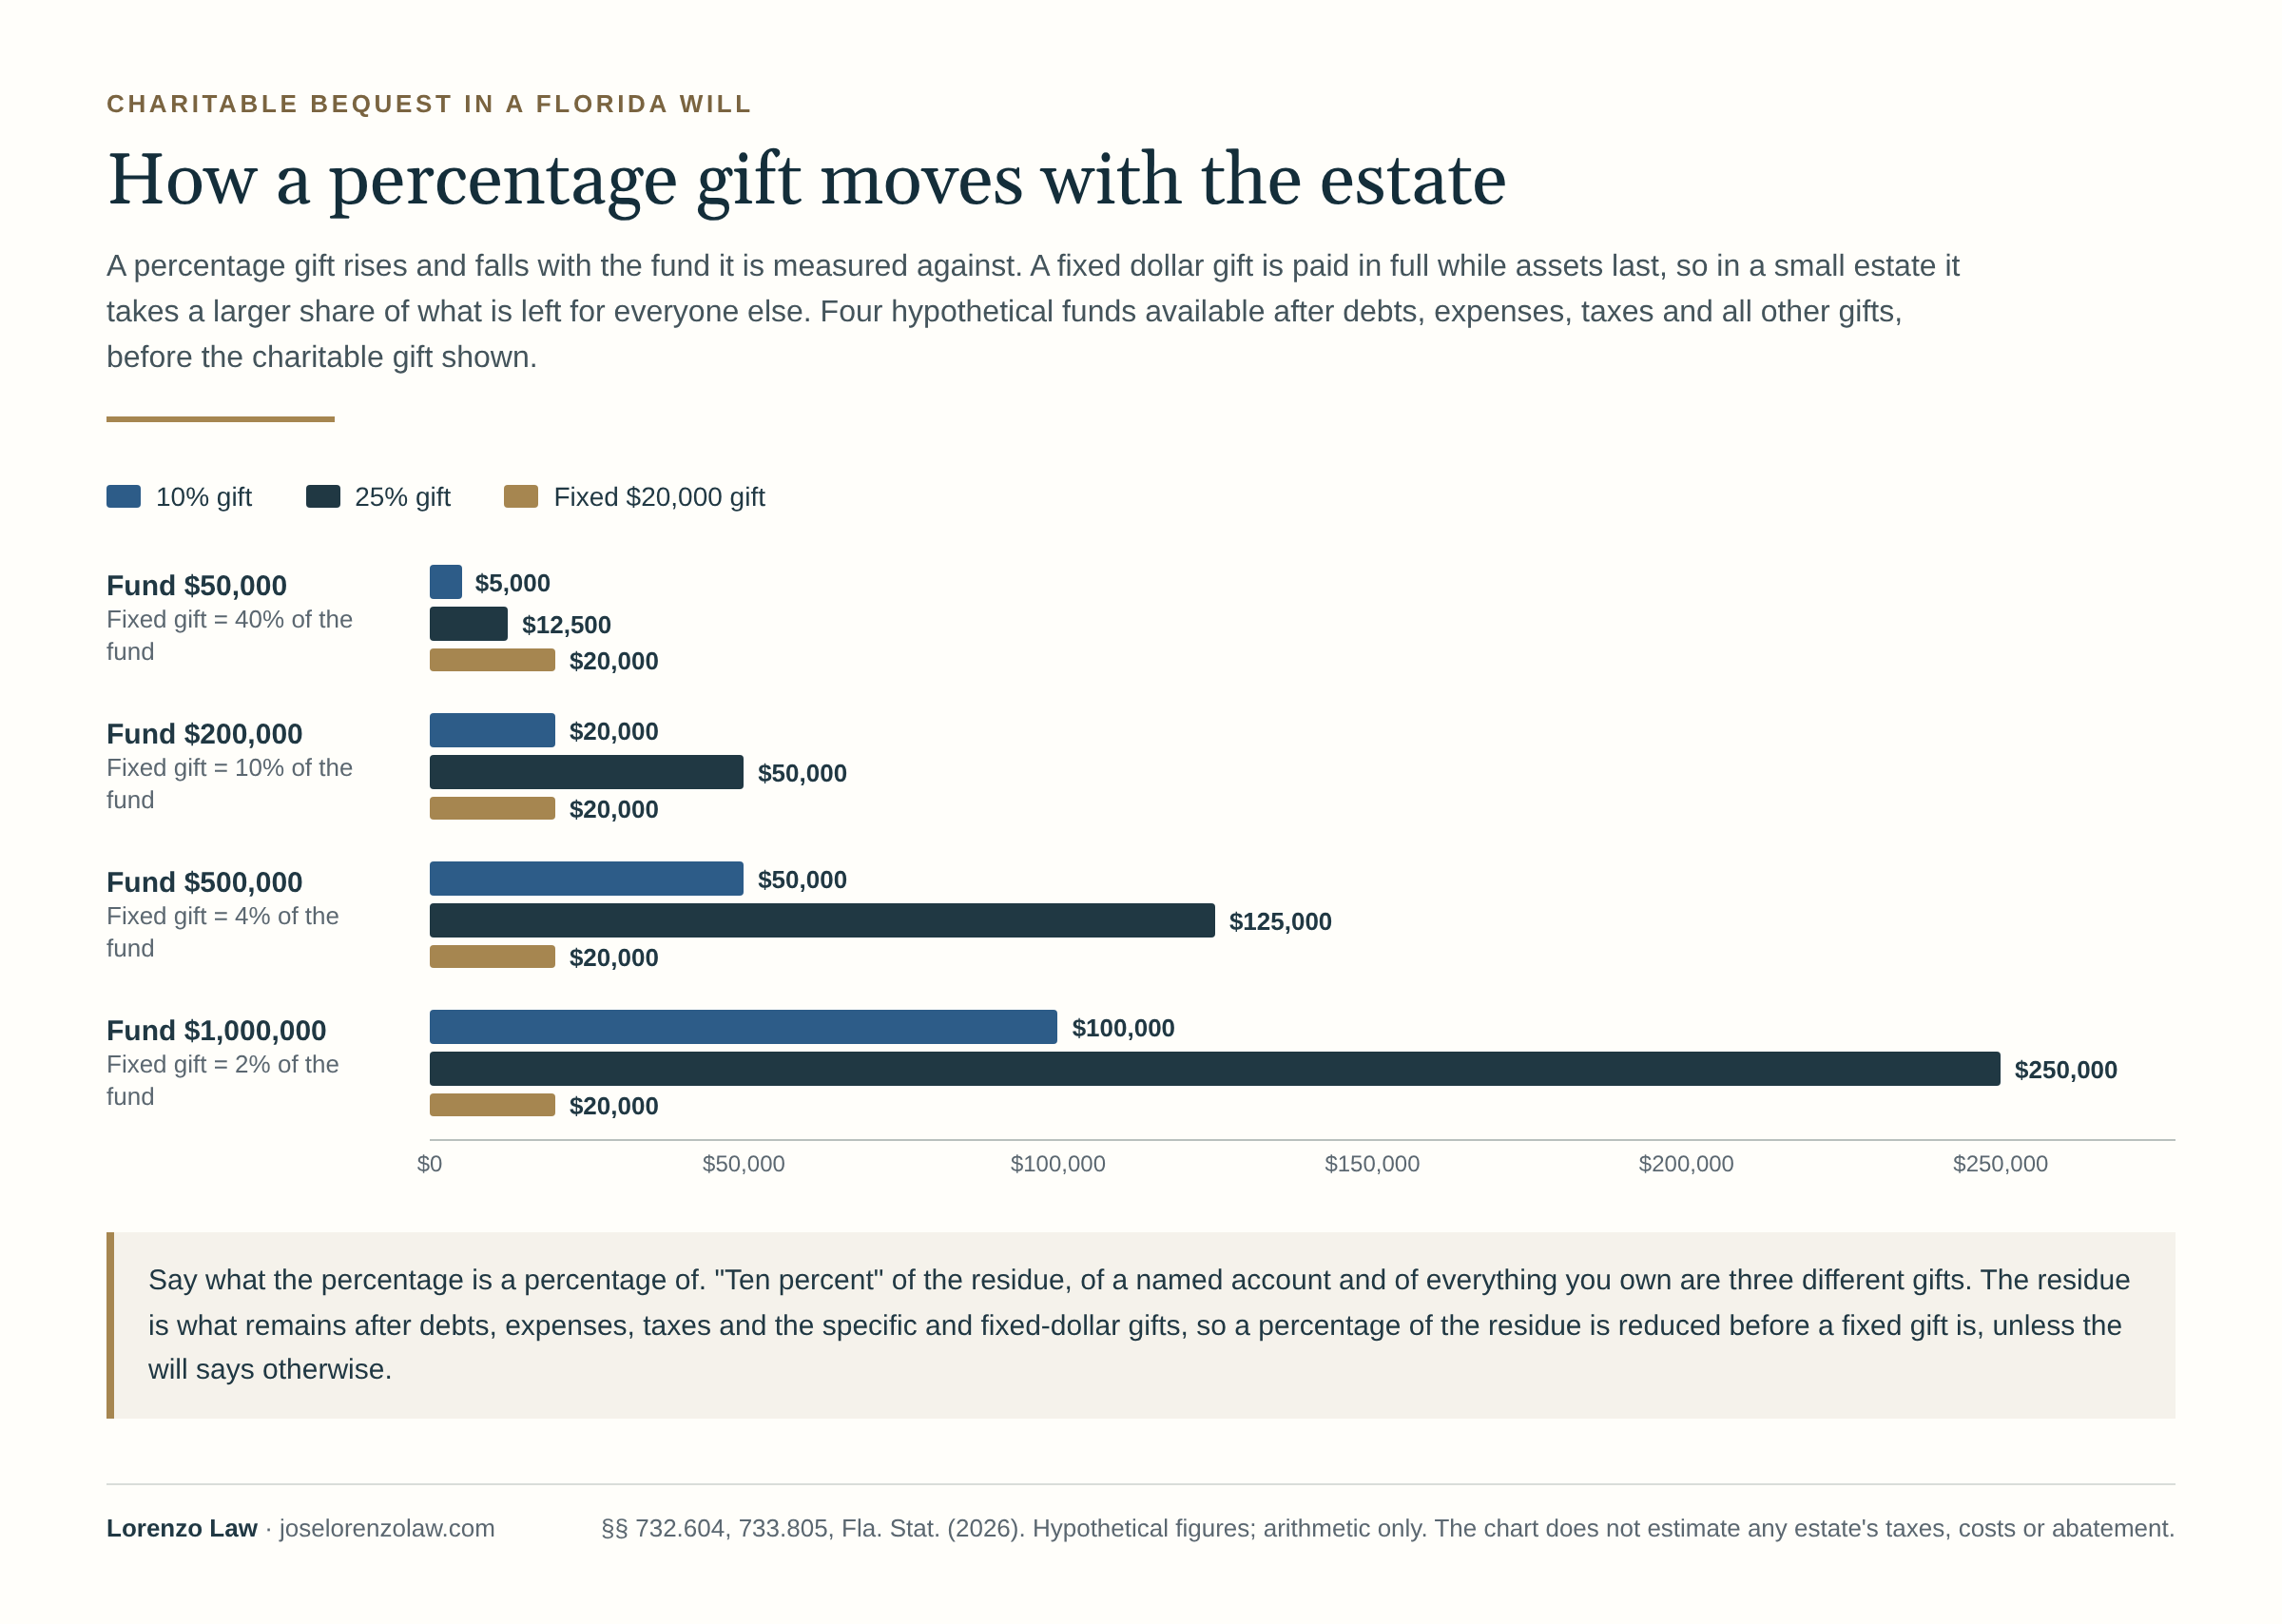
See the chart “How a percentage gift moves with the estate” (opens the full-size image; the details are also in the text).
Hypothetical calculation. Assume a fund is available after debts, expenses, taxes and all other gifts, but before the charitable gift shown. From a $200,000 fund, a 10 percent gift is $20,000; from a $50,000 fund, it is $5,000. A fixed $20,000 gift is $20,000 either way, and from the smaller fund it takes 40 percent, leaving less for everyone else. These figures assume the fund has already been determined under the document and applicable law; they are not estimates of a particular estate’s taxes or costs.
| Funds available before the charitable gift shown | 10% alternative | 25% alternative | Fixed-dollar alternative |
|---|---|---|---|
| $50,000 | $5,000 | $12,500 | $20,000 |
| $200,000 | $20,000 | $50,000 | $20,000 |
| $500,000 | $50,000 | $125,000 | $20,000 |
| $1,000,000 | $100,000 | $250,000 | $20,000 |
Compare one alternative at a time. These hypothetical figures assume debts, expenses, taxes and all other gifts have already been accounted for. They do not calculate an actual estate’s residue or establish payment priority.
A residuary gift does not guarantee that family members have been adequately provided for. Your family’s needs and any protected rights require a separate review; see the limits on giving to charity below.
Contingent gifts and final backups
A contingent gift might name a charity if an individual beneficiary does not survive under the document’s terms. Specify what happens if the charity also cannot receive the gift. One alternate beneficiary does not guarantee that every asset will avoid intestacy.
Florida has default rules for failed nonresiduary and residuary gifts (§ 732.604). Those rules may produce a different recipient from the one you would choose, so the drafting review should address both the particular gift and the residue.
What charitable bequest language looks like
When deciding how to write a bequest in a will, start with what the clause must contain. A useful charitable clause identifies the recipient by legal name and address, states the property or share, says whether the gift is restricted, and names what happens if the organization has changed, merged or closed. The five bequest examples below illustrate that structure. They are not forms, they name no real organization, and they are not a substitute for a will prepared and executed for your plan.
I give the sum of [amount] dollars ($[amount]) to [exact legal name of organization], a [state] nonprofit corporation with its principal office at [address], federal employer identification number [EIN], for its general charitable purposes.
I give [description of the asset, for example “my oil painting titled ‘[title]’ by [artist]”] to [exact legal name of organization], [address], EIN [EIN]. If I do not own that property at my death, this gift lapses and the organization takes nothing under this paragraph.
I give [number] percent ([number]%) of the residue of my estate, as defined in Article [number] of this will, to [exact legal name of organization], [address], EIN [EIN], for its general charitable purposes.
If [name of individual beneficiary] does not survive me, I give the share that [he/she] would have received to [exact legal name of organization], [address], EIN [EIN].
If at my death [exact legal name of organization] has merged with or been succeeded by another organization, I give this gift to that successor. If it no longer exists, or is not then an organization described in sections 170(c) and 2055(a) of the Internal Revenue Code, or declines the gift, I give this gift instead to [exact legal name of alternate organization], [address], EIN [EIN]. If no organization named in this paragraph can take this gift, I give it to such organization described in those sections as my personal representative selects for charitable purposes comparable to those of [exact legal name of organization].
Four cautions. First, “for its general charitable purposes” is the unrestricted form; a purpose restriction is a separate decision discussed under restrictions below. Second, the residue clause must actually define the residue the percentage refers to. Third, sample bequest language from a charity, or from an online will tool when you add a charitable bequest, can help identify the organization and its preferred terms. It does not establish that the wording fits your ownership, your family’s rights, your tax goals or your other documents. Have the whole plan reviewed before signing. Fourth, Illustration 2 deliberately gives the organization nothing if the asset is gone; a will can instead give it any sale, condemnation or insurance proceeds the law preserves.
How to identify the charity correctly
Ask the organization’s planned-giving or administrative office for its current legal name, employer identification number (EIN), mailing address and gift-acceptance instructions. Confirm whether you intend the national organization, a local chapter, a supporting foundation or a particular fund. Similar names do not establish that two entities are the same recipient.
Use a reliable contact method to verify the details. Compare the organization’s records with the IRS Tax Exempt Organization Search, which shows whether an organization is listed as eligible to receive tax-deductible contributions, its determination letter, and whether its exemption has been automatically revoked. An EIN identifies an entity; it does not by itself prove eligibility for every charitable tax deduction.
Some eligible religious organizations do not apply for IRS recognition and are not listed in the same way. An unsuccessful search therefore calls for further verification, not an automatic conclusion that the recipient is disqualified; the IRS discussion of qualified organizations is in Publication 526. A church, synagogue, mosque or temple usually has a corporate name that differs from the name on its sign; ask for the name on its articles of incorporation.
When choosing a charity for a legacy gift, check these three situations:
- Local chapter or national organization. Many national charities have affiliates with their own EINs, and a hospital or university usually receives gifts through a separate foundation. Decide which entity you mean, and name that one. If you want the gift used locally, say so in the restriction rather than by guessing at the right entity.
- Informal groups. Can a non-legal entity be named as a beneficiary in a will? A scholarship committee, a parents’ club or a neighborhood group that is not an incorporated entity may be unable to take title to a gift. If the cause matters to you, name an incorporated organization that will carry it out, or a community foundation fund established for that purpose.
- State registration and tax status. A charity that solicits in Florida generally registers with the Florida Department of Agriculture and Consumer Services under the Solicitation of Contributions Act (chapter 496, Florida Statutes); the department’s Check-A-Charity lookup and its consumer line, 1-800-HELP-FLA, show registration and financial filings. Registration is not the same as federal tax qualification, and neither is the same as the organization’s willingness to accept a particular gift.
No real charity’s legal name or tax status should be guessed from its advertising name. Keep the verified identification with your planning records and revisit it when you update the documents.
Restricted or unrestricted?
Can I leave everything to a charity in my will? The amount you may leave is subject to the family protections, claims and other limits discussed below. Whether you restrict the charity’s use of the gift is a separate decision. An unrestricted gift permits the recipient to use the funds for its charitable work within its governing terms. A restricted gift identifies a purpose, such as a scholarship or a program, and should be discussed with the organization before you sign.
Can you choose exactly how the gift is used? Within what the organization will accept, yes. Ask whether the program exists, whether the charity will accept the restriction, whether a minimum applies, and how administrative costs will be handled. A restriction that is too narrow may become impractical: a named program might close even though the organization continues operating. An endowment gift supports continuing charitable work under spending restrictions. Ask about the organization’s minimum funding level and gift agreement.
Discuss a fallback purpose, an alternate charity, or carefully defined authority to select a comparable use. Decide who can make that decision and under what conditions. A letter describing your wishes should not accidentally contradict binding terms in the will, trust or gift agreement.
For a charitable trust, Florida’s cy pres statute permits a court to modify or terminate the trust when a charitable purpose becomes unlawful, impracticable, impossible or wasteful, directing the property consistently with the settlor’s charitable purposes (§ 736.0413; see also § 736.0405 on charitable purposes). Courts apply the same idea to outright gifts in wills only when the will shows a general charitable intent and names no workable alternative, so it is a fallback, not a plan.
What if the charity no longer exists when you die?
The answer depends on what happened to the organization and on what the will says. A name change leaves the same organization in place, and when a charity merges into another nonprofit the surviving organization usually takes the gift automatically by law. A charity that has dissolved, lost its tax-exempt status or refused the gift leaves a question the will should answer in advance, because Florida’s default rules for a failed gift, or a court applying the cy pres doctrine, may send the money somewhere you would not choose.
| What happened | What usually follows | What the will can provide |
|---|---|---|
| The charity changed its name | The same entity still exists; the gift reaches it once identity is shown, often by the EIN and corporate records. | Identify the organization by legal name, address and EIN so a later name does not create doubt. |
| The charity merged into another organization | When the named charity has merged into another nonprofit, the surviving organization usually takes the gift automatically by law, even without a successor clause; proof of the merger may still be required (§ 617.1106). | A successor clause still helps: it confirms your intent and covers successions that are not formal mergers. |
| The charity dissolved and nothing succeeded it | An outright gift can fail. Florida’s default rules for a failed devise then apply (§ 732.604); a failed nonresiduary gift generally falls into the residue, and a failed residuary share passes to the other residuary beneficiaries. If the will shows a general charitable intent and names no workable alternative, a court may instead apply the cy pres doctrine and redirect the gift to a similar charity. | Name an alternate organization, or give the personal representative defined authority to select an organization with a comparable purpose. |
| The charity lost its federal tax-exempt status | The entity may still exist and still be able to take the gift, but an estate-tax deduction may be unavailable and your purpose may not be served. | Condition the gift on the organization being described in the Internal Revenue Code sections that govern deductibility, with an alternate recipient. |
| The charity declines the gift | Organizations refuse gifts that carry unwanted restrictions, liabilities or carrying costs, such as some real estate. | An alternate recipient and, for property, authority to sell and give the proceeds instead. |
| A restricted program ended | The organization continues but the stated purpose cannot be carried out. | A broader related purpose, or an alternate charity, chosen by you now rather than litigated later. |
Two further points. If a charity named in your will has dissolved, merged, or stopped qualifying, a Florida court may apply the cy pres doctrine to redirect the gift to a similar charity — but only if your will shows a general charitable intent and does not already name a workable alternative (Christian Herald Ass’n v. First Nat’l Bank of Tampa, 40 So. 2d 563 (Fla. 1949); SPCA Wildlife Care Ctr. v. Abraham, 75 So. 3d 1271 (Fla. 4th DCA 2011)). And do not assume that your personal representative can pick any charity they prefer: a personal representative distributes what the will directs, and a choice the will did not authorize invites an objection from the other beneficiaries. Your will can instead authorize your personal representative to choose a comparable charity; that authority is valid but is limited by your stated charitable purpose.
The practical answer is drafting: identify the organization precisely, add a successor sentence, name an alternate, and review the plan when you hear that a charity you have named is merging, rebranding or closing. The illustrations above show where that sentence goes.
Can you leave everything to charity in Florida?
How much can you leave to charity in your will? You can name a charity as the sole or principal beneficiary, leaving everything by will to charity, but some property and some people have rights the will cannot override. A surviving spouse’s elective share, the restrictions on devising a Florida homestead, the claims of creditors and the costs of administration all come ahead of a gift to charity, and the abatement rules decide which gifts are reduced first when the estate is short.
- A surviving spouse. Florida gives a surviving spouse the right (§ 732.201) to elect a 30 percent share of the elective estate (§ 732.2065), which reaches many assets outside probate, unless that right was validly waived (§ 732.702). A plan that leaves everything to charity does not defeat that election; it invites it. The details are in the Florida elective share guide.
- The homestead. If you are survived by a spouse or a minor child, Florida restricts how your homestead can be devised (§ 732.4015). A gift of your homestead to a charity does not work if you leave a spouse or minor child; the home passes to your spouse and descendants by law instead (§ 732.401). The rules differ for a home held in a trust or titled with another person.
- A spouse married, or a child born or adopted, after the will. Florida’s pretermitted-spouse and pretermitted-child provisions can give such a person a share the will did not mention (§ 732.301; § 732.302). A will that was signed before a marriage or a birth should be reviewed, not assumed to stand.
- Creditors and expenses. Valid claims, the family allowance, exempt property and the costs of administration are paid before beneficiaries receive distributions. Gifts are reduced in the statutory abatement order (§ 733.805), unless the will directs otherwise: residuary gifts abate first, then fixed-dollar (general) gifts, and specific gifts last — so a charity named in the residue bears shortfalls before a charity given a specific devise.
- Penalty clauses. A clause that penalizes a beneficiary for contesting the will is unenforceable in Florida (§ 732.517), so it cannot be used to protect a charitable gift from a challenge. What protects the gift is a properly executed, clearly drafted will and a plan the family understands; see contesting a will in Florida for the grounds a challenger must prove.
How much can I leave to charity, then? Within those limits there is no cap on how much of your estate you may leave to charity, and no requirement that family receive any share, apart from the rights above. How much to leave is a personal decision; the drafting question is whether the gift is expressed as a fixed sum, a share of the residue or a contingent gift, and what remains for the people you also intend to provide for.
Plan for changes before they become problems
A gift drafted for your circumstances today may need updating as those circumstances change. The table lists changes to review and the question the plan should answer for each.
| Change | Question to resolve in the plan |
|---|---|
| The charity merges or changes its name | Should a verified legal successor receive the gift? How will that successor be identified? |
| The charity closes, loses its qualification or refuses the gift | Which alternate recipient or authorized selection process applies? |
| A restricted program ends | Is a broader related purpose allowed, or should another charity receive it? |
| You sell, give away or replace the designated asset | Should the charity receive a substitute or nothing? Have the statutory exceptions in § 732.606 been considered? |
| The estate lacks enough assets | How do the document, debts, expenses, tax allocation and the abatement rules affect each gift? |
| Marriage, divorce, a birth or a beneficiary’s death changes the family | Do the gift, the residue and the protected-family-rights analysis need revision? |
| An account is moved to a new institution | Did the beneficiary designation carry over, or must it be submitted again? |
Do not assume a charity automatically takes ahead of creditors or a spouse’s protected rights. Florida’s homestead devise restrictions and elective-share rights can affect the plan (§ 732.4015; § 732.201), and a proposed gift of your home needs particular review if you have a spouse or a minor child.
Cash, securities, real estate and personal belongings
Cash is not the only option. Securities, real estate, artwork and other property may be suitable, but acceptance and administration matter. Ask the charity about brokerage transfer procedures, appraisals, storage, sale policies and any minimum gift size before you name an item.
Can you leave your house to a charity?
People ask whether they can donate a house to charity by will, or leave a vacation home to a cause. Potentially, in the right circumstances. Review four things first: whether the property is your Florida homestead and whether you have a spouse or a minor child (§ 732.4015); the title, including any co-owner with survivorship rights; the mortgage, taxes, insurance and carrying costs the estate will pay until the property is transferred or sold; and whether the organization will take the property in kind or prefers that the personal representative sell it and distribute the proceeds. A vacation home is not automatically easy to donate, and many organizations decline real estate that carries environmental, association or maintenance obligations. The will should say who may sell, which expenses are charged to the gift, and what the recipient is meant to receive. A lifetime alternative, such as a deed that reserves a life estate, is a different transaction with its own tax and homestead consequences; the guide to Florida deeds explains the forms, and whether a particular deed may name a charity is a question for the planning review.
Securities and accounts
Publicly traded securities are usually transferred by the personal representative to the charity’s brokerage account, or sold and distributed as cash, depending on the will and the organization’s policy. Ask for the charity’s transfer instructions and its account details in advance, and keep them with the plan. An account with a payable-on-death or transfer-on-death designation passes under that designation, not under the will; see account designations below.
Personal belongings and the separate writing
Florida allows a will-referenced, signed separate writing to dispose of eligible tangible personal property not otherwise specifically disposed of by the will, excluding property used in trade or business (§ 732.515). The items and recipients must be described with reasonable certainty. This limited mechanism is convenient for a painting or a collection intended for a museum or a school, but it is not a substitute for drafting gifts of money, accounts or land in the will itself. See specific bequests of tangible property for the details.
Naming a charity on a retirement account or insurance policy
An account designation can be an appropriate way to make a gift at death, but it uses the account’s rules, not the will’s. Request the current form, identify the correct legal entity, check primary and contingent beneficiaries, confirm how percentages are entered, and obtain the institution’s acknowledgment that the instruction is on record.
| Account type | What to confirm | Why it matters |
|---|---|---|
| Traditional IRA | The custodian accepts an organization as beneficiary; how shares among a charity and individual co-beneficiaries are entered; the charity’s legal name and EIN on the form. | Pre-tax dollars left to an individual are taxed as that person receives them; a qualified charity generally pays no income tax on what it receives. Co-beneficiaries can be affected by how the account is divided after death. |
| 401(k) or other employer plan | Whether a spouse must consent in writing; whether the plan permits an organization as beneficiary; the plan’s payout rules. | An IRA and an employer plan are not interchangeable; plan rules and federal spousal-consent requirements can override a form that was completed without them. |
| Life insurance | Whether you are changing the death-benefit beneficiary or transferring ownership of the policy; whether an assignment or restriction limits changes. | Changing the beneficiary is revocable and affects the death benefit; transferring ownership during life is a different gift with different consequences. |
| Bank or brokerage POD or TOD | That the institution permits an organization as the payee and has recorded it; what happens if the organization no longer exists. | A POD or TOD designation passes outside the will to a beneficiary that survives the owner (§ 711.509); but if the named organization has dissolved before death, check whether another effective beneficiary or successor can take under the account’s terms and applicable law. If no beneficiary survives the sole owner or last surviving owner, the asset generally belongs to that owner’s estate and passes under the will or intestacy rules (§ 655.82(3); § 711.507). |
Naming a charity as beneficiary of an IRA is the usual way of leaving an IRA to charity; a will clause does not do it. Naming your estate or a trust as beneficiary, and then leaving the money to charity through that document, can produce different results from naming the charity directly, including differences in timing, in who pays income tax on the distributions, and in whether the gift is reduced by expenses and claims. Avoid withdrawing funds or changing beneficiaries on the assumption that every route has the same tax result; the beneficiary-designation guide explains the broader coordination issues.
Giving from an IRA during life versus naming the charity at death
A qualified charitable distribution, or QCD, is a lifetime gift: a direct transfer from an IRA to an eligible charity that the IRS excludes from the owner’s gross income, within an annual limit, once the owner has reached age 70½. Naming the charity as the account’s beneficiary is a gift at death. They are different tools, and neither is a bequest in a will.
The IRS describes the QCD rules in Publication 590-B: the owner must be at least 70½ when the distribution is made; the IRA trustee must pay the organization directly; the amount is excluded from income rather than deducted; it counts toward the owner’s required minimum distribution (RMD) for the year once distributions are required, which is why people describe it as giving an RMD to charity; and the annual cap is set by the IRS and adjusted over time, with a separate one-time election for certain split-interest arrangements. Not every charitable recipient qualifies for a QCD; the organization must be eligible to receive tax-deductible contributions, and a tax adviser should confirm the recipient and the reporting before the transfer is made.
The disadvantages of a QCD are the ones built into the rules: the age requirement, the annual cap, the exclusion of some recipients, and the fact that money sent to charity is not available for other needs; whether it fits is a question for your tax adviser. Why does this belong on a page about wills? Because a plan can combine lifetime QCDs, a beneficiary designation naming the charity for whatever remains in the IRA, and will provisions for probate assets. Which combination fits depends on your age, your other income, your family and the size of the account. The point of raising it here is that a will clause giving “my IRA to charity” usually accomplishes nothing, because the account passes under its own form.
Taxes: which taxpayer, which deduction
Writing a revocable charitable bequest into your will does not complete a donation during life and does not, by itself, create a current personal income-tax deduction. Florida imposes no estate or inheritance tax: there is no Florida estate tax and no Florida inheritance tax. The “charitable bequest tax deduction” people search for is really three separate deductions, each belonging to a different taxpayer and tax return, so “will a charitable gift in my will lower my taxes?” depends on which one you mean. A revocable bequest itself produces no lifetime income-tax deduction; each deduction has its own taxpayer and its own conditions.
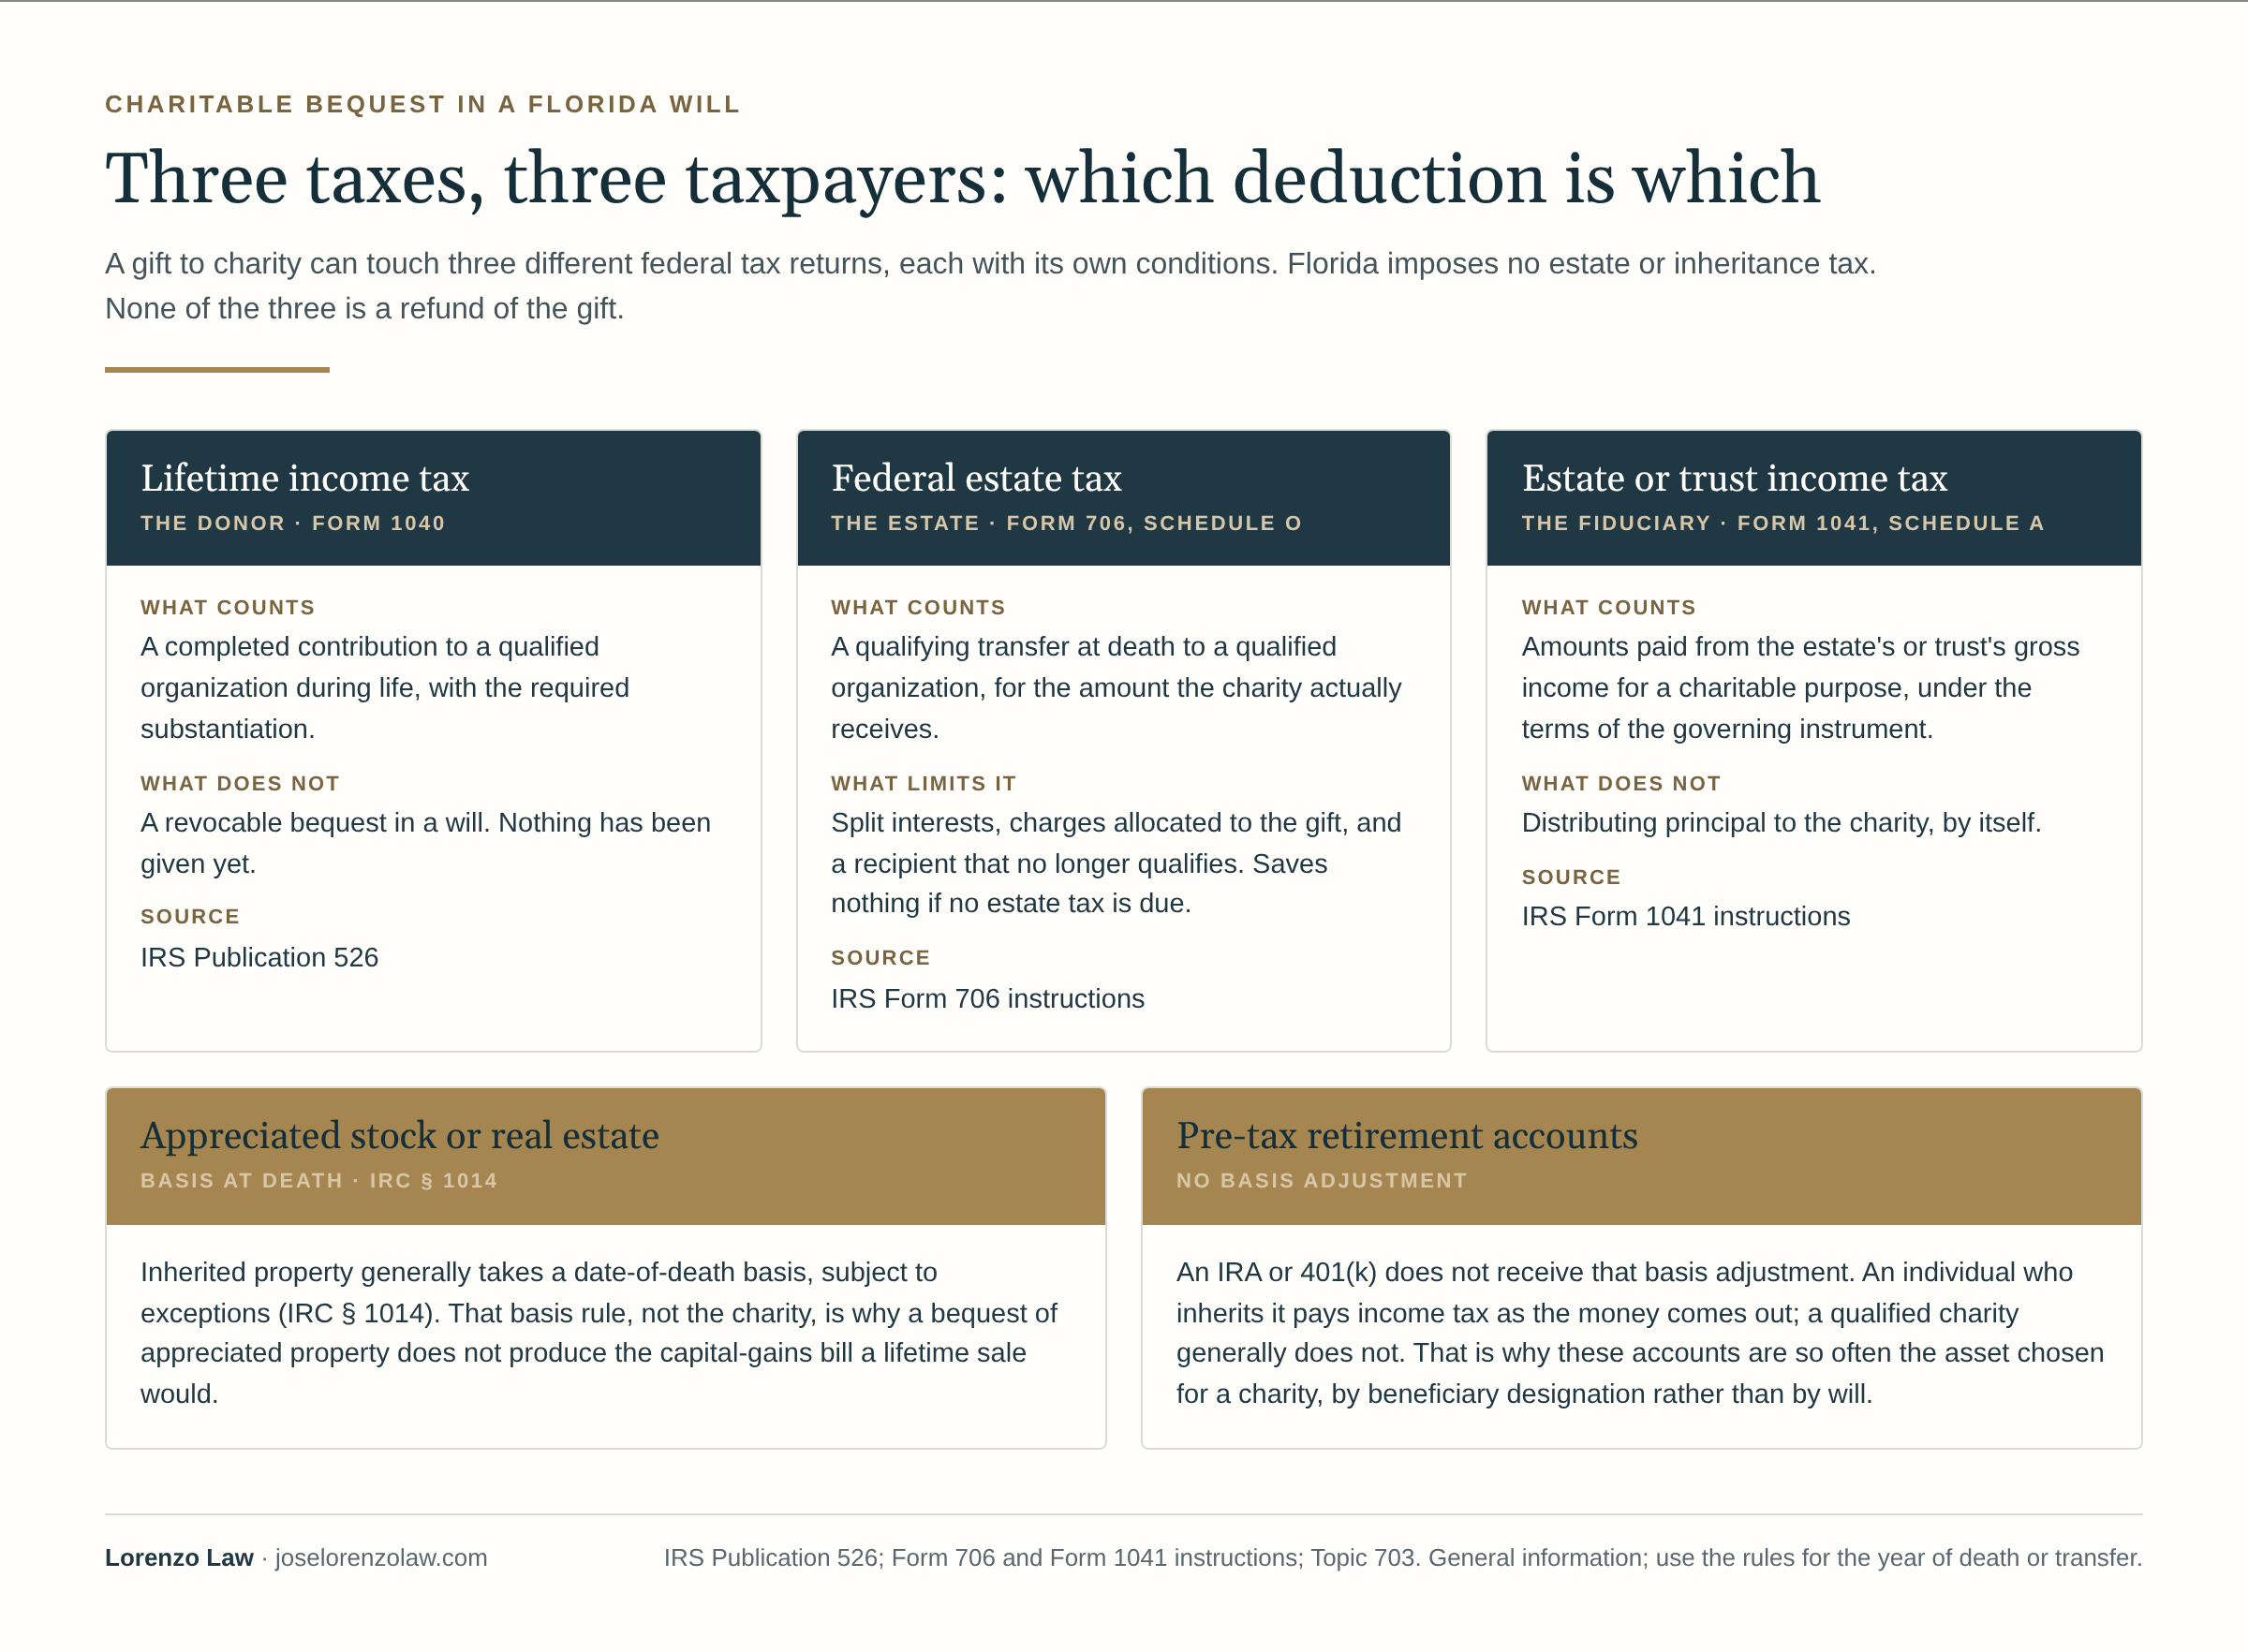
See the chart “Three taxes, three taxpayers: which deduction is which” (opens the full-size image; the details are also in the text).
| Tax question | Relevant distinction |
|---|---|
| Your lifetime income tax | Completed qualifying contributions have their own eligibility, substantiation and deduction rules (IRS Publication 526). A future revocable bequest is different. |
| Federal estate tax | Qualifying transfers can support an estate-tax charitable deduction, reported on Form 706, Schedule O. Qualification of the recipient, the interest that passes, and the amount actually available to the charity all matter. |
| Estate or trust income tax | A separate deduction may apply to qualifying payments made from gross income under the terms of the governing instrument (Form 1041, Schedule A). Distributing principal is not automatically deductible on this basis. |
| Capital gains or retirement income | Asset type, basis, the recipient, sale timing and the distribution route affect the analysis. A charitable intention alone does not eliminate these taxes. |
Do charitable bequests reduce estate tax? Only an estate that owes federal estate tax in the first place. Are charitable bequests deductible on Form 706 or on Form 1041? They are different deductions with different conditions, and a gift may qualify for one, both or neither. The federal estate-tax deduction is not a dollar-for-dollar refund. It reduces the taxable estate, so it saves nothing if no estate tax would otherwise be due, which is the position of most Florida estates under the current federal exclusion. A transfer split between charitable and noncharitable interests requires special attention; not every arrangement qualifies. Taxes or other charges allocated to a charitable gift can also reduce the deductible amount. See the IRS Form 706 instructions, Schedule O, and the Form 1041 instructions, Schedule A. Use the rules for the year of the transaction or death; this page does not promise a particular deduction.
Appreciated property also needs its own analysis. Inherited property generally takes a basis determined by reference to its value at the date of death, subject to exceptions (IRS Topic 703). That is different from the treatment of a lifetime transfer, and it means a bequest of appreciated stock does not “avoid” a capital-gains bill that a sale during life would have produced; the basis rule, not the charity, is what changes the result. Pre-tax retirement accounts are the exception that matters most: they do not receive that basis adjustment, which is why they are so often the asset chosen for a charity.
For the broader distinctions among inheritance tax, federal estate tax, inherited retirement income and capital gains, read Florida inheritance taxes and the taxes heirs may owe.
Donor-advised funds, charitable trusts and gift annuities
These arrangements are not bequests, but they often appear in the same plan, and people reasonably ask how a donor-advised fund or a charitable trust compares with a gift in a will. A revocable bequest does not transfer the gift during life, although preparing or updating the plan may involve fees. A donor-advised fund can receive lifetime contributions or a gift at death; a charitable trust can be established during life or under a will. The governing arrangement determines when ownership and control change. A donor-advised fund is an account at a sponsoring charity; a charitable remainder trust and a charitable lead trust split the benefit between people and charity over time; a charitable gift annuity is a contract with a charity. Each has its own rules, and each can be named in, or coordinated with, a will.
Donor-advised funds
A donor-advised fund is a separately identified fund maintained by a sponsoring organization that is itself a public charity. After a contribution, the sponsoring organization has legal control of the assets; the donor keeps advisory privileges over grants and investments (IRS donor-advised fund guidance). Two questions arise at death. First, who succeeds to the advisory role: most sponsors let you name a successor advisor, or direct that the remaining balance be granted to named charities, on the sponsor’s own form. Second, how to make a bequest to a donor-advised fund by will or beneficiary designation: the recipient is the sponsoring organization, identified by its legal name and EIN, “for the [name] Fund,” using the sponsor’s recipient instructions rather than a fund nickname. Florida community foundations and national sponsors both offer these funds; the mechanics differ by sponsor.
Charitable remainder and charitable lead trusts
A charitable remainder trust is an irrevocable arrangement that pays one or more noncharitable beneficiaries for life or a term of years, after which the remainder passes to charity. It has qualification, valuation, payout and reporting requirements, and the payments to the beneficiaries can carry taxable income; a qualifying contribution may produce a partial deduction, not a blanket exemption from capital-gains tax (IRS charitable remainder trust guidance). A charitable lead trust reverses the order: the charity receives payments first and the remainder passes to family. A charitable remainder trust takes one of two forms, a charitable remainder annuity trust (CRAT) or a charitable remainder unitrust (CRUT). Either kind can be created during life or, as a testamentary charitable remainder trust, by a will that takes effect at death; the drafting and the tax analysis call for an attorney and a tax adviser who handle these trusts regularly. For Palm Beach County families, see charitable planning in Palm Beach County.
Charitable gift annuities
A charitable gift annuity involves a transfer to a charity in exchange for its contractual promise to pay you, or you and another person, for life. It is different from leaving a future gift in a will. Review the contract, the charity’s financial obligation and the applicable tax treatment with qualified advisers before committing funds.
These options may require separate legal and tax advice. Their discussion here is not an offer of a particular charitable-trust, investment, annuity or tax-return service. The scope of any Lorenzo Law engagement is agreed in writing.
How to add or change a charitable bequest
How to include a charity in your will depends first on whether you are changing a will or an account designation. For a will that already exists, use a codicil or a new will, signed with the same formalities as the original; a handwritten note, an email or a downloaded clause is not an amendment. The steps for updating a will to add a charity appear below. Changing a charity named on an account means a new form filed with that institution. The six steps below cover both.
- Gather the existing plan. Bring the will, codicils, trust amendments, relevant titles and current beneficiary confirmations.
- Describe the gift and the recipient. Identify the amount, asset or percentage; the intended organization by legal name, address and EIN; any restriction; and the backup.
- Coordinate the documents. Check that the intended asset is governed by the document being changed, and that duplicate or conflicting gifts are addressed.
- Execute the correct amendment or new document. A codicil may be suitable for one added gift, but substantial changes are usually clearer in a replacement will. Trust amendments follow the trust and applicable law (§ 736.0602).
- Complete institution-specific changes. A signed will does not submit a new account beneficiary form.
- Keep records and review on change. Tell the appropriate person where the original documents and current confirmations can be found. Revisit the plan after a material family, asset or charity change.
Under Florida’s ordinary will-execution rule, the will must be in writing and signed at the end by the testator, or by another person in the testator’s presence and at the testator’s direction. The signing or acknowledgment must occur before at least two attesting witnesses, who sign in the presence of the testator and of each other. A codicil uses the same formalities (§ 732.502).
A notary alone does not replace the witnesses. A self-proving affidavit serves a separate evidentiary function that makes the will easier to admit to probate (§ 732.503). An electronic will accomplishes these same steps electronically — it is signed and witnessed with electronic signatures, and the witnesses may appear remotely by live audio-video technology through an online notarization rather than in the room (§§ 732.521–732.525; § 117.285). Remote will signing by online notarization is offered for wills prepared by the firm.
What happens to the gift after death
A charitable bequest in a will is paid through Florida probate. The personal representative is appointed, gives notice, inventories and values the assets (§ 733.604), handles creditors’ claims, and then distributes the gifts the will directs — though it is not required to distribute until five months after letters issue (§ 733.801) — usually obtaining a receipt from each beneficiary. A charity named in a will is a beneficiary with the same standing as any other, and it can be months before a gift is paid.
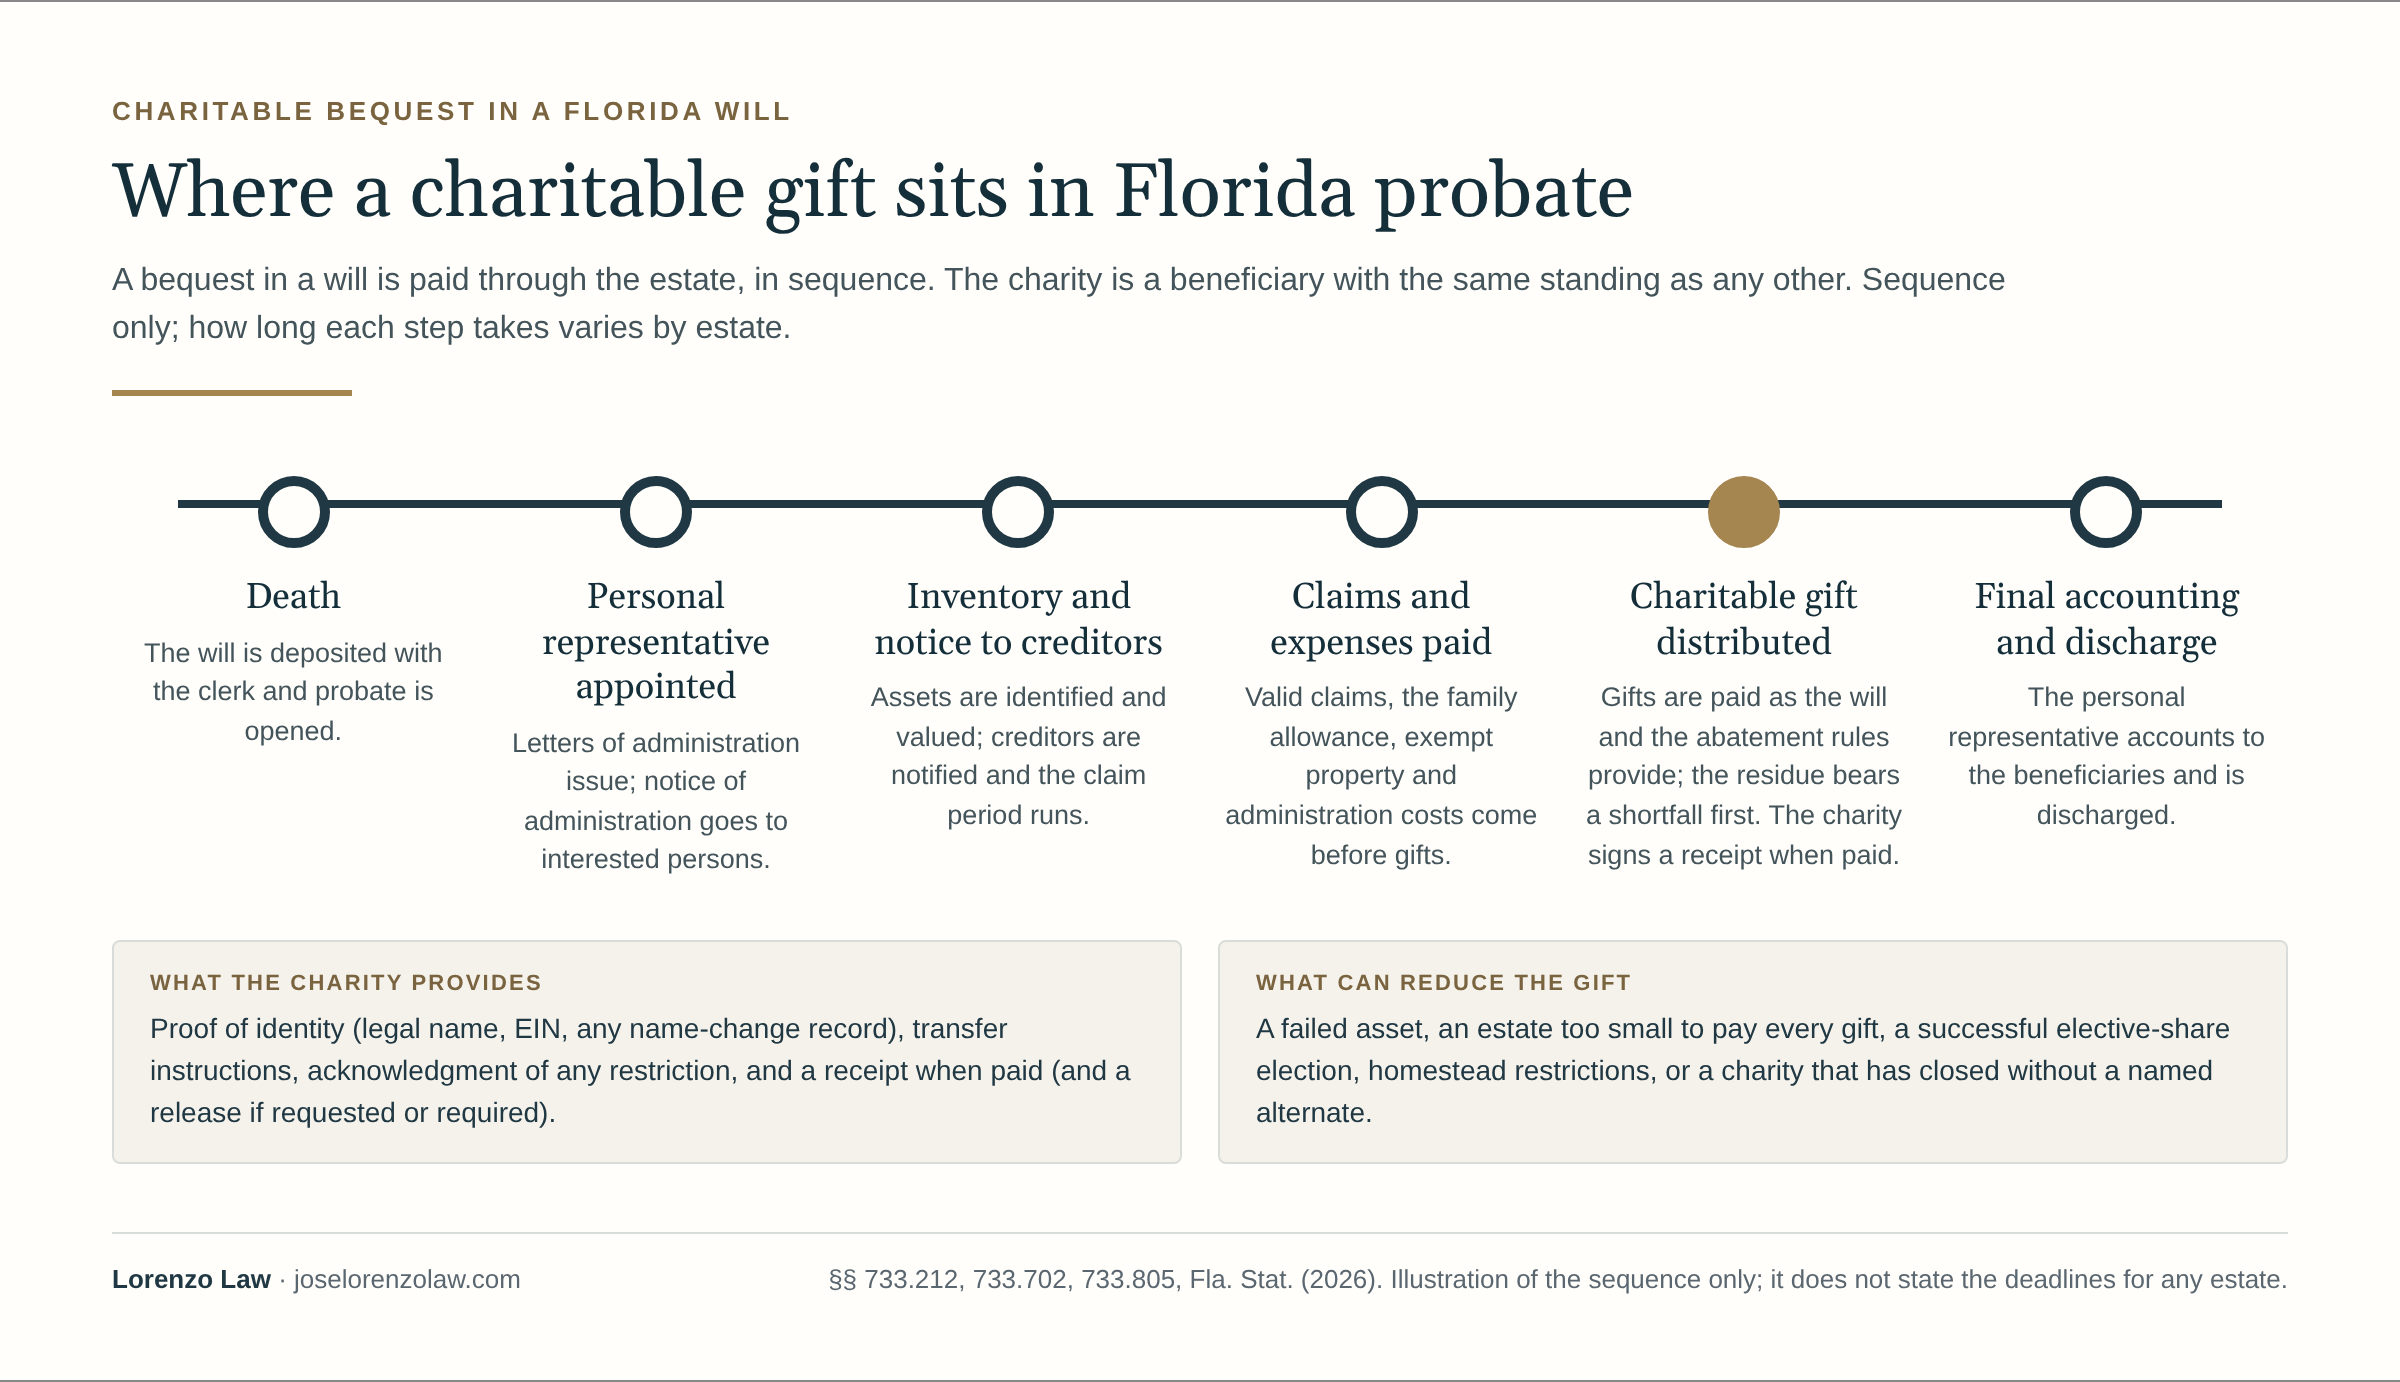
See the chart “Where a charitable gift sits in Florida probate” (opens the full-size image; the details are also in the text).
What the charity needs to provide
The paperwork and documentation a charity needs to claim an estate gift are modest. Organizations with planned-giving staff handle estate gifts routinely. The personal representative will typically ask the charity for proof that it is the organization named (its legal name, EIN and, if the name has changed, the corporate record showing the change), its tax-exemption letter if a deduction will be claimed, wiring or transfer instructions, and a signed receipt when the gift is paid. A receipt and release may be requested or required in a particular matter. If the gift is restricted, the charity may be asked to acknowledge the restriction in writing. The charity, in turn, is entitled to information about the administration as a beneficiary, and it may object if the estate is administered in a way that reduces its gift.
Unpaid pledges
If you have signed a pledge to a charity and die before paying it, the estate and the charity may disagree about whether the balance is a debt the estate must pay or a promise that ended at death. A charity usually cannot collect an unpaid pledge from a Florida estate unless the pledge named the specific purpose for the money and the charity actually relied on it in a substantial way (Mount Sinai Hosp. of Greater Miami, Inc. v. Jordan, 290 So. 2d 484 (Fla. 1974)). Even an enforceable pledge is lost if the charity does not file a timely creditor claim in the probate (generally the later of 3 months after the first publication of the notice to creditors or 30 days after service, and in no event more than 2 years after death) (§ 733.702; § 733.710). The planning answer is to record each outstanding pledge and say in the will whether a bequest to that organization satisfies the pledge or is in addition to it. For how creditor claims work generally, see what happens to your debt when you die.
Can a charity serve as your personal representative?
In Florida the executor of a will is called the personal representative, so the question is whether a charity can be executor of a will. A charity cannot serve as your personal representative: Florida allows only a Florida trust company or a bank with trust powers to act as a corporate personal representative (§§ 733.302–733.305). Name an individual or an authorized institution instead, and let the charity be what it is: a beneficiary.
A personal representative who wants to make a charitable gift the will does not direct faces the mirror-image problem: the personal representative distributes the estate as the will and the law provide, and a gift the will did not authorize can be charged back to the personal representative by the beneficiaries who should have received it.
A private charitable gift planning worksheet
Use this worksheet privately before a planning meeting. It records decisions, not legal instructions. Do not put account numbers, Social Security numbers, balances, passwords or copies of signed documents into a public comment or a general inquiry form. Use general asset descriptions at the initial inquiry and arrange a suitable method for sharing documents.
| Asset or gift | Governing document to verify | Recipient to confirm | Backup instruction to discuss |
|---|---|---|---|
| Example: a percentage of the probate residue | Will and codicils | Exact legal charitable entity, address and EIN | Alternate charity if the first cannot receive the gift |
| Example: part of a retirement account | Provider’s accepted designation | Charity accepted by the provider | Contingent recipient under the provider’s rules |
| Example: a painting | Will or an eligible will-referenced list | Organization willing to accept the item | What should happen if the painting is sold |
| Your proposed gift: ______ | ______ | ______ | ______ |
| Your proposed gift: ______ | ______ | ______ | ______ |
For each gift, also note: whether the gift is restricted; whether the organization has confirmed acceptance; when its identifying information was checked and by what method; whether the gift satisfies or adds to any pledge; which other documents might duplicate or conflict with it; and the next event that should trigger a review. For multiple charities, keep the percentages and alternatives in one private working list so inconsistencies are easier to spot.
Questions readers ask about leaving money to charity in a Florida will
How do I leave a gift to charity in my will?
Whether you want to include your favorite nonprofit organization in your will or several charities, the steps are the same. Decide what the gift is (a sum, an asset, a percentage of the residue, or a contingent share); confirm the organization’s exact legal name, address and EIN with the organization and the IRS search; decide whether the gift is restricted; name a successor and an alternate; check that the asset passes under the will rather than an account form; and sign the will or codicil with two attesting witnesses as Florida requires. The sections above take each step in turn.
Can I leave gifts to more than one charity?
Yes. Identify each recipient by legal name, address and EIN, and give each a clear amount, asset or share. Reconcile the total allocation so the whole intended fund is disposed of, and name a backup for each gift that could fail. If the charities appear in different documents, such as a will and an account form, review the combined effect instead of treating each form in isolation.
Can I change my mind after naming a charity in my will?
An ordinary revocable will can be changed while you have the required capacity, by a codicil or a new will signed with Florida’s formalities. A completed lifetime gift, an irrevocable trust, a contract to make a will or a binding pledge may have different consequences, so review those arrangements before assuming the property can be recovered.
Does a charitable bequest avoid probate?
No. A bequest in a will is paid through probate. A properly funded trust or an effective beneficiary designation may transfer an asset outside probate, but the asset’s ownership and the document’s terms must support that result, and those routes do not eliminate every claim, tax or administrative obligation.
Is a charitable gift in a will tax deductible now?
Merely signing a revocable bequest does not create a current personal income-tax deduction. At death, a qualifying gift may support a federal estate-tax deduction, and an estate or trust may have a separate income-tax deduction for qualifying payments; each has different requirements. Review the actual transfer and the taxpayer rather than assuming the same deduction applies to all three.
What is the difference between a bequest and a beneficiary designation?
A bequest is a gift made in a will and paid through probate, after debts, expenses and protected rights. A beneficiary designation is an instruction filed with an institution for one account or policy; it pays the named person or organization directly, outside the will, and the will generally cannot change it. Many plans use both: the will for probate assets, designations for retirement accounts and insurance.
What happens if the charity no longer exists when I die?
It depends on what happened to the organization and on the will. A name change leaves the same organization in place, and a charity that merged into another nonprofit is usually succeeded by the survivor automatically. If the charity dissolved and the will names no alternate, a court may redirect the gift to a similar charity only if the will shows a general charitable intent; otherwise the gift fails and passes under Florida’s default rules, usually into the residue. Name an alternate yourself rather than rely on either outcome.
Is there a limit on how much I can leave to charity in Florida?
Can I leave everything to a charity in my will? Yes, subject to rights that come first: a surviving spouse’s elective share, the restrictions on devising a homestead when a spouse or minor child survives, the claims of creditors, the costs of administration, and the rights of a spouse married or a child born after the will was signed. Within those limits you may leave as much of your estate to charity as you choose.
Can I leave my house or a vacation property to a charity?
Potentially, after reviewing title, any homestead restrictions, the mortgage and carrying costs, and the organization’s willingness to accept real estate. Decide whether the gift is the property itself or the sale proceeds, who bears the costs until transfer, and what happens if the charity declines. For many organizations a cash gift is more practical than a house.
Can I leave money to my church or to a local chapter instead of the national organization?
Yes, if you name the right entity. Leaving money to a church in a will works the same way as any other charitable gift: a congregation usually has a corporate name that differs from its everyday name, and a local chapter or affiliate often has its own EIN separate from the national organization. Ask the organization which entity should be named and confirm it before signing; if you want the gift used locally, say so in the restriction as well.
Will the charity receive the exact amount I name?
Not necessarily. Available assets, enforceable claims, the costs of administration, the document’s terms and Florida’s abatement rules can reduce a gift. A fixed amount states your intended gift; it does not guarantee that enough will remain to pay it in full.
Should I tell the charity and my family?
Notifying the charity of a legacy gift in your will is a letter or a call to its planned-giving office; there is no required form. Telling the charity lets it confirm acceptance, its legal name and any restriction, and most organizations record the intention without any obligation on your part. Whether to discuss personal provisions with family depends on your circumstances; a conversation can reduce surprise but does not prevent a dispute, and notice is never a substitute for a properly executed document.
What paperwork does a charity need to claim a gift from my estate?
Prove that it is the organization named, usually with its legal name, EIN and any record of a name change; supply transfer instructions; acknowledge any restriction; and sign a receipt when the personal representative pays the gift. A release may also be requested or required. If a deduction will be claimed, the estate may also ask for the organization’s tax-exemption letter. The charity may ask the personal representative for information about the administration as a beneficiary.
Can a charity be the personal representative of my Florida will?
No. A charity itself cannot serve as your personal representative in Florida — only a qualified individual or a bank or trust company with Florida fiduciary powers may (§§ 733.302–733.305). Name an individual or an authorized institution as personal representative and let the charity be a beneficiary.
Can my personal representative donate to charity if my will does not say so?
Not on the personal representative’s own initiative. A personal representative distributes the estate as the will and Florida law direct; a gift the will did not authorize is a distribution to the wrong person, and the beneficiaries who should have received it can hold the personal representative responsible. If you want a charitable gift made, put it in the will.
Can a charity refuse my gift?
Yes. Any beneficiary, including a charity, may disclaim a bequest (ch. 739), and organizations decline gifts that carry restrictions they cannot honor, real estate with liabilities, or items they cannot use or sell. What happens next depends on the will, the reason for refusal and applicable law. Review any alternate recipient or authority to sell the property and give the proceeds. If the gift fails, Florida’s default rules distinguish nonresiduary gifts from residuary shares (§ 732.604). Cy pres may apply where the will shows general charitable intent and names no workable alternative. Confirm acceptance before signing.
What is a qualified charitable distribution, and is it the same as a bequest?
No. A qualified charitable distribution is a lifetime transfer paid directly from an IRA to an eligible charity by an owner who is at least 70½; the IRS excludes it from income within an annual limit and it counts toward the required minimum distribution. A bequest is a gift at death through a will. Leaving an IRA to charity at death is done by beneficiary designation, not by a will clause.
Does Florida tax a gift to charity in a will?
No. Are bequests taxable in Florida, and do you pay inheritance tax on money left to charity? Florida has no estate tax and no inheritance tax, so neither the estate nor the charity pays a Florida tax on the gift. The questions that remain are federal: whether the estate owes federal estate tax at all, whether the gift qualifies for the estate-tax charitable deduction, and how income earned by the estate or paid from a retirement account is taxed. Florida inheritance taxes and the taxes heirs may owe are explained in a separate guide.
Will a trust keep the gift completely private?
A funded revocable trust can reduce reliance on probate filings for the property it actually owns, but complete secrecy is not assured. Beneficiary disclosures, trust administration, litigation or other legal requirements may reveal information. Treat privacy as one planning factor rather than an assured result. If you do not want the gift publicly acknowledged, tell the organization; most will honor a request for anonymity in their donor lists and legacy society.
How do I include my favorite nonprofit organization in my will?
Ask the organization for its exact legal name, address and EIN, confirm them against the IRS Tax Exempt Organization Search, decide the amount, asset or share, and have the gift written into a will or codicil signed with Florida’s formalities. If the organization is a national charity with local chapters, or a hospital or university with a separate foundation, name the entity you actually mean, and add a successor and an alternate in case it changes.
Can I leave part of my estate to both family and charities?
Yes. One possible arrangement is specific or fixed-dollar gifts to individuals, a percentage of the residue to one or more charities, and the balance of the residue to family, or the reverse. The drafting questions are which gifts should bear a shortfall first under Florida’s abatement rules, what happens if a family beneficiary or a charity cannot take, and whether a spouse’s or minor child’s protected rights change the arithmetic.
Should I leave a specific amount or a percentage of my estate to a charity?
A fixed amount states the gift you intend today but is paid in full while assets last, so it takes a larger share of a shrunken estate. A percentage of the residue rises and falls with what remains, which keeps the balance between charity and family roughly where you set it. Many wills use a modest fixed gift for a charity that should receive something regardless, and a percentage for the rest; the chart in the gift-structures section shows how the two behave.
What types of assets can I leave to charity through a will?
Anything that passes through your probate estate: cash, securities held in your own name, real estate that is not restricted homestead, vehicles, artwork, collections and other tangible property. Accounts with beneficiary designations, jointly owned property with survivorship rights and property already in a trust pass under their own documents, so a gift of those assets is made on the account form or in the trust, not in the will. Ask the charity before naming property it may be unable to use or sell.
Are there minimum amounts for a charitable gift in a will?
Florida law sets none. Organizations do: an endowed or named fund usually requires a minimum, and some will not accept real estate or tangible items below a value that covers their costs. Ask whether the organization accepts unrestricted gifts of the size you intend. Confirm any minimum with the organization before writing a restriction into the will.
Can I leave a gift in my will to an organization that is not a 501(c)(3)?
A will can name an organization that is not tax-exempt. The gift is valid if the organization can legally take title; an informal club or association often cannot in its own name, in which case a charitable gift may be saved as a trust and a non-charitable one fails and falls into the residue. What changes is tax treatment: the estate-tax charitable deduction is available only for transfers to organizations the Internal Revenue Code describes, so the gift to a non-qualifying organization is not deductible. If deductibility matters, condition the gift on qualification and name an alternate.
Can I include a charity in my will if I have debts?
Yes. Valid claims, the costs of administration and the family protections are paid first, and the gifts in the will are then paid from what remains, reduced in the statutory abatement order if the estate is short. A charitable gift expressed as a share of the residue absorbs that reduction before fixed-dollar and specific gifts do, unless the will says otherwise. If you expect debts to be significant, say which gifts should be protected and which should give way.
Can I name a donor-advised fund in my will?
Yes, by naming the sponsoring organization that maintains the fund, identified by its legal name and EIN, “for the [name] Fund,” using the sponsor’s own recipient instructions. A fund nickname alone is not a legal recipient. Separately, tell the sponsor on its own form who should succeed you as advisor, or which charities should receive the balance, because the will does not control the sponsor’s succession rules.
Do I need a lawyer to add a charity to my Florida will?
Florida does not require one (§ 732.501), but the signing formalities apply to every will and codicil however it was prepared (§ 732.502), and errors in identifying the recipient, missing backup instructions, or giving away an asset the will does not control can prevent the intended result or require court interpretation. A review checks the entity, the fund the gift is measured against, the successor and alternate, the interaction with beneficiary forms, and the spouse’s and homestead rights. Lorenzo Law’s wills start at $675 per person, all-inclusive for the agreed will service.
What is the difference between a donation and a bequest?
Timing and control. A donation is completed during life: the money or property leaves you now, and any income-tax deduction is subject to applicable eligibility, timing, limits and carryover rules. A bequest is a gift in a will that takes effect only at death; until then you keep the property, can change the gift, and receive no income-tax deduction for it. A bequest may instead support the estate’s federal estate-tax deduction if the estate owes that tax and the gift qualifies.
What should I consider when choosing a charity for a legacy gift?
Whether the organization is the exact entity you mean (national, local chapter or foundation arm); whether it is in good standing with the IRS and, if it solicits in Florida, registered with the Department of Agriculture and Consumer Services; whether it will accept the asset and any restriction you have in mind; how it treats restricted and endowed gifts; and what it would do if the program you care about ended. A conversation with its planned-giving office answers most of this.
How much does it cost to include a charitable gift in a will?
The cost to get a will done at Lorenzo Law starts at $675 per person, all-inclusive for the agreed will service. Work on an existing plan, coordination of account designations, restricted gifts or a more complex arrangement is confirmed in the written engagement before it begins. That starting fee does not establish a price for tax or charitable-trust work.
Is sample bequest wording from a charity legally sufficient?
Not by itself. The charity’s suggested wording identifies the organization and its preferred terms, but it must fit a validly executed document, the property’s ownership, the rest of the plan and Florida law. A legally effective gift also remains subject to administration, abatement and other enforceable rights.
Discuss a charitable gift in your Florida will
A useful first conversation covers the organizations you have in mind, the assets you intend for them, the documents and account forms you already have, and the people you also want to provide for. From there the work may be a new will, a codicil, a trust amendment, a set of beneficiary-form changes, or a review of a plan someone else prepared. Jose M. Lorenzo, Jr. is Lorenzo Law’s sole attorney (Florida Bar No. 107002) and handles Florida estate planning, probate and probate litigation, with consultations in English and Spanish. Charitable estate planning, including charitable legacy planning, Florida homestead and spousal-rights review and the coordination of account designations, is part of that work. Lorenzo Law is a solo practice: the attorney you speak with at the first call is the attorney who handles any matter the firm accepts. If you are comparing Florida estate planning attorneys for a charitable gift, bring your existing documents, general asset categories, the charity’s verified identifying information and the choices from the worksheet, and confirm the scope of any drafting, coordination or separate adviser involvement before work begins. The principal office is in Kissimmee; meetings in Coral Gables and Fort Lauderdale are by appointment, and consultations are available statewide by phone and video.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing. Representation requires a conflict review, acceptance and an engagement agreement.
Request a free initial consultationCall (305) 224-6811
¿Prefiere español? Jose M. Lorenzo, Jr. atiende consultas en español sobre cómo dejar dinero o bienes a una organización benéfica en un testamento de Florida, los legados a favor de una iglesia o fundación y la coordinación con los beneficiarios de cuentas. Lea también qué pasa si no hay testamento en Florida.
Explore estate planning for coordinating a future plan, probate administration for handling an estate after death, and probate litigation for a contested matter.
This page provides general information about Florida law and federal tax rules, not advice about a particular estate or a particular gift. Reading it, using the worksheet or requesting a consultation does not create an attorney-client relationship.
Sources and authorities cited
Statutes cited are Florida Statutes (2026). The text of the law and the IRS’s own publications control over any summary on this page.