Closing an Estate in Florida: Final Accounting, Distribution and Discharge
Closing an estate in Florida takes more than paying the bills and the beneficiaries: in a formal administration, the estate is closed when the court enters an order discharging the personal representative.
Settling an estate in Florida ends with that order. This guide covers the final accounting or the waivers that replace it, receipts (often called a “receipt and release”), the petition for discharge and plan of distribution, the objection periods, how long a Florida estate can stay open, how to find out whether an estate is closed and what to do when a closing stalls, for personal representatives and beneficiaries alike. It is about closing a probate estate, not a real-estate closing.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing.
Request a free initial consultationCall (305) 224-6811
Consultations by phone or video in English or Spanish, statewide; meetings by appointment in Coral Gables or Fort Lauderdale. Lorenzo Law’s principal office is in Kissimmee.
Go straight to: Seven steps · Closing checklist · Final accounting · Waivers and receipts · 12-month deadline · Is it closed? · Fees · More questions
By role: if you are the personal representative, start with the closing checklist; if you are a beneficiary asked to sign, with what each signature does; if the estate has not closed, with delay or dispute; if you want to know whether it is closed, with checking the court file.
Formal, summary and ancillary estates · Personal representatives and beneficiaries · All 67 Florida counties · Published flat fees · English and Spanish
All guide sections(40)
Closing an estate in Florida at a glance
Short answer. In a Florida formal administration, an estate is closed when the court enters an order discharging the personal representative, not when the last check is written. Closing ordinarily involves a final accounting unless it is validly waived, a petition for discharge with a plan of distribution, the notice and objection process, proof that the estate was properly distributed and the court’s order of discharge. What happens next depends on what is still unresolved, such as a claim, a tax question, a missing record, a beneficiary’s entitlement or a transfer, rather than on how long the estate has been open. Summary administration ends differently.
| What closes the estate | The court’s order of discharge in a formal administration. Paying the beneficiaries, emptying the estate account or a “closed” label on the docket is not a substitute for that order. What closing means |
|---|---|
| Main documents | Final accounting (or valid waivers of it), petition for discharge with a plan of distribution, proof of distribution such as receipts, and the order of discharge. What each document does |
| Filing deadline | The final accounting and petition for discharge are due within 12 months after letters are issued if the estate is not filing a federal estate tax return; otherwise 12 months from the return’s due date. The court can extend it for cause. A filing deadline is not a promise of when the court will sign the discharge. When the petition is due |
| Objection period | An interested person may object within 30 days after being served with the later of the petition for discharge or the final accounting; notice of hearing on an objection must be served within 90 days after it is filed, or the objection is treated as abandoned. Objections |
| Beneficiaries | A beneficiary decides whether to sign each document. A waiver of accounting, a consent to discharge and a receipt are separate things, even when one form combines them. Should I sign? |
| Summary administration | Ends with the order of summary administration; there is ordinarily no personal representative to discharge. Summary administration |
| Checking the status | Look for an order of discharge in the court file, not only the docket status. Is the estate closed? |
| Who handles it | Jose M. Lorenzo, Jr., a solo attorney: the attorney at the first call is the attorney who handles any matter the firm accepts, through the order of discharge. Getting help |
2026 changes that touch the closing stage
- Attorney’s fees on the statutory schedule: since July 1, 2026, an attorney who intends to charge a personal representative under the fee schedule in section 733.6171 must first give the written disclosures that section requires; see compensation and fees at closing.
- Summary administration limit: the limit in section 735.201 was raised to $150,000 effective July 1, 2026; if the death occurred before that date, confirm which limit applies before filing; see closing a summary administration.
- Who needs a lawyer: Florida Probate Rule 5.030 was amended effective October 1, 2026; it still requires a personal representative to be represented by a Florida attorney, with limited exceptions; see closing without a lawyer.
How do you close an estate in Florida?
In a Florida formal administration, the personal representative closes the estate in seven steps: resolve the claims, settle the tax position, reconcile the records, prepare a final accounting or obtain valid waivers, file and serve the petition for discharge with a plan of distribution, let the objection period run or obtain consents, and then distribute, file proof of distribution and obtain the order of discharge.
- Resolve the claims. Let the creditor period run and make sure every timely claim has been paid, settled or otherwise disposed of, or lawfully provided for.
- Settle the tax position. File the decedent’s final income tax return and the estate’s fiduciary income tax returns where required, and decide how any federal estate tax return and any open tax question will be handled before the last distribution.
- Reconcile the records. Match the inventory, every receipt and disbursement, every sale and every prior distribution to the bank and transfer records, so the ending balance is what is actually on hand.
- Prepare the final accounting, or obtain valid waivers. The accounting follows Florida Probate Rule 5.346; interested persons may waive it in writing.
- File and serve the petition for discharge. It includes a plan of distribution and the statements Rule 5.400 requires; it and the final accounting must both be served on the interested persons. Lawyers file the closing papers with the Clerk through the Florida Courts E-Filing Portal.
- Let the objection period run, or obtain consents. Unless objections are filed, the personal representative distributes promptly under the plan.
- Distribute, prove it and obtain the discharge. File receipts or other proof of distribution; the court enters the order of discharge on evidence that the estate was fully administered and properly distributed.
Those steps describe the formal administration that most estates with a court-appointed personal representative go through. Where closing fits in the whole probate case is explained in the Florida probate process guide; how long the earlier stages take is explained in how long probate takes in Florida.
What does it mean to close an estate in Florida?
Closing an estate means the court has formally ended the administration and discharged the personal representative. Paying the bills and distributing inheritances does not by itself discharge the personal representative.
In a Florida formal administration, the personal representative files a final accounting and a petition for discharge that includes a plan of distribution, serves them on the interested persons, distributes the remaining assets, files proof of distribution and asks the court to enter an order of discharge. The estate is legally closed when that order is entered.
If you are the personal representative, focus on the records and decisions needed to finish the administration. If you are a beneficiary, focus on what you are being asked to approve, what you have actually received and the service dates on any accounting or petition. The personal representative’s attorney does not automatically represent every beneficiary.
Settling, closing, distribution and discharge: the terms
People use several phrases for the end of a probate case, and they do not all mean the same thing:
- Closing out an estate, or estate closure: the last stage, from the final accounting or waivers to the order of discharge.
- Settling or finalizing an estate: the whole administration, from opening the case to the order of discharge. Settling an estate in Florida ends with that order.
- Executor: the everyday word. Florida law calls the office the personal representative; the two words describe the same role.
- Final distribution: handing the remaining assets to the beneficiaries. It happens before discharge, not instead of it.
- Closing papers: in Florida practice, the final accounting (or waivers of it) and the petition for discharge.
- Discharge: the court order that releases the personal representative and, if there is a bond, the surety.
- “Closed” on the docket: an administrative status at the clerk’s office. A closed docket and a discharged personal representative are not always the same thing.
- Receipt and release: the name used in many states and on many websites for the document a beneficiary signs on receiving a distribution. Florida practice usually calls it a receipt of beneficiary, and a Florida form may combine the receipt with a waiver or consent; read what each part says.
- Estate closing letter: two different things share this name. The IRS estate tax closing letter concerns a federal estate tax return; a lawyer’s closing letter to beneficiaries explains a distribution. Neither is the Florida order of discharge.
This page is about closing a probate estate. It is not about a real-estate closing, the sale of a house at a title company. Lorenzo Law does not handle real-estate closings or issue title insurance.
Only the personal representative, or a successor appointed by the court, files the closing papers in a formal administration; a beneficiary who wants the estate closed asks the personal representative or the court, not the clerk. The personal representative controls the estate’s property during the administration, but holds it as a fiduciary for the beneficiaries and creditors and answers to the court for it, so the power is not unlimited.
The distinction that matters most is the one between distribution and discharge. Handing out the assets does not end the personal representative’s responsibility. The court’s order is what closes the administration.
The Florida estate closing sequence
Closing a Florida formal administration follows a sequence in which each step depends on the ones before it. That is why an estate that skips a step usually stalls.
| Step | What is filed or done | Who signs it | Who is served |
|---|---|---|---|
| 1. Creditor period ends | Nothing filed; the claims period runs out | — | — |
| 2. Claims resolved | Claims paid, settled, objected to or otherwise disposed of | Personal representative | Claimants |
| 3. Tax position settled | Required returns filed; refunds or liabilities resolved or provided for | Personal representative | IRS or other taxing authority |
| 4. Homestead and exempt property determined | Petitions and orders, where needed | Personal representative or interested person | Interested persons |
| 5. Final accounting prepared | Receipts, disbursements, distributions and assets on hand for the period | Personal representative | Interested persons |
| 6. Waivers obtained, if any | Written waivers covering the rights each signer gives up | Each interested person who agrees | Filed with the court |
| 7. Petition for discharge filed | Petition including the plan of distribution | Personal representative | Interested persons |
| 8. Objection period runs | Objections, if any, filed and served | Objecting interested person | Personal representative and interested persons |
| 9. Distribution | Assets transferred under the plan of distribution | Personal representative | Beneficiaries |
| 10. Proof of distribution filed | Receipts or other proof the court accepts | Beneficiaries or personal representative | Filed with the court |
| 11. Order of discharge | Order discharging the personal representative and releasing the surety on any bond | The judge | Entered in the court file |
Two points about that sequence are worth stating plainly. Under Florida Probate Rule 5.400(d), the personal representative distributes promptly under the plan unless objections are filed; distributing before the 30-day objection period ends, without consents or waivers, risks an objection after the assets are gone. And under Rule 5.400(e), the court enters the order of discharge on receipt of evidence that the estate has been fully administered and properly distributed, so the discharge really is the last step.
Estate closing checklist: records and what each step depends on
Use this checklist to find the next unresolved item, not to calculate a guaranteed closing date. Different estates need different supporting documents, and court orders, the applicable procedure and local requirements control. A beneficiary may ask for information relevant to his or her interest; the personal representative and counsel assemble and file the estate’s closing papers.
| Closing step | Prerequisite to check | Records to gather and who usually holds them | What changes the next step |
|---|---|---|---|
| Confirm the procedure and authority | Identify the route (formal, summary or ancillary) and who may act | Letters of administration, the will, administration orders, the docket; held by counsel and the clerk | Summary administration and some ancillary routes do not use an ordinary personal representative’s discharge |
| Resolve obligations | Whether claims were paid, settled, barred or otherwise lawfully addressed; taxes and administration expenses paid or provided for | Proof of publication and service of the notice to creditors, the creditor statement, the claims docket, releases or orders, tax correspondence; held by the personal representative, counsel and the tax adviser | A contested, contingent or unmatured claim may need court-approved treatment; a reserve alone does not resolve every issue |
| Confirm recipients and shares | Each beneficiary’s entitlement and who has legal authority to receive it | The will or intestacy analysis, homestead, exempt property or elective share orders where relevant, trust or guardianship papers; held by counsel and other fiduciaries | A disputed share, protected homestead, a minor or an incapacitated recipient can change how distribution is made |
| Reconcile the accounting | Every transaction since the last accounting or the start of administration | Inventory and amendments, statements, deposit records, invoices, sale records, valuations, prior transfers, fee calculations; held by the personal representative, banks and professionals | Missing transactions or unreconciled balances have to be corrected before the final figures can be relied on |
| Decide whether waivers apply | Which interested persons are affected and whether each has authority to sign; what exactly each waives | Written, signed waivers and any representative’s authority; held by the signers and counsel | A waiver of accounting, a compensation waiver and a consent to discharge have different effects; one person’s waiver does not waive another person’s rights |
| File and serve the closing papers | The petition’s required statements and the plan of distribution | Final accounting unless waived, petition, prior distributions, remaining assets, proposed shares, funds retained for closing expenses, service records; held by counsel and the personal representative | Separate service dates affect each objection period; a federal estate tax return and any extension affect the filing deadline |
| Address objections | Filing and service of any objection, the notice-of-hearing period, any court-ordered extension | Objections, proof of service, hearing notices, settlements and orders; held by counsel and the clerk | An objection needs a response or a ruling; the 90-day rule is about serving notice of a hearing, not about when the hearing takes place |
| Complete distribution | Carry out the plan with authorized recipients and adequate provision for remaining obligations | Cleared payment records, transfer confirmations, recorded deeds, beneficiary receipts or other proof the court accepts; held by the personal representative, recipients and institutions | Refusing to sign a receipt is different from refusing the property; section 733.816 may call for a court-directed solution |
| Obtain the discharge and finish the records | Proof of full administration and proper distribution | The order of discharge, bond-release papers if there is a bond, final reconciliations and retained records; held by counsel, the clerk, the surety and the personal representative | Paying the beneficiaries, an empty bank account or a “closed” docket label does not replace the order of discharge |
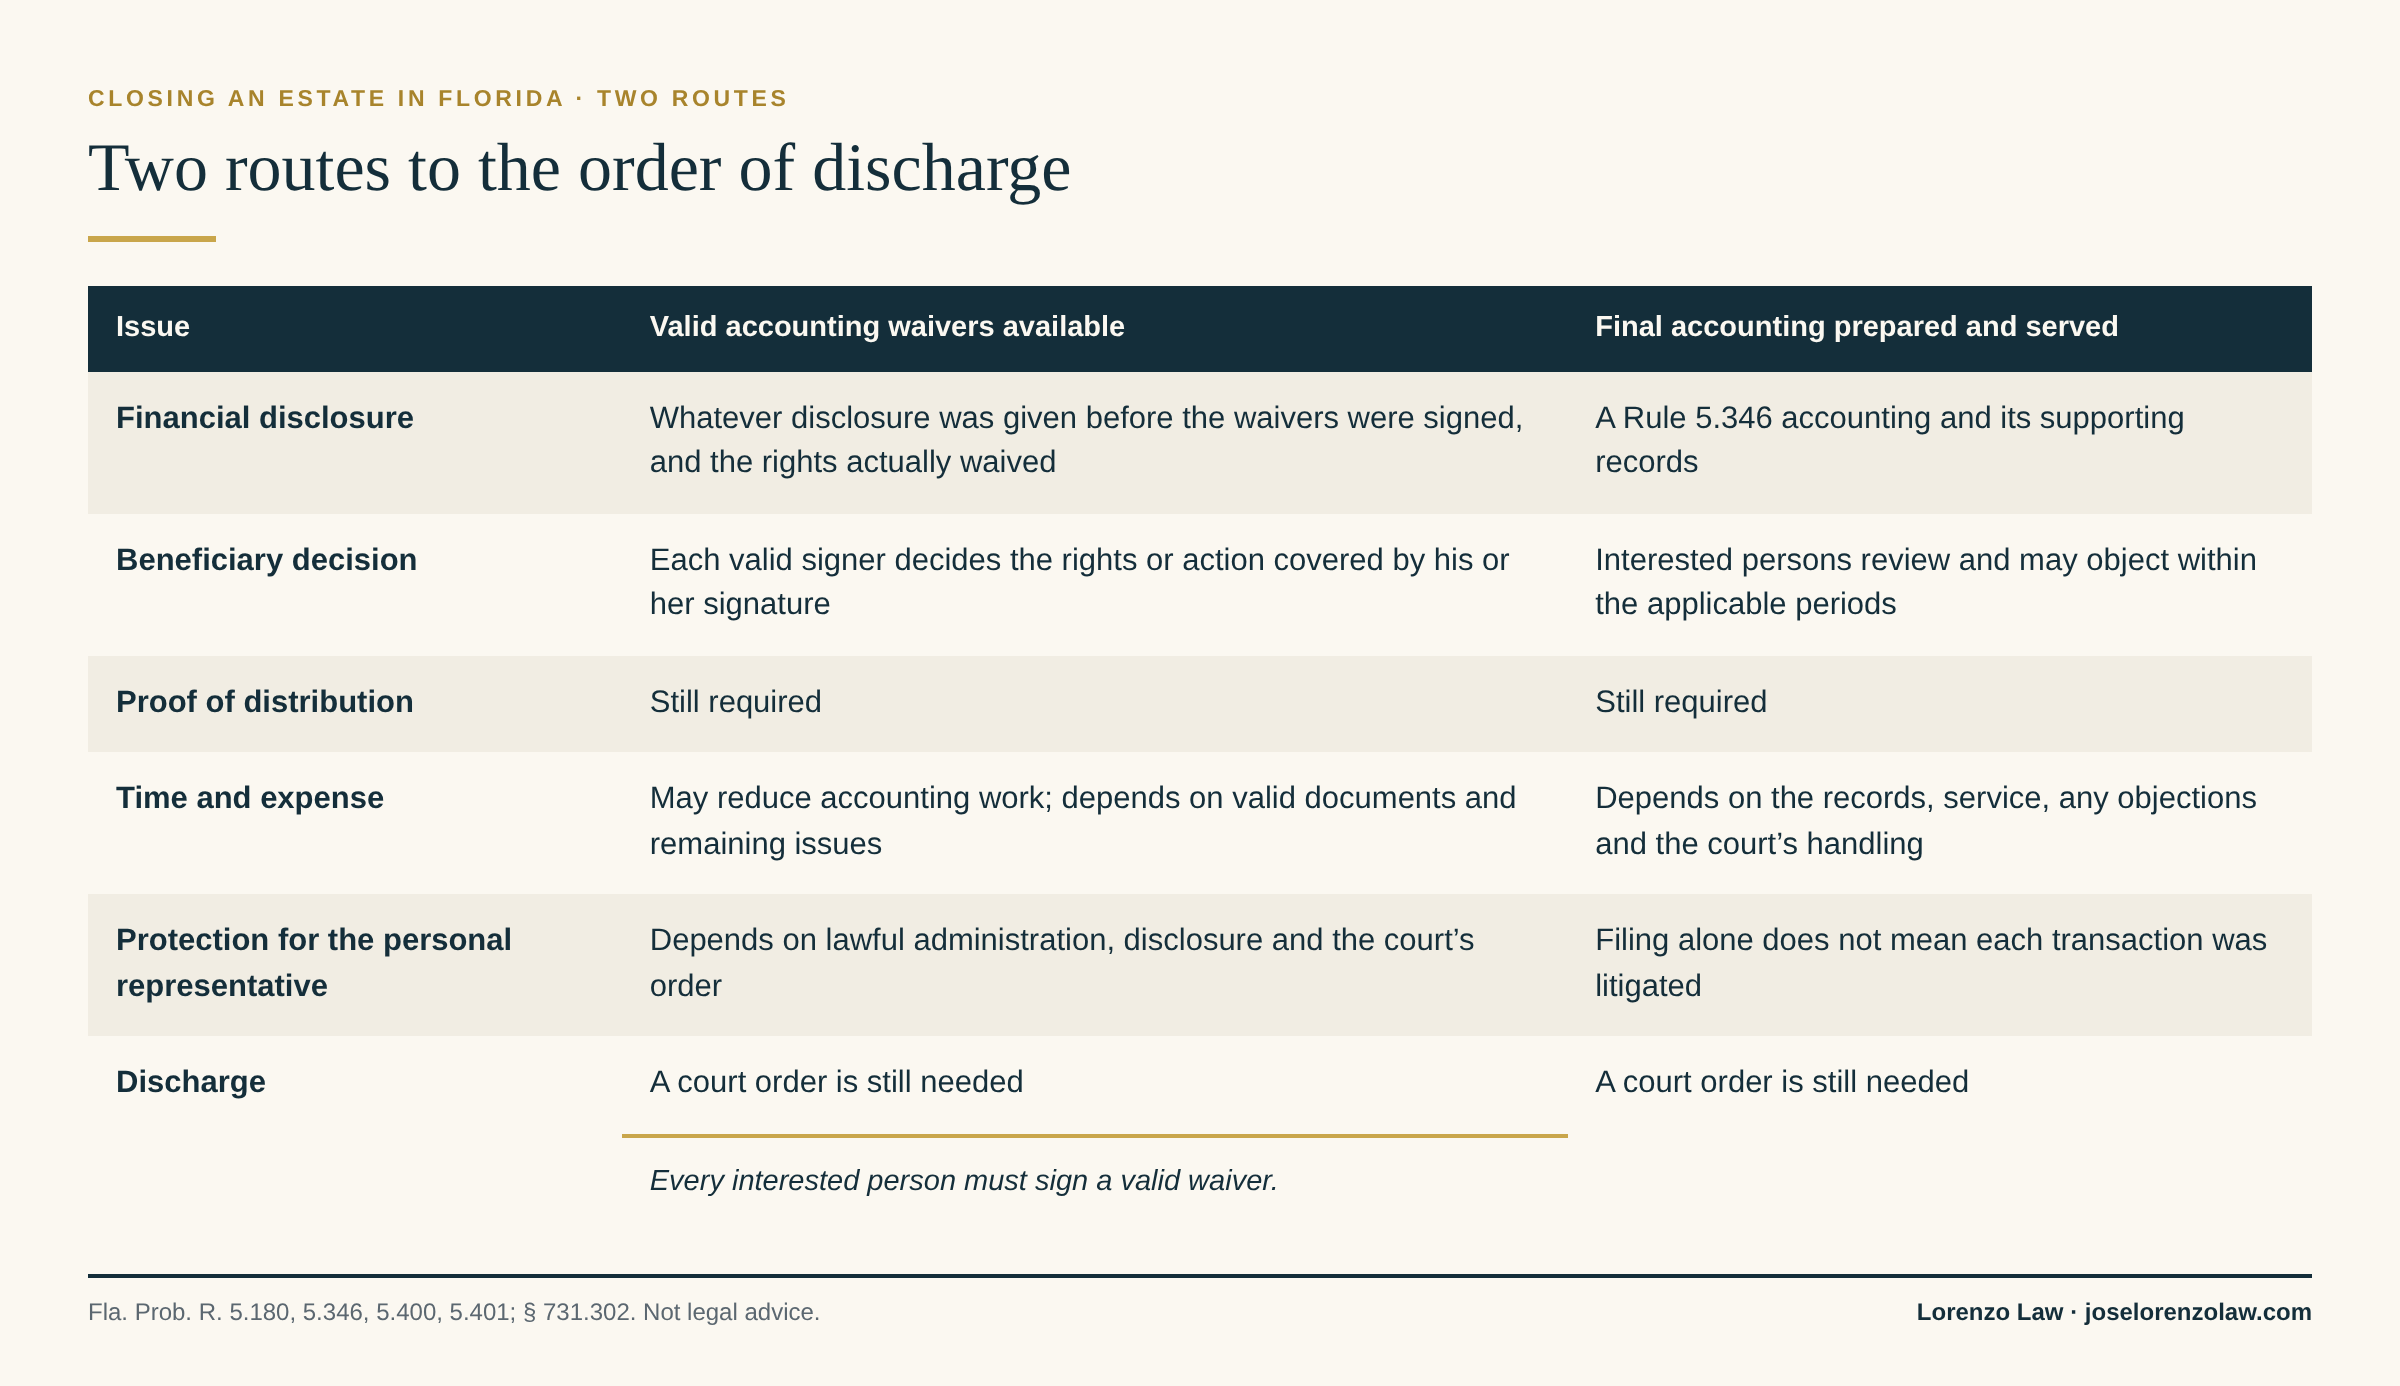
Chart: Two routes to the order of discharge
Before you can close: the prerequisites
Among the executor’s responsibilities, described in duties of a personal representative in Florida, finishing these steps comes before any closing paper is filed. Most estates that will not close are not stuck on the paperwork. They are usually waiting on one of these six prerequisites, each of which may keep an estate open until it is resolved or lawfully provided for.
The creditor claim period has to run
A Florida estate is not ready to close while the claims period is still open, because the personal representative does not yet know what the estate owes. Florida runs two clocks, and they do different jobs.
Section 733.702 is the nonclaim statute: a claim is not binding on the estate, the personal representative or any beneficiary unless it is filed by the later of three months after the first publication of the notice to creditors or 30 days after service of the notice on a creditor entitled to be served. A claim not filed in time is barred even if nobody objects, unless the court extends the time for fraud, estoppel or insufficient notice.
Section 733.710 is different in kind: it is a two-year limit running from the date of death, which the Florida Supreme Court has described as jurisdictional and not subject to waiver or extension in the probate proceeding. May v. Illinois National Insurance Co., 771 So. 2d 1143, 1157 (Fla. 2000); Tsuji v. Fleet, 366 So. 3d 1020, 1023–24 (Fla. 2023). Section 733.710 does not apply to a creditor who filed a timely claim that has not been paid or otherwise disposed of, or to recorded mortgages, security interests and certain liens. It is not a mandatory two-year wait before an estate can close. The full rules on claims are in Florida probate creditor claims.
Every timely claim has to be paid, settled or disposed of
A claim is disposed of when it is paid, compromised, withdrawn, struck or resolved by an objection followed by the claimant’s failure to bring an independent action in time. An unresolved claim matters at closing because the petition for discharge has to state that every claim presented has been paid, settled or otherwise disposed of. Unmatured and contingent claims have their own procedures under section 733.705, which can involve court-directed security, retention of assets or other arrangements.
Taxes have to be paid or provided for
Florida does not currently collect an estate tax or an inheritance tax, but federal returns still matter. The estate’s fiduciary income tax return, the decedent’s final individual return and, for an estate filing one, the federal estate tax return have to be addressed before the personal representative distributes everything and asks to be released. The petition for discharge states that the personal representative has paid or made provision for taxes and expenses of administration. See tax records at closing below.
Homestead and exempt property have to be determined
Protected homestead is not an ordinary probate asset and is generally outside the personal representative’s right of possession. When a Florida residence may be protected homestead, families often ask the court for an order determining homestead status, because that order is what title companies and buyers usually look for. No statute makes a homestead order a condition of every discharge, and whether one is needed depends on the title, the family and the plan for the property. The personal representative does not list protected homestead in the plan of distribution as an estate asset to be distributed. Exempt property has to be claimed and determined separately.
Spousal and family entitlements have to be resolved
If a surviving spouse has elected against the will, the elective share has to be determined and satisfied before the residue can be divided. The same is true of a family allowance and of any exempt property claim. An estate that reaches the petition for discharge with any of these unresolved is not fully administered, and the plan of distribution cannot be right.
Under section 732.402(6), the right to exempt property is lost unless a petition to determine exempt property is filed within the period the statute sets, measured from service of the notice of administration or from the end of certain proceedings. The family allowance under section 732.403 has a statutory maximum of $18,000. Where a surviving spouse has elected the elective share, or may still elect it, confirm the status of that election before filing for discharge.
The assets have to be in a form that can be distributed
Real property that has not sold, a business interest nobody has valued, a pending lawsuit or an unliquidated insurance claim can keep an estate open until the issue is resolved or lawfully provided for. Sometimes the answer is to distribute the asset in kind rather than wait for a sale. See distribution in kind.
The final accounting in Florida probate
The final accounting is the personal representative’s complete financial report of the administration. It is not a bank statement and not a summary: it is a verified document with a defined structure, and interested persons may examine it and object to it.
What a Florida final accounting contains
| Component | What it shows |
|---|---|
| Starting balance | The assets the personal representative took in, at inventory or carrying value |
| Receipts | Everything that came into the estate during the accounting period: income, refunds, sale proceeds, recovered assets |
| Disbursements | Everything paid out: claims, administration expenses, taxes, fees and costs |
| Capital transactions | Sales, exchanges and other dispositions, with gains and losses against carrying value |
| Distributions | Anything already distributed to a beneficiary during the administration |
| Assets on hand | What remains to be distributed, described and valued |
| Compensation | Fees paid to the personal representative and attorney |
Florida Probate Rule 5.346 requires an understandable accounting of cash and property transactions since the last accounting, or from the start of administration if there was none, and a schedule of assets at the end of the period. It calls for both acquisition or carrying values and estimated current values, together with disclosure of gains, losses and significant transactions. The fiduciary must verify the accounting. Bank statements support this work; they are not a substitute for the accounting. Not every value requires a professional appraisal. The rule includes a model format that lawyers use as a reference.
How do I prepare a final accounting for an estate?
Start from the inventory and the opening balances, then post every receipt and disbursement from the estate account in date order, record each sale as a capital transaction rather than a simple receipt, list each prior distribution, and end with the assets actually on hand. The ending balance has to equal the starting balance plus receipts, minus disbursements and distributions, adjusted for gains and losses. Keep the supporting records together, because an interested person may ask to see them. Rule 5.346 includes a model accounting format, but a template downloaded from a website can omit a required statement or schedule; see closing an estate without a lawyer.
Who gets to see the final accounting
Rule 5.400 requires the final accounting to be filed and served on the interested persons. An interested person is defined in section 731.201(23) as anyone who may reasonably be expected to be affected by the outcome of the particular proceeding, and the definition expressly excludes a beneficiary who has already received complete distribution. That normally includes residuary beneficiaries whose shares depend on the numbers. A beneficiary whose specific gift has already been satisfied usually stands differently.
A Florida estate accounting is not an ordinary public record. Probate files are generally public, but inventories and accountings are confidential under section 733.604(1). The persons the statute lists may see them; anyone else needs a court order on good cause.
Mistakes that cause problems with an accounting
- The ending balance does not reconcile to the inventory plus receipts minus disbursements.
- Assets are carried at a value that was never established.
- Personal expenses of the personal representative appear as administration expenses.
- Compensation appears as a lump sum with no disclosure of how it was calculated.
- A sale is shown as a receipt with no capital transaction entry, so the gain or loss disappears.
- The accounting period leaves a gap between the last interim accounting and the final one.
Interim and amended accountings
A long administration may call for an interim accounting along the way, and an accounting that contains an error can be amended or supplemented before the court rules. Offering a correction is usually better than defending an accounting that is known to be wrong.
Interim accountings are governed by Florida Probate Rule 5.345: the personal representative may elect to file one at any time, or the court may require an interim or supplemental accounting, and notice and a copy must be served on the interested persons.
If an accounting is amended after it has been served, counsel should determine who must receive the amendment, whether a new objection opportunity is required and whether a court order affects the timetable. Do not assume either that the original date always controls or that every amendment automatically restarts every deadline.
Waivers, consents and receipts: what each closing document does
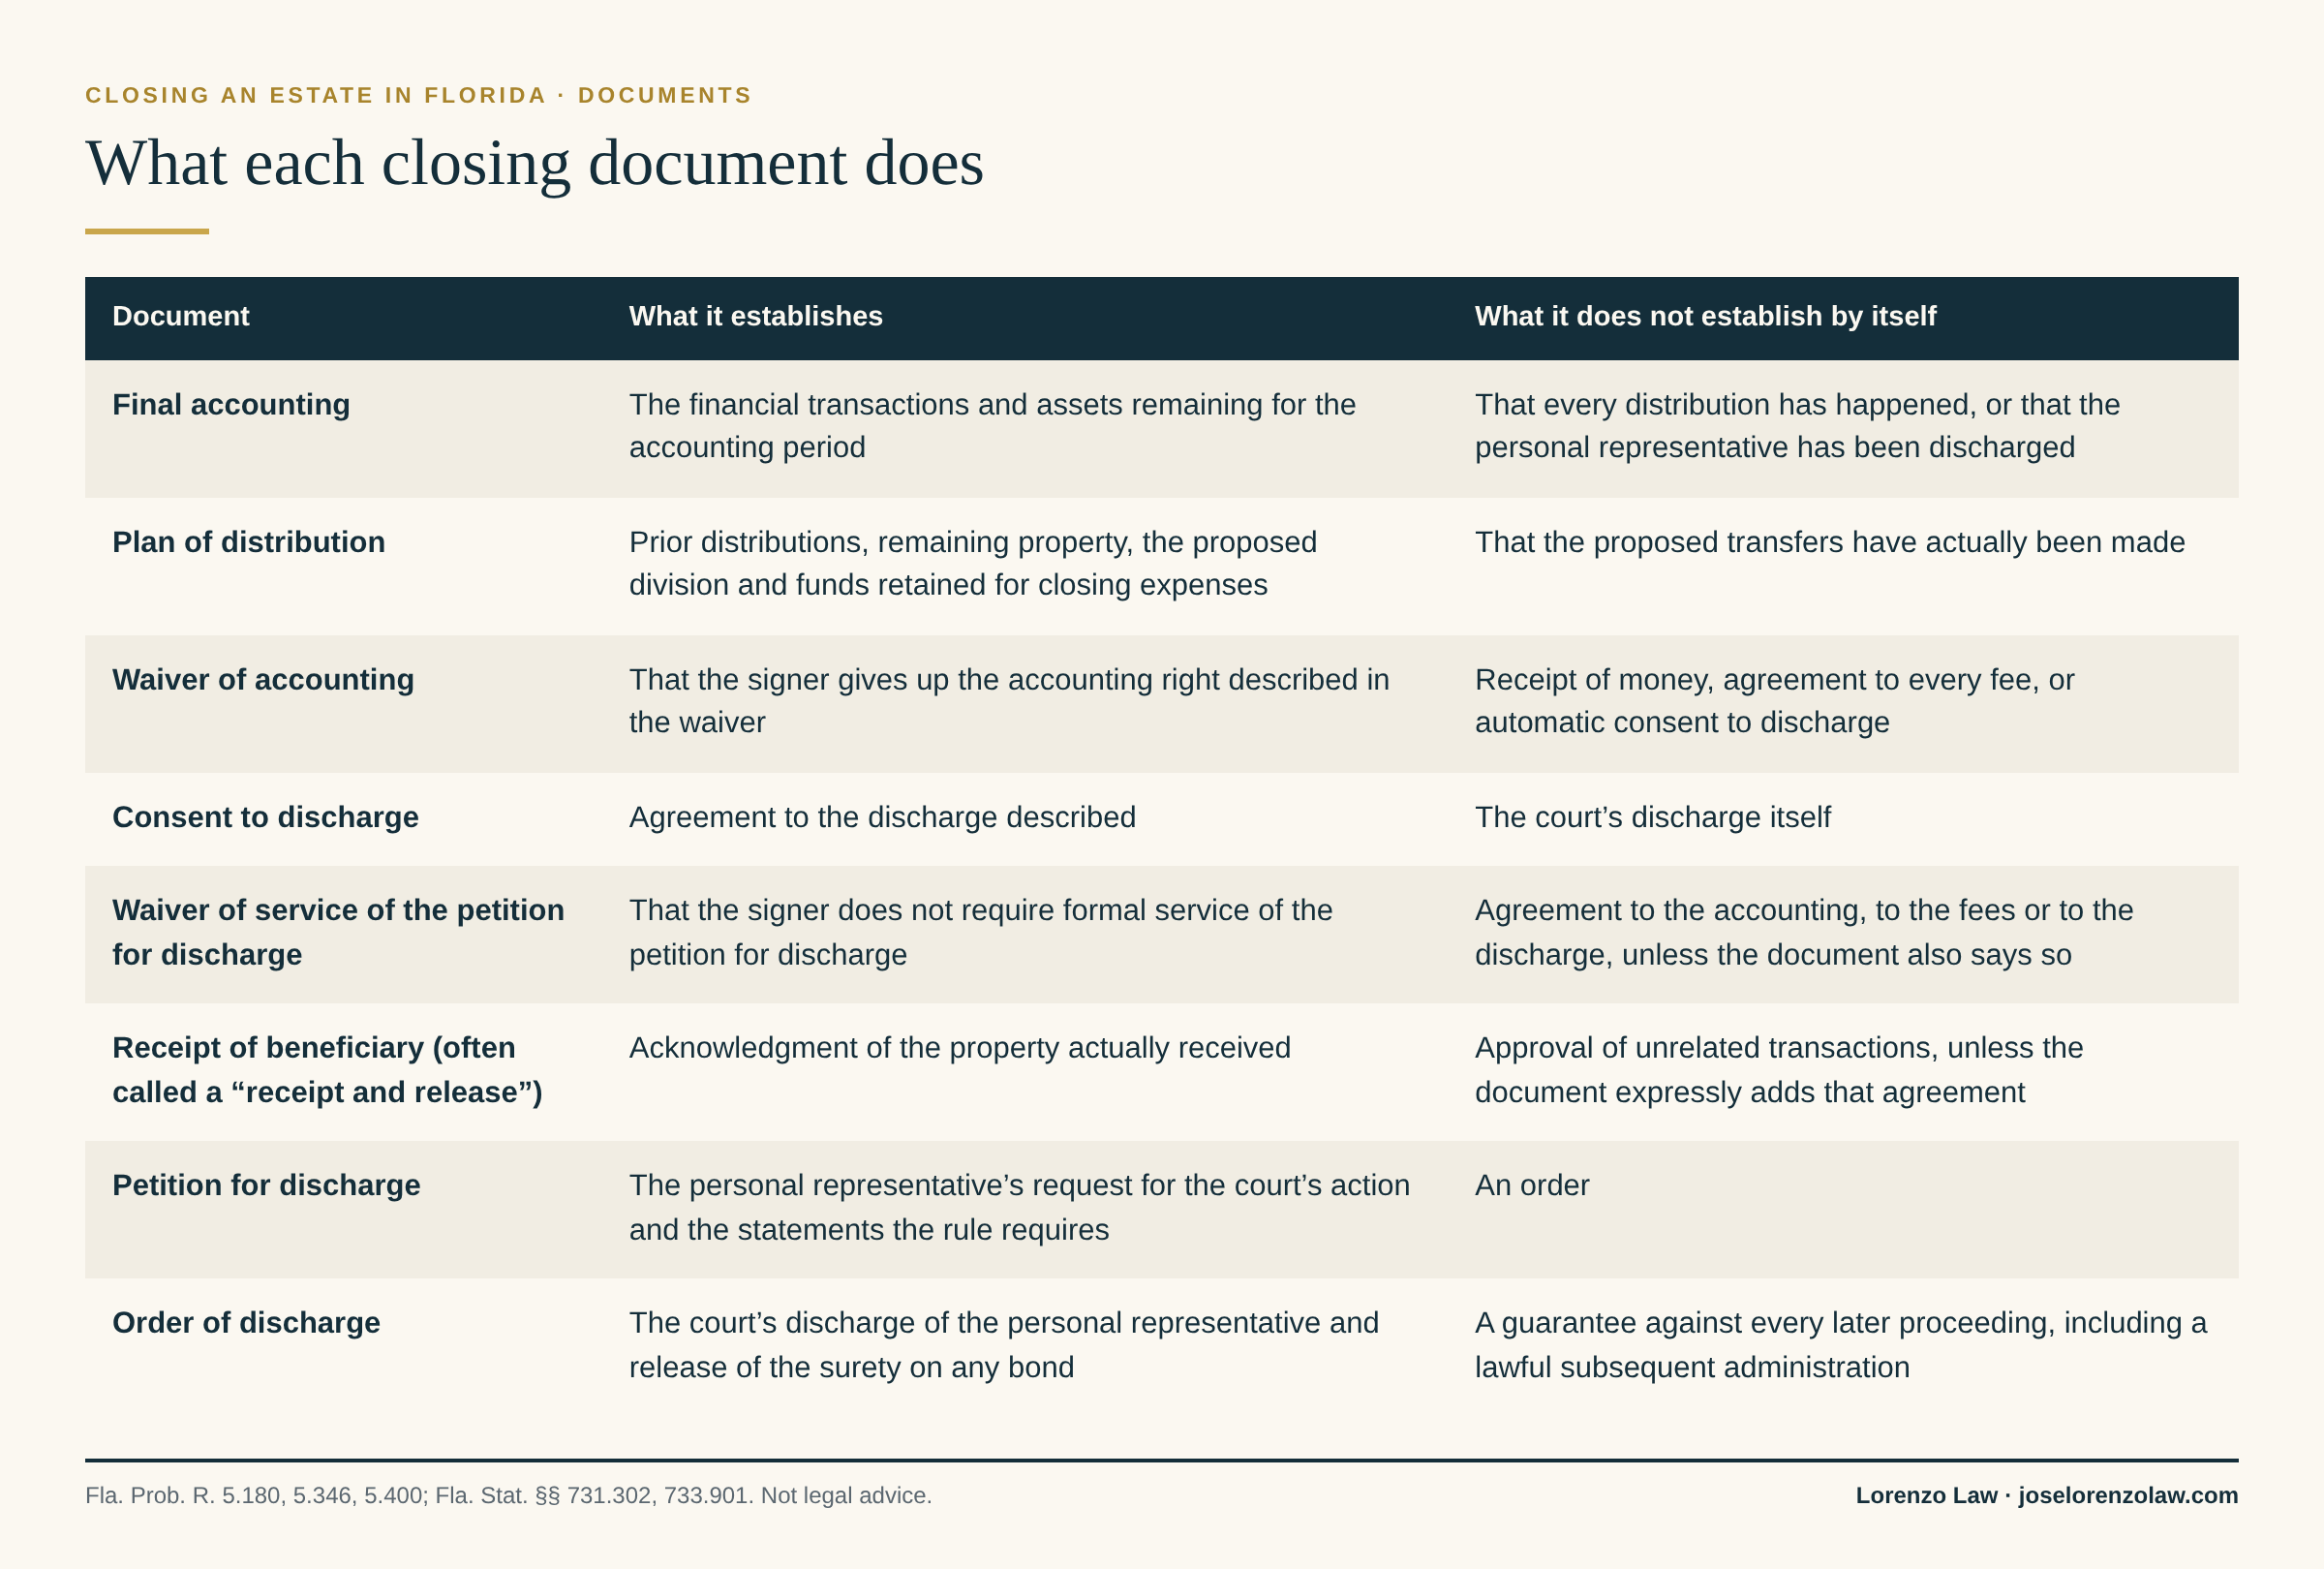
Each closing document proves one thing. A waiver of accounting gives up the right it describes; a consent to discharge agrees to the discharge; a receipt acknowledges property actually received. None of them is the order of discharge, and signing one does not automatically sign the others, even when a single form contains several of them.
| Document | What it establishes | What it does not establish by itself |
|---|---|---|
| Final accounting | The financial transactions and assets remaining for the accounting period | That every distribution has happened, or that the personal representative has been discharged |
| Plan of distribution | Prior distributions, remaining property, the proposed division and funds retained for closing expenses | That the proposed transfers have actually been made |
| Waiver of accounting | That the signer gives up the accounting right described in the waiver | Receipt of money, agreement to every fee, or automatic consent to discharge |
| Consent to discharge | Agreement to the discharge described | The court’s discharge itself |
| Waiver of service of the petition for discharge | That the signer does not require formal service of the petition for discharge | Agreement to the accounting, to the fees or to the discharge, unless the document also says so |
| Receipt of beneficiary (often called a “receipt and release”) | Acknowledgment of the property actually received | Approval of unrelated transactions, unless the document expressly adds that agreement |
| Petition for discharge | The personal representative’s request for the court’s action and the statements the rule requires | An order |
| Order of discharge | The court’s discharge of the personal representative and release of the surety on any bond | A guarantee against every later proceeding, including a lawful subsequent administration |
Chart: What each closing document does
Waiver of accounting and consent to discharge
An accounting waiver gives up the right described in that waiver. Consent to discharge, waiver of objections to compensation and acknowledgment of receipt are separate matters, even when a form combines them. Read each provision before signing.
Under Florida Probate Rule 5.180, a waiver or consent must be in writing, signed and filed; it must identify the signer’s interest and any representative capacity, and it must expressly state what is waived or consented to. A compensation waiver must also state that the signer knows the amount and method, and agrees or waives court review. Under section 731.302, a person may waive only his or her own rights, or rights he or she lawfully represents, and representation and conflicts rules apply.
A personal representative who is also a beneficiary is an interested person too, and signs the same waivers and consents in that individual capacity.
Dispensing with the final accounting requires valid waivers covering the affected interested persons. Who qualifies as an interested person depends on the proceeding. If a required waiver is not available, counsel can use the accounting and notice procedure instead; one refusal is not a veto of the closing. A valid waiver does not excuse the personal representative from administering and distributing the estate properly.
Waivers are common and, in the right estate, sensible. Preparing a formal accounting takes time and costs money, and in a small estate where everyone already knows what came in and what went out, the accounting can cost more than it reveals.
A beneficiary who signed may still be able to challenge a waiver obtained without full and fair disclosure of the material facts. A personal representative that did not disclose what it did with an estate asset could not rely on the discharge, even against beneficiaries who had consented to it; “the price of immunity is disclosure.” Van Dusen v. Southeast First National Bank of Miami, 478 So. 2d 82, 91 (Fla. 3d DCA 1985).
When a beneficiary should get advice before signing a waiver
A waiver is the point at which a beneficiary gives up the most detailed look at the administration. Get an explanation, and independent advice, before signing if:
- You have never received a clear statement of what the estate received and what it paid out.
- You do not know what the personal representative and the attorney are being paid.
- Assets were sold and you do not know to whom, for how much or how the price was set.
- Estate assets were used, occupied or managed by someone connected to the personal representative.
- You are being asked to sign the waiver and the receipt at the same time, before you have been paid.
Unequal shares, or a personal representative who is also a beneficiary, do not by themselves mean anything is wrong; they are reasons to read the numbers carefully. Ask for the records supporting your distribution and any proposed waiver; the information available depends on your interest and the proceeding.
Should I sign the waiver or the receipt before I am paid?
Most beneficiaries are asked to sign more than one document at the end. Each signature does something different, so it helps to decide them one at a time.
A beneficiary’s signing checklist
| Document you are asked to sign | Ask for first | What signing gives up or confirms | When it is usually reasonable to sign |
|---|---|---|---|
| Waiver of accounting | An informal statement of what came in and went out, the fees and your exact share | Your right to a formal, verified final accounting, to the extent the waiver says | When you have seen enough to be comfortable with the numbers |
| Waiver of objections to compensation | The amount of each fee and how it was determined | Objections to the compensation described | When you know the amounts and the method |
| Consent to discharge | The petition for discharge and the plan of distribution | Your agreement to the discharge described | When the plan matches your share and nothing is unresolved |
| Receipt of beneficiary (“receipt and release”) | The payment or transfer itself | Confirmation that you received what the document lists | After the money has cleared or the property is in your name; do not acknowledge property you have not received |
| Refunding or indemnity agreement | What it would require you to repay and why | A promise to return money if a later obligation appears, on the terms stated | After you understand the obligation it covers |
What if one beneficiary refuses to sign?
One refusal does not stop the estate from closing. It changes the route: instead of closing on waivers, the personal representative prepares the final accounting, serves it with the petition for discharge and lets the objection period run. That usually costs more and takes longer, but it does not depend on everyone’s cooperation. A beneficiary who declines a waiver is asking for a formal review, which is the beneficiary’s right; it is not obstruction.
Receipt of beneficiary and consent to discharge
A waiver of accounting says, in effect, “I do not need to see a formal accounting.” A receipt of beneficiary says “I received my share.” They are different documents doing different jobs, and an estate often needs both.
Signed receipts are a common way to show that beneficiaries received their distributions. Rule 5.400(e) requires evidence of full administration and proper distribution. If a recipient will not sign, counsel should determine what other proof the court will accept, such as cleared payments or completed transfer records. Local procedures may call for receipts, so explain the missing receipt and ask for the court’s direction rather than assuming another document is automatically enough.
How receipts work in practice
- One receipt per distributee, signed after that distributee has actually been paid or taken delivery.
- The receipt should describe what was received specifically enough to match the plan of distribution: the amount or the asset, not just “my share.”
- A combined “receipt of beneficiary and consent to discharge” records both the distribution and the beneficiary’s consent.
- Do not ask a recipient to acknowledge property not yet received.
- A beneficiary who has been paid but will not sign is a solvable problem; see when a beneficiary will not sign.
Where the distributee is a minor or an incapacitated adult, the receipt has to be signed by a person with legal authority to receive the property; see minor and incapacitated beneficiaries.
What is a receipt and release in Florida probate?
“Receipt and release” is the name many websites and other states use for the paper a beneficiary signs when a distribution is made. In Florida probate the court document is usually a receipt of beneficiary, sometimes combined with a consent to discharge or a waiver. Some estates also ask for a private agreement, sometimes titled a “receipt, release and refunding agreement” or a “receipt, release, refunding and indemnification agreement,” in which the beneficiary promises to give money back if a later obligation appears. Read each paragraph: acknowledging receipt, releasing claims and agreeing to refund are three different promises, and a document can contain any combination of them.
The plan of distribution
The plan of distribution is the part of the petition for discharge that tells everyone who gets what. It is the part a beneficiary usually reads first, and the part objections are usually aimed at.
Rule 5.400(b)(5) requires the plan to show four things: (A) a schedule of all prior distributions; (B) the property remaining in the hands of the personal representative for distribution; (C) a schedule describing the proposed distribution of the remaining assets; and (D) the amount of funds retained by the personal representative to pay expenses incurred in distributing the remaining assets and ending the administration.
Item (D) answers a question personal representatives ask often: a reserve for the cost of closing is part of the rule, and the plan says how much is held back. That provision is not a blanket exception that allows an estate to ignore disputed debts or unresolved taxes. Unmatured and contingent claims have separate procedures under section 733.705, which can involve court-directed security, retention or other arrangements; match the proposed treatment to the actual obligation and any order.
A plan that is vague about a reserve, or that shows a fee without explaining it, invites an objection that a clearer plan would have avoided.
Distribution in kind, partial distribution and final distribution
Distribution in kind means transferring the asset itself rather than selling it and distributing cash: deeding the house to the beneficiaries, transferring the brokerage account or assigning a note. It can be the right answer when a property will not sell, when the beneficiaries want the asset or when a forced sale would waste value.
Partial distribution means distributing some assets during the administration and the rest at closing. It helps when beneficiaries need money and the estate is plainly able to pay everything it owes, but assets distributed early can be hard to recover if a claim or expense appears later.
Final distribution is the transfer of the remaining assets under the plan of distribution. It happens before the discharge and is not the same as the estate being closed.
When estate real property is distributed, the transfer is usually documented by a personal representative’s deed recorded in the county where the property is located. A personal representative’s deed is not automatically the right instrument for protected homestead. If the estate is still trying to sell a house, see selling a house in probate in Florida.
Two related questions depend on the particular estate and are worth settling before the plan of distribution is drafted: the valuation date used for property distributed in kind, and the order in which gifts are reduced if the estate cannot pay everything.
When beneficiaries receive their inheritance
Beneficiaries are usually paid after the creditor period has run, timely claims and expenses have been paid or provided for and the tax position is known; a partial distribution can come earlier when the estate can plainly pay what it owes. How long it takes a beneficiary to receive an inheritance therefore depends on those steps, not on a fixed number of months.
In a formal administration, the last distributions usually follow the final accounting or the waivers that replace it: once the objection period has run or every interested person has consented, the remaining assets and funds can be distributed under the plan of distribution, and the receipts are then filed before the order of discharge. There is no reliable average for how long estate settlement takes, because the timeline turns on the unfinished task rather than the calendar; see how long a Florida estate can stay open. An estate in which nothing has moved for months is worth a question to the personal representative, and the delay-or-dispute signs help tell the difference.
Brothers and sisters inheriting the family house together
Settling an estate with siblings often comes down to the house. When the family house goes to several children, the plan can distribute it to them together as co-owners, or one sibling can buy the others’ shares before closing, or the house can be sold and the cash divided. Co-owners who later disagree can ask a court to divide or sell the property in a partition action; see Florida partition actions. Deciding this before the plan of distribution is served avoids an objection at the last step.
The petition for discharge
The petition for discharge, which people often call the petition to close the estate, is the personal representative’s formal request to be released. It is filed with the final accounting, or with the waivers if the accounting has been waived, and it is served on every interested person.
Rule 5.400(b) requires the petition to contain seven statements: (1) that the personal representative has fully administered the estate; (2) that all claims presented have been paid, settled or otherwise disposed of; (3) that the personal representative has paid or made provision for taxes and expenses of administration; (4) the amount of compensation paid or to be paid to the personal representative, attorneys, accountants, appraisers or other agents, and the manner of determining it; (5) the plan of distribution; (6) that any objections to the accounting, the compensation or the proposed distribution must be filed within 30 days of service of the later of the petition or the final accounting, and that within 90 days after an objection is filed a notice of hearing must be served or the objection is abandoned; and (7) that objections must be in writing and state with particularity the items objected to and the grounds.
| What the petition addresses | Why it matters |
|---|---|
| Full administration | The court will not discharge a personal representative who still has work to do |
| Claims paid, settled or disposed of | An unresolved claim has to be dealt with before the estate is fully administered |
| Taxes and expenses paid or provided for | Distribution should not leave an unpaid obligation behind |
| Compensation paid or to be paid | A beneficiary has a direct financial interest in this item and may object to it |
| The plan of distribution | Tells each beneficiary what he or she will receive |
| Notice of the objection rights and deadlines | The warnings are part of what makes the deadlines operate |
Item (6) is not boilerplate. Where a petition for discharge omitted the required warning about the 90-day abandonment rule, a Florida court held that the abandonment provision could not be applied against the objector. Estate of Guthrie v. Guthrie, 478 So. 2d 465, 466–67 (Fla. 1st DCA 1985) (petition filed before the rule required the warning).
When the petition for discharge is due
Rule 5.400(c) requires the final accounting and the petition for discharge to be filed and served on the interested persons within 12 months after letters are issued for an estate not filing a federal estate tax return. Otherwise, the rule measures 12 months from the return’s due date. That is not limited to estates legally required to file: Rules 5.395 and 5.400 also cover an estate that files, or will file, a federal estate tax return. Rule 5.395 requires notice of the return’s due date within 12 months after letters, with a further notice when the due date is extended.
The court can extend the deadline for cause after notice to the interested persons; the petition for an extension must explain the estate’s status and why more time is needed. This is a filing-and-service requirement, not a promise that a judge will enter the discharge by that date.
What happens if the personal representative misses the 12-month deadline?
Passing the deadline does not close the estate, and it does not by itself establish grounds for removal or for a damages award. Keeping an estate open past the 12-month period does not deprive the probate court of subject-matter jurisdiction. Herskowitz v. Nesbitt, 419 So. 2d 418 (Fla. 3d DCA 1982). The deadline still matters: the personal representative is expected to file on time or obtain an extension, and an interested person can ask the court to require the closing papers, an accounting or the status of the estate. Failure to comply with a court order and failure to account are among the grounds for removal listed in section 733.504, and a personal representative is liable for loss caused by a breach of duty.
Some circuits also review inactive cases and may require a status report or set a hearing. An estate that is closed administratively for inactivity is not the same as a personal representative who has been discharged.
Closing with waivers or with a final accounting
Both routes are formal administration, and both end with the court’s order of discharge. The difference is whether the interested persons waive the formal accounting or receive one.
| Issue | Valid accounting waivers available | Final accounting prepared and served |
|---|---|---|
| Financial disclosure | Whatever disclosure was given before the waivers were signed, and the rights actually waived | A Rule 5.346 accounting and its supporting records |
| Beneficiary decision | Each valid signer decides the rights or action covered by his or her signature | Interested persons review and may object within the applicable periods |
| Proof of distribution | Still required | Still required |
| Time and expense | May reduce accounting work; depends on valid documents and remaining issues | Depends on the records, service, any objections and the court’s handling |
| Protection for the personal representative | Depends on lawful administration, disclosure and the court’s order | Filing alone does not mean each transaction was litigated |
| Discharge | A court order is still needed | A court order is still needed |
Valid accounting waivers available: Every interested person must sign a valid waiver.
A beneficiary who asks pointed questions about money is not an adversary. When questions come up, a formal accounting is often the clearest way to answer them, and it gives everyone a verified record.
Objections to the final accounting or petition for discharge
Once the final accounting and the petition for discharge are served, an interested person has a limited period to object. An objection is not a letter of complaint: it is a written document, filed and served, that identifies the specific items objected to and states the grounds for each.
The objection deadlines
| Required act | Rule period and trigger | Qualification |
|---|---|---|
| File a written objection stating the items and grounds with particularity, and serve it on the personal representative and the interested persons | 30 days after service on that objector of the later of the petition for discharge or the final accounting | Apply Rules 5.401 and 5.042 and the governing time-computation and service rules; do not count from the date of death, from filing alone or from someone else’s service |
| Serve notice of hearing on the objection | Within 90 days after the objection is filed | Any interested person may set the hearing; the rule requires service of the notice, not that the hearing take place within 90 days |
| Ask for relief if a period is missed | Depends on the case | Enlargement may be available under Rule 5.042; it is not automatic, and rehearing and appellate deadlines follow different rules |
The 30 days run separately for each interested person, from the date that person was served with the later of the two documents. If the accounting and the petition go out on different dates, the period starts with the later one.
Standing depends on whether a person may reasonably be affected by the particular proceeding. A creditor with a timely, unresolved claim may remain an interested person; payment or other disposition of the claim can change that. Do not decide notice or objection rights from the label “creditor” alone.
The 90-day rule is not as absolute as it reads. A Florida court allowed a short enlargement for excusable neglect under Rule 5.042 and reversed a finding that objections had been abandoned. In re Estate of Cummins, 979 So. 2d 984, 985–86 (Fla. 3d DCA 2008). That is a narrow exception, not something to plan on.
What a valid objection looks like
Objections that succeed tend to be about specific items: a payment that was not an estate expense, compensation that is not supported, an asset carried at a value nobody established, a sale to an insider, a missing transfer or a distribution that does not match the will. Delay that is tied to a missed duty or a loss deserves a factual review; frustration that the process took a long time, without more, is rarely enough.
What happens at the hearing
If an objection is set for hearing, the court sustains or overrules it and determines the plan of distribution. That can mean disallowing a payment, reducing compensation, ordering a different division or requiring a corrected accounting. Who bears the costs and fees depends on the proceeding and the court’s rulings. A contested objection is probate litigation.
The order of discharge, and what it releases
The order of discharge is the judge’s order ending the administration, discharging the personal representative and releasing the surety on any bond. A signed waiver from every beneficiary, a fully distributed estate or a closed docket does not do that by itself.
The order of discharge is what many people mean by the release of the executor: in Florida, the personal representative is released by the court’s order, not by a beneficiary’s signature.
Once the order is entered, obtain a certified copy and keep it. Banks, title companies and transfer agents may ask for it later.
Section 733.901(2) provides that the discharge releases the personal representative and bars any action against the personal representative, as such or individually, and the surety. Florida courts have described it as a form of res judicata for probate.
Why discharge makes later challenges harder
Discharge has substantial finality consequences under section 733.901. Challenges after discharge raise different procedural questions from timely objections before it. In a 2026 Third District decision, an objection filed nine days after the discharge order was entered was held untimely. Gilbert v. Riley, 431 So. 3d 588 (Fla. 3d DCA 2026). Earlier decisions treated a petition to revoke probate filed after discharge the same way. In re Jackson’s Estate, 236 So. 2d 475, 477 (Fla. 4th DCA 1970); Yellen v. Long, 387 So. 2d 384, 384–85 (Fla. 4th DCA 1980). That is why an interested person who is uneasy about an accounting should file the objection within the period rather than wait for a conversation.
The bar is not absolute. Florida courts recognize an exception where the personal representative did not disclose what it did with an estate asset. Van Dusen v. Southeast First National Bank of Miami, 478 So. 2d 82, 91 (Fla. 3d DCA 1985). The line runs between an accounting that is merely inaccurate, which the discharge generally bars, and one that withholds a disposition from the court and the beneficiaries, which it may not. Alleged fraud, nondisclosure or procedural irregularity calls for prompt, case-specific advice; neither an automatic right to reopen nor absolute immunity should be assumed. After-discovered assets are handled differently again, through subsequent administration.
How long someone has to attack a closed administration for fraud is not settled by section 733.901 itself, which contains no period of its own. The answer depends on the claim, when it accrued and the procedure used, so get advice promptly rather than relying on any single number.
For a personal representative, the point to remember is that a signed waiver plus a signed receipt, without an order of discharge, does not end the personal representative’s exposure. The statutory release is tied to the order.
Release of the bond and the surety
If the court required the personal representative to post a bond, the order of discharge is also what releases the surety on that bond. Until then the bonding company remains responsible, and the personal representative remains responsible to the bonding company. Personal representatives who stop short of the discharge sometimes find this out later, when a premium notice arrives or the surety will not release collateral.
Rule 5.400(e) provides that the court’s order discharges the personal representative and releases the surety on any bond. Where a successor personal representative was appointed during the administration, confirm how and when the predecessor’s surety is released; it does not necessarily happen at the same time as the successor’s discharge.
Personal representative compensation and attorney’s fees at closing
Florida sets presumptively reasonable compensation for the personal representative and for the attorney for the personal representative, with additional compensation available for extraordinary services. Both are disclosed in the petition for discharge, and both can be objected to. This section is about compensation at the closing stage; the overall cost of probate, court costs and flat-fee options are explained in how much probate costs in Florida.
The personal representative’s commission. Section 733.617(2) sets a presumptively reasonable commission on the compensable value of the estate: 3% of the first $1,000,000; 2.5% above $1,000,000 to $5,000,000; 2% above $5,000,000 to $10,000,000; and 1.5% above $10,000,000. Further reasonable compensation may be allowed for extraordinary services such as selling property, litigation, tax proceedings, running the decedent’s business or dealing with protected homestead. Any interested person may petition the court to increase or decrease the ordinary commission, and the court weighs the factors the statute lists. Executor fees in Florida are therefore a presumption, not a fixed price.
The attorney’s fee. Section 733.6171(3) sets a presumptively reasonable fee for ordinary services: $1,500 for an estate of $40,000 or less; an additional $750 above $40,000 to $70,000; an additional $750 above $70,000 to $100,000; 3% of the next $900,000; 2.5% above $1,000,000 to $3,000,000; 2% above $3,000,000 to $5,000,000; 1.5% above $5,000,000 to $10,000,000; and 1% above $10,000,000.
These figures are not a mandatory statutory fee. An attorney who charges on the schedule must disclose in writing that there is no mandatory statutory fee, that the fee need not be based on the size of the estate, that the fee is negotiable, that the personal representative chooses the attorney and need not use the attorney who prepared the will, and that the personal representative is entitled to a summary of ordinary and extraordinary services at the end of the representation. The attorney must obtain the personal representative’s signed acknowledgment of those disclosures; without them, the fee requires prior court approval or the written consent of all interested persons.
The base is narrower than people assume: compensable value is the inventory value of the probate assets plus income earned during the administration. Jointly held property, accounts with a named beneficiary and trust assets are not part of it.
Compensation a personal representative receives is generally taxable income to the personal representative for federal income tax purposes; a family member who is also a beneficiary may prefer to waive it, a question for a tax professional.
Can the personal representative be paid before the estate closes?
Compensation may be paid from estate assets without a prior court order under section 733.617(1), and attorney’s fees likewise under section 733.6171(1), except where the required disclosures were not made. Paying compensation before closing is not, by itself, a breach of duty. Every amount still has to be disclosed in the petition for discharge under Rule 5.400(b)(4), and it is subject to objection and court review under section 733.6175 and Rule 5.355, where the burden of showing that the compensation is reasonable is on the personal representative and the person employed. Excessive compensation can be ordered refunded.
Surcharge and what the personal representative remains exposed to
Surcharge is the remedy when a personal representative causes a loss to the estate through a breach of duty, such as self-dealing, an unjustified sale, unreasonable expenses, failing to preserve assets or distributing to the wrong person. The closing documents exist in the form they do for this reason: the accounting shows what happened, the objection period gives interested persons a chance to say it was wrong, and the discharge closes the question.
The situations that most often lead to surcharge claims at closing are distributing before claims were resolved and then facing a creditor, using estate property personally, selling an asset to a relative at a price nobody tested, and closing on a waiver obtained without telling the beneficiary what was being waived. An estate staying open, unequal shares or compensation paid before closing do not by themselves establish a breach.
Closing the estate bank account
How to close an estate account: closing the estate bank account is the last operational step, not the first. The account is closed after the final distributions have cleared, not before. Leave enough in it to cover the last filing costs, certified copies and any final tax payment, and close it once those have cleared.
Bank requirements vary. A bank may ask for distribution instructions, identification and sometimes a certified copy of the order of discharge or the letters of administration. Closing the account is not the same as the court’s discharge: an empty account does not close the estate.
The estate’s employer identification number is not “closed” the way an account is; it stops being used once the final fiduciary return is filed and marked final. For opening the account, what banks require after a death and how accounts pass outside probate, see a deceased person’s bank account in Florida.
Tax records and unresolved liabilities at closing
Florida does not currently collect an estate tax or an inheritance tax, but federal returns and any unresolved tax liability still matter at closing, because distributing everything before the tax position is settled can leave the personal representative exposed. Lorenzo Law does not prepare tax returns or give tax opinions; the personal representative’s tax professional handles the returns, and the closing plan is coordinated with that work.
| Form or document | What it is | When it matters at closing |
|---|---|---|
| Form 1041 | U.S. Income Tax Return for Estates and Trusts, the estate’s own income tax return, filed for each year the estate meets the filing threshold | The return for the estate’s last year is marked final; calendar-year or fiscal-year due dates follow the IRS instructions |
| Final Form 1040 (and Form 1310 if a refund is claimed) | The decedent’s final individual return; Form 1310 is used by some claimants of a refund due a deceased taxpayer | Due on the normal individual schedule; whether Form 1310 is needed depends on who files and claims the refund |
| Form 706 | United States Estate (and Generation-Skipping Transfer) Tax Return, filed when required or to elect portability | Generally due nine months after death, with an extension of time to file available; an extension to file is not an extension to pay |
| Estate tax closing letter | An IRS letter about the federal estate tax return; it is not the probate order of discharge | Requested only after the IRS conditions are met; a qualifying account transcript can be used instead |
| Account transcript | The IRS record of the estate tax account | A transcript showing the return was accepted can substitute for the closing letter |
| Form 56 | Notice concerning a fiduciary relationship | Filed when the fiduciary relationship begins and, where appropriate, when it ends |
An IRS estate tax closing letter concerns the federal estate tax return; it is not the Florida probate discharge order. Current IRS instructions allow a request once transaction code 421 is shown on the account transcript; otherwise the IRS generally directs waiting at least nine months after the return is filed, or 30 days after an examination is completed. Whether an estate needs that evidence before distribution or discharge depends on the circumstances and any court requirements.
Whether to hold the estate open until the tax position is confirmed, or to close and distribute with a reserve, is a judgment that depends on the size of the estate, whether a Form 706 was filed and how much risk the personal representative is willing to carry.
The estate’s tax year and the final Form 1041
An estate may choose a fiscal year rather than the calendar year when it applies for its employer identification number (EIN); the IRS form asks for the “closing month of accounting year,” the closing month of the estate’s accounting year. The choice affects when each Form 1041 is due and which year is the final one. Ask the estate’s tax professional before closing which year’s return will be marked final and whether income distributed to beneficiaries in that year will be reported to them.
Other liabilities to check before distribution
Before distribution, also consider whether the estate faces a Medicaid estate recovery claim by the Agency for Health Care Administration, a claim by another government agency, a child support lien or a federal tax lien. Under section 198.32(3), most estates need no Florida “no estate tax due” affidavit; a title examiner on a later sale may still ask what was filed. For the broader tax picture, see Florida inheritance tax.
Closing a summary administration is different
Summary administration is not closed the way a formal administration is. There is ordinarily no personal representative to discharge: the proceeding is concluded by the order of summary administration itself, which directs who receives what. A summary administration requires no final accounting, no petition for discharge and no order of discharge. It begins with a petition under section 735.203 and ends with an order under section 735.206.
Summary administration is available when the value of the Florida estate subject to administration, less exempt property, does not exceed $150,000, or the decedent has been dead more than two years, and any will does not direct formal administration. The limit was raised to $150,000 effective July 1, 2026. If the death occurred before that date, confirm which limit applies before filing. Eligibility is explained in the summary administration guide.
The trade-off is creditor exposure. People who receive property under an order of summary administration can be personally liable, up to the value each received, for lawful claims against the estate, until those claims are barred. Section 735.2063 allows notice to creditors to be published in a summary administration. See also when probate is not necessary in Florida.
Closing an ancillary Florida estate
When a person domiciled in another state or country dies owning Florida property, the Florida case is often an ancillary administration running alongside the main estate at home. The Florida ancillary personal representative still accounts for what came in and went out in Florida, still deals with Florida creditors and still needs a Florida discharge. Coordinating the two proceedings so that neither closes before the other is ready is most of the work.
Section 734.102(4) requires ancillary proceedings to be as similar to an original administration as possible, so the ancillary personal representative files a final accounting and petition for discharge, serves the interested persons and obtains a Florida order of discharge.
Where the Florida residue goes. After expenses of administration and claims are paid, the court may order the remaining Florida property transferred to the foreign personal representative or distributed to the beneficiaries. It turns on the will, what the parties want and what the court considers appropriate; expenses and claims come first.
The short form. Section 734.1025 offers a shorter procedure for a nonresident who died with a will and Florida property with a gross value at death of $50,000 or less: the foreign personal representative files authenticated copies of the domiciliary proceedings, before two years after death, without a full ancillary administration. Whether a Florida personal representative is appointed or a discharge order is entered depends on what happens in that procedure, including whether a claim is filed. More on ancillary probate in Florida and serving as an out-of-state executor.
Insolvent estates, a personal representative who leaves, and assets in a trust
Closing an estate that cannot pay everyone
Who gets paid first out of an estate? When the estate cannot pay every claim and expense in full, Florida law sets the order of payment, and the beneficiaries are paid only after the classes ahead of them. The plan of distribution and the petition for discharge then show how the available funds were applied, and some circuits ask for a petition and order declaring the estate insolvent, served on the outstanding creditors, before the discharge. The payment classes are explained in Florida probate creditor claims and what happens to your debt when you die in Florida.
If the personal representative dies, resigns or is removed before closing
The estate does not close because the personal representative is gone. A personal representative may resign only with court approval, and a resigning or removed personal representative must account and deliver the estate’s records and property to the successor. A successor personal representative then finishes the administration and files the closing papers. If the personal representative died, the court appoints a successor, and the deceased personal representative’s own estate may be asked to account for the period he or she served.
If the assets are in a trust
Assets held in a funded revocable trust usually pass under the trust, not through probate, and closing out a trust after death is a different process: the trustee administers and distributes under the trust document and Florida trust law, generally without a court order of discharge. Many families have both: a small probate estate that pours into the trust, and the trust itself. Closing the probate estate does not close the trust, and the trust may have its own accountings. Lorenzo Law handles trust administration as well as probate.
Reopening a closed estate in Florida
A closed Florida estate can be reopened. The usual vehicle is subsequent administration, which exists because assets and documents surface after the estate is closed.
Why would an estate be reopened? Common reasons:
- After-discovered assets: an old bank account, an unclaimed property record, a forgotten insurance policy, a mineral interest, a class-action settlement or a refund check that arrives years later.
- An unfinished matter: an asset that was never actually transferred, a deed that was never recorded or an unsatisfied obligation.
- A need for someone with authority: a buyer, title company or transfer agent requires a personal representative who no longer exists because the estate closed.
If the discovered asset is unclaimed property held by the State of Florida, start with unclaimed property in Florida; sometimes the answer is a claim rather than a reopened estate.
Section 733.903 provides that the final settlement of an estate and the discharge of the personal representative do not prevent further administration. Under Rule 5.460, if additional property is discovered after the estate is closed, or if further administration is required for any other reason, any interested person may petition for further administration.
| Question | Short answer |
|---|---|
| Who may ask | Any interested person |
| Time limit | None stated in the statute or the rule; but the two-year limit in section 733.710 keeps barring new creditor claims whether or not the estate is reopened |
| Is the discharge undone? | Not necessarily. The court enters the orders that are appropriate and, unless required, need not revoke the order of discharge, reissue letters or require a bond |
| Does the creditor period start again? | No. The two-year period runs from death, and reopening does not restart it |
| Is a second discharge needed? | Where letters are reissued and real administration follows, the estate is closed again in the ordinary way |
| What about a will found later? | Section 733.903 provides that the order of discharge may not be revoked based on the discovery of a will or a later will |
Finding a will after discharge is therefore not, by itself, a reason to revoke the discharge. The word discovery matters: in Gilbert v. Riley, 431 So. 3d 588 (Fla. 3d DCA 2026), the later will was already in the court file months before the discharge.
Fraud, bad faith and procedural irregularity
Beyond after-discovered assets, Florida courts have allowed an estate to be reopened after discharge where there were procedural irregularities or facts constituting fraud or bad faith. Carraway v. Carraway, 883 So. 2d 834, 835 (Fla. 1st DCA 2004). A court erred in refusing to reopen where a surviving spouse alleged that the personal representative had withheld material information it had a duty to disclose about the surviving spouse’s rights. Udell v. Udell, 397 So. 3d 1050, 1053 (Fla. 4th DCA 2024). The trial court has broad discretion over whether to reopen. Gilbert v. Riley, 431 So. 3d 588, 591–92 (Fla. 3d DCA 2026).
Fraud has to be alleged. In Gilbert, the objecting heir complained that the wrong will had been probated but never expressly alleged fraud, and lost on that ground among others. A petition to undo a discharge should expressly allege the fraud relied on.
A late creditor claim after the estate closed
A creditor who appears after distribution raises three separate questions with different answers: whether the claim is still alive, whether the personal representative is personally liable and whether the creditor can pursue the beneficiaries.
Is the claim still alive? A claim not filed within the period in section 733.702 is barred unless the court extended the time, and section 733.710 bars claims after two years from death, except for timely filed claims that remain unresolved and for recorded mortgages, security interests and certain liens. Whether a demand is a “claim” at all can matter: in a 2026 Fifth District decision, a company’s action to recover its own equipment that was in the decedent’s possession at death was held not to be a claim subject to the three-month filing requirement. The full treatment is in Florida probate creditor claims.
Is the personal representative personally liable? Generally not, where the claims procedures were followed and distribution was made under the plan. Section 733.619(2) makes a personal representative individually liable for obligations arising from ownership or control of the estate, or for torts in the course of administration, only if personally at fault.
Can the creditor pursue the beneficiaries? Within limits. Under section 733.812, a distributee who was improperly paid must return the assets plus income or interest, or their value, unless the distribution can no longer be questioned because of adjudication, estoppel or limitations. Section 733.811 protects a distributee’s title against other persons interested in the estate, subject to recovery of an improper distribution.
Before closing, a personal representative can protect against later claims with a reserve, a refunding agreement taken from the distributees as a condition of distribution, or a written agreement among the interested persons under section 733.815, subject to the rights of creditors and taxing authorities. Under section 733.705, the court may require assets to be reserved for unmatured or contingent claims before discharge. Each protection has limits.
When a beneficiary will not sign
A beneficiary who will not sign a waiver or a receipt is not a dead end, and it is not a reason to leave the estate open for years. It is a fork in the road.
- Will not sign the waiver of accounting. Prepare the accounting, serve it and let the objection period run. This route works whether or not everyone cooperates.
- Has been paid but will not sign the receipt. Determine what other proof of distribution the court will accept, such as the cleared check, the wire confirmation or the recorded deed, and explain the missing receipt to the court.
- Will not accept the distribution at all. Section 733.816 provides a court-directed process for property the owner refuses after a reasonable attempt and notice; a formal disclaimer may also be what the beneficiary actually wants.
- Will not sign and will not say why. Serve everything properly and let the periods run. Silence is not an objection.
A refusal to sign is different from an objection on the merits. A beneficiary who objects to an amount or an entitlement is raising a dispute that the court resolves; a beneficiary who simply does not return paperwork is a procedural problem with a procedural answer. What a particular judge will accept in place of a signed receipt is worth confirming in the circuit where the estate is pending.
When a beneficiary cannot be found
A missing beneficiary calls for a documented, diligent search: last known addresses, relatives, former employers, public records, mail and professional locator services. Keep the search records and the record of each attempted distribution.
Section 733.816 addresses property that cannot be distributed because the lawful owner cannot be found, is unknown or refuses it after a reasonable attempt and notice. It provides a court-directed process for sale and deposit of the funds with the clerk, followed by statutory notice and handling of unclaimed funds. Obtain the court’s direction before treating a deposit as a completed distribution. That is different from concluding that the decedent has no lawful heirs, and an informal transfer to the clerk or an assumption of escheat is not a substitute for the statutory process.
When a beneficiary is a minor or incapacitated
Before distributing a minor beneficiary’s inheritance, or an incapacitated adult’s, identify who has legal authority to receive the property and sign for it.
Section 744.301 permits a natural guardian, ordinarily a parent, to receive specified property for a minor within its aggregate limit, which is $15,000. Larger distributions or other circumstances may require a guardian of the property, or a properly authorized trust, custodial or other arrangement. A parent, relative or caregiver should not be assumed to have authority solely because of the relationship. A receipt signed by the minor personally is not a reliable acknowledgment. For an incapacitated adult, an existing guardianship or other legal authority usually controls who may receive and sign.
A pending guardianship can affect timing, because the court looks for evidence that the estate was properly distributed, and a distribution to a minor is not complete until someone with authority receives it. Depending on the facts, options include a partial distribution to the other beneficiaries, an extension of the closing deadline or another court-approved arrangement. Have counsel review the governing document, the amount, the recipient’s capacity and any existing order.
Why Florida estates stall at closing, and when a delay is a dispute
Why does it take so long to close an estate? Usually because one task is unfinished, not because of the paperwork. An estate remaining open does not by itself establish misconduct. Ask what specific task remains, who is responsible for it and what document will show it is complete. A request for information does not stop a deadline from running.
| The delay | What usually clears it |
|---|---|
| Real property that has not sold | A decision to keep marketing it, sell on new terms or distribute it in kind |
| An unresolved creditor claim | Payment, settlement, or an objection and the claimant’s failure to bring an independent action in time |
| Homestead status not determined | A petition and order, where the title and plan require one |
| Tax position unsettled | Final returns filed; a decision whether to hold the estate open or close with a reserve |
| A beneficiary will not sign a waiver | The accounting route: prepare, serve and let the objection period run |
| A beneficiary cannot be located | A documented search, then the court-directed process in section 733.816 |
| Pending litigation involving the estate | Resolution, or court-approved provision for it |
| A minor or incapacitated distributee | A person or arrangement with legal authority to receive the property |
| An accounting that will not reconcile | Rebuilding it from the bank and transfer records rather than patching it |
| The personal representative has stopped responding | A request to the court to compel action, or removal and a successor if grounds exist |
Delay or dispute? Signs that an open estate needs a closer look
| What you know | What it may mean | Record or next step |
|---|---|---|
| A tax issue remains, and a written status or extension explains it | An identified dependency, not by itself evidence of wrongdoing | Tax correspondence, a reserve proposal and any extension order |
| The final accounting does not reconcile | Error or incomplete records; intent cannot be inferred from the discrepancy alone | Identify the transaction, the amount and the supporting statement |
| A beneficiary declines a waiver | A request for formal review, not obstruction | Whether a compliant accounting can be prepared and served |
| Money appears to be missing, an insider transaction is unexplained, or a court order is ignored | A possible breach that needs legal assessment | The relevant documents, transaction dates, orders and the resulting loss |
| An accounting or petition for discharge was just served | A time-sensitive review, even if discussions continue | Keep the document and the service record; get advice promptly |
| The docket says closed but no order of discharge can be found | Administrative status may differ from the personal representative’s discharge | Ask for the actual order and identify the procedure used |
If records suggest a breach, remedies may include an accounting, an objection, compulsory payment where its conditions are met, removal on established grounds or surcharge for a proven loss. The right remedy depends on the evidence, standing and the stage of the case. Two hypothetical examples: a documented pending tax determination with an extension order can explain a long delay even when every beneficiary agrees on the shares; a missing transfer combined with an ignored court order calls for a different inquiry even if only a few months have passed. Neither example predicts a result or describes a client matter.
Chart: Stuck, or something wrong
What a personal representative may not do at the closing stage
At closing, a personal representative may not:
- Distribute before claims, taxes and expenses are paid or provided for, without accepting the risk that creates.
- Favor one beneficiary over another contrary to the will or the law.
- Mix estate money with personal money or use estate property personally.
- Leave compensation undisclosed in the petition for discharge.
- Ask a beneficiary to sign a receipt for property not yet delivered, or obtain a waiver without the disclosure the beneficiary needs.
- Stop at distribution and never obtain the order of discharge.
How long can a Florida estate stay open?
No statute closes a Florida estate automatically after a set time. The personal representative must file the final accounting and petition for discharge within 12 months after letters are issued, or within 12 months after a federal estate tax return is due, unless the court extends the time. After that, how long the estate stays open depends on the unfinished task, not on the calendar. There is no reliable average time to close an estate; the remaining task, not the calendar, controls. A formal administration does not ever close by itself; it closes when the court enters the order of discharge.
What controls when a Florida estate is ready for discharge
| Situation | What controls readiness for discharge |
|---|---|
| Records complete and valid waivers available | Remaining obligations, proper distribution, a complete filing and the court’s processing |
| Final accounting served without waivers | The objection period, service and proof of distribution |
| An objection or a disputed share | Resolution of the issue and carrying out the court’s plan |
| A tax, claim or asset issue unresolved | Lawful resolution, or approved provision for that issue |
| A missing recipient, or one who cannot legally receive the property | Authority to receive the property, or a court-directed alternative |
A filing deadline, a creditor period or an objection period is not an estimate of the court’s turnaround. For the stages before closing and the whole timeline, see how long probate takes in Florida. Many uncontested formal administrations take roughly six months to a year from start to finish.
How do you find out whether a Florida estate is closed?
Look for an order of discharge in the court file. In a formal administration, that order is what closes the estate; a docket status of “closed” is an administrative label and does not always mean the personal representative was discharged.
- Find the case. Probate cases are filed with the Clerk of the Circuit Court in the county where the estate is pending, usually the county where the decedent was domiciled. Each clerk offers an online search of court records by the decedent’s name or case number; some documents may require registration or a request to the clerk.
- Read the docket. Look for entries such as “petition for discharge,” “final accounting,” “waiver,” “receipt” and “order of discharge.” Note the dates. Florida law bars posting images of probate court records on a public website, so the online docket often lists a filing without showing it; request a copy from the clerk.
- Look for the order itself. An entered order of discharge, or in a summary administration the order of summary administration, is what you are looking for.
- Know what you will not see. Inventories and accountings are confidential; an interested person can obtain them, but they are not ordinarily open to the public. Property that passed outside probate, such as a trust, a jointly held account or an account with a named beneficiary, does not appear in the probate file at all.
- If the case shows as administratively closed without an order of discharge, treat the administration as unfinished: an administrative or inactive status on the docket does not discharge the personal representative.
- If no order exists, the administration is still open even if the assets were distributed. An interested person can ask the personal representative for the status or ask the court to require the closing papers.
A beneficiary who has been told the estate is “settled” can ask for a copy of the order of discharge. If none was entered, the personal representative has not been discharged.
If you are a beneficiary and the estate will not close
Much of what is written about closing an estate is aimed at the personal representative. This section is for beneficiaries who have been waiting and are not getting answers, including those who think an executor is delaying distribution or taking too long to settle or close the estate. You do not have to wait 12 months to get advice, and you do not have to wait for the personal representative to act.
- Ask for information. An interested person may ask for information about the administration. A written request is the first step, and it creates a record.
- Petition to compel payment. Florida has a proceeding for compulsory payment of a devise or distributive interest when the estate is in a position to pay.
- Object to the accounting or the petition for discharge when it is served, within the period and with particularity.
- Ask the court to remove the executor (the personal representative) on a ground the statute recognizes, including when the executor refuses to act, ignores a court order or is using estate money as if it were the personal representative’s own, which is what people mean when they say an executor is stealing from the estate.
- Seek surcharge for a loss caused by a breach of duty.
Signing a waiver of accounting just to “move things along” gives up the most detailed look at the administration; ask for the numbers first.
Compelling payment. Under section 733.802(1) and Rule 5.380, before final distribution a personal representative cannot be compelled to pay a devise or distributive share, deliver specific property or surrender land unless the beneficiary establishes that the property will not be needed for debts, family allowance, estate and inheritance taxes, claims, the elective share, charges or expenses of administration. The burden is on the beneficiary. If the court is satisfied, it may order payment or delivery before final settlement and may require the beneficiary to post a bond.
Getting an accounting. Rule 5.345 lets the court require an interim or supplemental accounting, and Rule 5.400 requires the final accounting to be served on the interested persons.
Removal. Section 733.504 lists the causes for removal, including failure to comply with a court order and failure to account for the sale of property or to produce the assets of the estate when required. Any interested person may petition, and the court may act on its own motion. A removed personal representative must account and deliver the estate’s records and property to the successor. Elapsed time alone is not an automatic ground.
Surcharge. The standard is breach of fiduciary duty under section 733.609(1): liability to interested persons for damage or loss resulting from the breach. Admitted misadministration can shift the burden of going forward with the evidence to the personal representative. Rich v. Narog, 366 So. 3d 1111 (Fla. 3d DCA 2022). Liability is limited to the actual damage or loss caused by the breach. Brush v. Coppelli, 407 So. 3d 518, 518–19 (Fla. 5th DCA 2025). A testamentary trust beneficiary is an interested person with standing to seek surcharge and to contest the discharge. Carmel v. Fleischer, 391 So. 3d 907, 910–11 (Fla. 4th DCA 2024). A surcharge against the personal representative individually, or a petition to recover fees already paid, is an adversary proceeding requiring formal notice on that person individually. Kozinski v. Stabenow, 152 So. 3d 650, 653–54 (Fla. 4th DCA 2014); Simmons v. Estate of Baranowitz, 189 So. 3d 819, 821–22 (Fla. 4th DCA 2015).
If the problem runs deeper than delay, see Florida probate litigation and Florida estate litigation.
A 2026 case: how quickly a beneficiary’s objection can come too late
Gilbert v. Riley, 431 So. 3d 588 (Fla. 3d DCA 2026), shows how quickly the closing stage can move. According to the opinion, the personal representative petitioned to administer his mother’s estate in February 2024 with a copy of a 2000 will naming him sole beneficiary, offered as lost or destroyed; a week later a 2014 will naming all of the children equally was placed in the court file. Over the next weeks he obtained defaults against family members, an order admitting the 2000 will and an order determining homestead, and on 7 May he filed a petition for discharge; the order of discharge was entered the next day. A daughter objected nine days later, waited months to petition to reopen, missed a court deadline to set a hearing, did not expressly allege fraud and had no transcript of the hearing she eventually had. The Third District affirmed.
The lessons are practical: a served notice starts a period whether or not the recipient understands it; a default is not a formality; an objection has to be filed in writing, in time; a complaint that something was concealed has to say so in the pleading; and an inadequate record can prevent meaningful review of fact-dependent issues on appeal. A beneficiary who thinks something is wrong should not wait to be invited.
What does it cost to close an estate in Florida?
How much a lawyer charges to close or settle an estate in Florida depends on the route and on what remains to be done. The closing stage has three cost components: the professional time to prepare and file the closing papers, court costs and certified copies, and, where a formal accounting is required, the time to build the accounting. The accounting is the variable item. An estate with one bank account and two beneficiaries is a different exercise from one with a business interest, three properties and eighteen months of transactions. That is why closing on waivers can save money when it is genuinely available, and why it is a false economy when it is not.
Court filing fees and certified-copy charges are set by law and published by the Clerk of the Circuit Court in each county; check the current schedule for the county where the estate is pending. Statutory compensation presumptions are explained in compensation and fees at closing, and the overall cost of probate in how much probate costs in Florida.
Lorenzo Law’s fees at the closing stage
- An estate Lorenzo Law handles from the start: summary administration starts at $3,975 and includes the filing fee and certified copies of the order; Lorenzo Law does not publish the optional notice to creditors in summary administration, so there is no publication cost. Uncontested formal administration starts at $7,975 and includes the filing fee, creditor-notice publication and certified copies. Ancillary administration is quoted per matter. For either procedure, homestead determinations, more complex estates and contested matters are quoted separately, and other expenses may apply, such as recording fees or the decedent’s debts, and in formal administration a personal representative’s bond if the court requires one and the personal representative’s compensation; any increase is discussed before work begins.
- An estate stuck at closing, started by someone else: Jose takes over probate matters from other lawyers partway through a case, depending on the facts and position of the case; the scope and fee are discussed at the consultation and agreed in writing.
- A beneficiary reviewing an accounting, a waiver or a release: a paid hourly engagement for the beneficiary’s own matter; the rate is agreed in writing.
The flat fee is generally paid near the close of the matter; whether the client advances any cost is discussed in advance, and when the estate has no cash, for example when the home is the only asset, the client pays the flat fee. The written engagement names the client, the work, the fee and any cost not included. The published flat fees are honored at least through February 17, 2027. Only the initial consultation is free; representation fees and costs are agreed separately in writing.
Can you close an estate in Florida without a lawyer?
Generally no, if a personal representative has been appointed, whether the question is closing or settling an estate in Florida. Florida Probate Rule 5.030 requires a personal representative to be represented by an attorney, with two exceptions: a personal representative who is the sole interested person, and one who is a member of The Florida Bar.
There is no exception for summary administration or disposition without administration because those procedures do not appoint a personal representative in the first place; they can be pursued without a lawyer. See do I need a probate attorney in Florida.
Where closings go wrong is rarely the filing itself. It is the judgment around it:
- Downloaded documents. What circulates online as a “Florida petition for discharge form” may be a circuit-created document, a commercial product or another state’s paperwork. A document that looks right can still omit a statement Rule 5.400 requires and invite a challenge. Lorenzo Law does not provide fill-in forms.
- Distributing too early. Distributing before claims and taxes are resolved shifts risk to the personal representative personally.
- Waivers obtained without disclosure. A waiver signed by a beneficiary who was never shown the numbers is the one most likely to be challenged later.
- Undisclosed compensation. Compensation that is not disclosed in the petition invites an objection.
- Stopping at distribution. Paying everyone and never obtaining the order of discharge leaves the personal representative in office.
Closing practice across Florida’s circuits
Rules 5.400 and 5.401 apply statewide, Florida probate filings are made electronically through the statewide portal, and many uncontested closings do not require a hearing. What changes from one circuit to the next is what the probate division expects to see with the closing papers: several circuits publish closing or discharge checklists, and some require a completed checklist with the petition. Check the assigned division’s current instructions before filing. Lorenzo Law handles probate matters in every Florida county by phone or video; not every court step can be done remotely, and the assigned judge’s procedures control.
| Circuit (counties) | What the circuit publishes about closing | Where to check |
|---|---|---|
| Eleventh (Miami-Dade) | Required Probate Smart Forms for proposed orders, including the order of discharge, and the rule that proposed orders identify the filing they rely on | Eleventh Judicial Circuit, Probate Smart Forms |
| Seventeenth (Broward) | Local procedures for the Probate Division and a set of mandatory checklists | Seventeenth Judicial Circuit, Probate |
| Fifteenth (Palm Beach) | An approved checklist for the petition for discharge, to be completed and e-filed with the petition | Fifteenth Judicial Circuit, Probate Division |
| Ninth (Orange, Osceola) | Its 2021 order mandating estate certification checklists in Orange County is listed as vacated; confirm the division’s current requirements before filing | Ninth Judicial Circuit |
| Fifth (Lake, Marion, Sumter, Citrus, Hernando) | County-specific checklists for closing formal administration | Fifth Judicial Circuit |
| Twentieth (Lee, Collier, Charlotte, Glades, Hendry) | Administrative orders on probate matters; confirm any county checklist requirement with the assigned division before filing | Twentieth Judicial Circuit, administrative orders |
| All other circuits | The assigned division’s instructions and any administrative orders | The circuit’s probate page and the county Clerk |
Miami-Dade County (Eleventh Judicial Circuit)
Miami-Dade estates are filed in the probate division of the Eleventh Judicial Circuit. Complete closing packages, with every order the plan depends on, avoid a return trip; when a Miami-Dade residence may be protected homestead, settle its status before the plan of distribution is served. Lorenzo Law meets clients by appointment in Coral Gables. More on Miami probate.
Broward County (Seventeenth Judicial Circuit)
Broward’s Probate Division publishes a closing-document list in its local procedures. It includes items such as the inventory, proof of the notice to creditors, claim-resolution records, the accounting or waivers, distribution documents and discharge papers, with tax and agency-notice requirements where they apply. Check the court’s current instructions and the assigned division before submitting a package; the published list supplements the statewide rules and is not a promise about processing time. Lorenzo Law meets clients by appointment in Fort Lauderdale. More on Broward probate.
Palm Beach County (Fifteenth Judicial Circuit)
In Palm Beach County, an administrative order requires the circuit’s petition for discharge checklist to be completed and filed with the petition, and petitions filed without it may be rejected with leave to refile. Proposed orders go through the circuit’s online scheduling system. Where the estate filed a federal estate tax return, the closing timeline is often set by the tax position rather than by the court.
Lee, Collier and Southwest Florida (Twentieth Judicial Circuit)
The Twentieth Judicial Circuit covers Lee, Collier, Charlotte, Glades and Hendry counties; check the assigned division’s current instructions, including any checklist requirement, before filing the closing papers. Estates of seasonal residents and owners domiciled in another state raise the ancillary administration question early, and condominium or deed-restricted property can affect how a distribution in kind is carried out.
Orlando and Central Florida
Orange and Osceola counties are in the Ninth Judicial Circuit, whose 2021 Orange County checklist order is now listed as vacated, so the division’s current instructions control; Seminole is in the Eighteenth Circuit and Lake is in the Fifth, each with its own instructions. Lorenzo Law’s principal office is in Kissimmee. See Orlando probate and the Orange County probate court.
Every other Florida county
The same statewide rules apply in all 67 counties, including Pinellas, Hillsborough, Pasco, Manatee, Sarasota, Duval, St. Johns, Alachua, Leon, Escambia, Marion, Volusia, Brevard, Polk, Monroe, Martin, St. Lucie, Indian River, Hernando, Citrus and Sumter. Check the assigned division’s current instructions and any administrative orders for the county where the estate is pending. See the Florida probate service areas.
Getting help at the closing stage
Jose M. Lorenzo, Jr. is a solo practitioner. The attorney who takes the first call is the attorney who handles any matter the firm accepts, including the final accounting and the petition for discharge, from the first call to the order of discharge. That continuity matters most at closing, when the person signing the petition needs to know what happened months earlier in the administration.
- Personal representatives whose estate is ready to close, or stuck: bring the letters of administration, the inventory, the bank statements, the claims status and whatever was filed last.
- Personal representatives whose lawyer has withdrawn or gone quiet: Jose takes over probate matters partway through a case, depending on the facts and position of the case; that is discussed at the consultation.
- Beneficiaries asked to sign a waiver, a receipt or a release, or reviewing a final accounting: Jose represents beneficiaries in their own matters as a paid engagement. The personal representative’s lawyer does not represent the beneficiaries.
An initial consultation can help identify the issue that needs review and the information needed for the next step. Have the county, the case number, your role, the latest filing and any service dates available. Do not send account numbers or other sensitive details through the contact form.
Comparing Florida probate attorneys for a closing? Ask each one who will actually prepare the accounting and what happens if a beneficiary refuses to sign. More questions are in how to choose a Florida probate lawyer.
More questions about closing an estate in Florida
How long does an executor have to settle an estate in Florida?
In a Florida formal administration, the personal representative (the executor) must file and serve the final accounting and petition for discharge within 12 months after letters of administration are issued if the estate is not filing a federal estate tax return, or within 12 months after the federal estate tax return is due if it is. The court can extend that time for cause after notice to the interested persons. The deadline is for filing the closing papers; it is not a promise of when the court will sign the order of discharge, and missing it does not close the estate.
Is settling an estate the same as closing it?
Settling an estate usually means the whole administration, from opening the probate case through paying claims and distributing the assets. Closing is the last part: in a Florida formal administration, the estate is closed when the court enters the order discharging the personal representative, after the final accounting or waivers, the petition for discharge and proof of distribution. Paying the beneficiaries settles their shares but does not, by itself, close the estate.
What happens if an estate is never closed?
The personal representative remains in office and responsible, any bond stays in place, the estate keeps incurring costs and nothing about the administration becomes final. An interested person can ask the personal representative for the status, ask the court to require the closing papers or an accounting, petition to compel payment where its conditions are met, or seek removal on a ground the statute recognizes.
What documents are needed to close an estate in Florida?
In a formal administration: proof that the creditor period ran and every claim was resolved or provided for; the tax filings and any tax correspondence; any homestead, exempt property or elective share orders; the final accounting or signed waivers of it; the petition for discharge with a plan of distribution; proof of service; receipts or other proof of distribution; and the order of discharge. Some circuits also require a completed closing or discharge checklist with the petition.
Does the executor have to provide a final accounting?
Yes, unless the interested persons validly waive it. The final accounting is filed and served on the interested persons with the petition for discharge, and each has 30 days after service of the later of the two documents to object. A waiver gives up the accounting right it describes; it is not automatically a consent to discharge or a receipt.
Does an executor have to show the accounting to beneficiaries in Florida?
The final accounting is served on the interested persons, which normally includes beneficiaries whose shares depend on it, unless they waive it. A beneficiary who has already received a complete distribution is not an interested person for that purpose. Accountings are confidential under section 733.604, so the public cannot see them without a court order, but the persons the statute lists can.
Can a beneficiary demand an accounting in Florida?
A beneficiary who is an interested person can ask the personal representative in writing for information about the administration, and can ask the court to require an interim or supplemental accounting under Florida Probate Rule 5.345. At closing, the beneficiary receives the final accounting unless he or she waives it. A written request creates a record if court action is needed later.
What does a waiver of accounting mean?
It means the signer gives up the right described in the waiver, usually the right to receive a formal, verified final accounting, so the estate can close without one. Under Rule 5.180, the waiver must be written, signed and filed and must state expressly what is waived; a compensation waiver must also confirm knowledge of the amount and method and agreement or waiver of court review. It is separate from a consent to discharge and from a receipt, even when one form contains all three.
Does an executor have to provide receipts?
The personal representative usually obtains receipts from beneficiaries as proof that distributions were made, because the court enters the discharge on evidence of proper distribution. If a beneficiary will not sign, other proof such as a cleared payment or a recorded deed may be offered, subject to the court’s direction. Separately, the payments in the accounting should be supported by records that an interested person may ask to see.
When can an executor start distributing assets?
Distribution is safest after the creditor period has ended and claims, taxes and expenses have been paid or provided for. Earlier partial distributions are possible, but they shift risk to the personal representative if a claim or expense appears later, and assets distributed early can be hard to recover.
Can a beneficiary object to a petition for discharge?
Yes. An interested person may file and serve a written objection within 30 days after being served with the later of the petition for discharge or the final accounting, stating with particularity the items objected to and the grounds. Notice of a hearing on the objection must be served within 90 days after it is filed, or the objection is treated as abandoned; the 90-day rule concerns serving the notice, not the hearing date.
Does the order of discharge protect the personal representative personally?
Under section 733.901(2), the discharge releases the personal representative and bars actions against the personal representative, as such or individually, and the surety on any bond. Florida courts recognize limits, including where the personal representative concealed what it did with an estate asset, and a lawful subsequent administration can still occur.
Can a personal representative be sued after discharge?
Can you sue an executor after the estate is closed? It is difficult: the discharge is meant to close the question and usually does, but it is not absolute. A claim based on concealment or fraud may survive, and the procedure and timing for such a challenge depend on the facts, so both sides should get advice promptly. An accounting that was merely inaccurate is generally covered by the discharge; one that hid a disposition may not be.
Can a closed estate be reopened in Florida?
Yes. Under section 733.903 and Florida Probate Rule 5.460, any interested person may petition for further administration if property is discovered after the estate closes or further administration is needed for another reason. The court need not revoke the discharge or reissue letters unless that is required, and the discovery of a will or a later will does not by itself allow the discharge to be revoked.
What if another bank account is found after the estate closed?
That is the typical after-discovered asset. Depending on what it is and how it was titled, the answer may be a petition for subsequent administration, a transfer to the beneficiary named on the account, or a claim through Florida’s unclaimed property program if the State already holds the money.
What if a creditor shows up after the estate is closed?
Three questions arise: whether the claim is barred, whether the personal representative is personally liable and whether the creditor can pursue the beneficiaries. A claim not filed in time under section 733.702 is generally barred, and section 733.710 bars claims two years after death except timely filed claims still unresolved and certain liens. A personal representative who followed the claims procedures is generally not personally liable, while section 733.812 can require a distributee who was improperly paid to return the property or its value.
What can a beneficiary do if the executor is not paying beneficiaries?
Start by asking in writing what remains unfinished and when it will be done. If the estate is in a position to pay, a beneficiary can petition to compel payment under section 733.802 and Rule 5.380 by showing the property is not needed for debts, taxes, claims, family entitlements or expenses. If records suggest missing money, an ignored order or self-dealing, an objection, removal or surcharge may be available, depending on the evidence.
How much does a personal representative get paid in Florida?
Section 733.617(2) sets a presumptively reasonable commission on the compensable value of the probate estate: 3% of the first $1,000,000, then 2.5%, 2% and 1.5% on the higher tiers, with further compensation available for extraordinary services. The amount is disclosed in the petition for discharge, and any interested person may ask the court to increase or decrease it.
Does an estate have to file a final Form 1041?
An estate files Form 1041 for each tax year in which it meets the IRS filing threshold, and the return for the last year is marked as the final return. The due date depends on whether the estate uses the calendar year or a fiscal year it chose when it obtained its employer identification number. The estate’s tax professional prepares the returns; Lorenzo Law does not.
Do I need an IRS estate tax closing letter before closing the estate?
Only estates that file a federal estate tax return (Form 706) have a closing letter to consider. Where one was filed, the IRS allows a closing letter to be requested once the account transcript shows the return was accepted, or otherwise generally at least nine months after filing, and a qualifying account transcript can be used instead of the letter. Whether to wait for that confirmation or close with a reserve depends on the estate.
When can the estate bank account be closed?
After the final distributions have cleared and any last filing cost, certified copy or tax payment has been paid. Banks set their own requirements; some ask for identification and a certified copy of the letters of administration or the order of discharge. Closing the account does not close the estate; the court’s order of discharge does.
Can the estate close if the house has not sold?
Often yes, by distributing the property in kind to the beneficiaries rather than waiting for a sale, if the will, the beneficiaries’ wishes and any mortgage or other encumbrance allow it. If the house is protected homestead, it generally passes outside the personal representative’s control and is not distributed as an estate asset.
Can an estate close while a lawsuit is still pending?
A lawsuit by or against the estate usually has to be resolved, or provided for in a way the court approves, before the personal representative can state that the estate is fully administered.
Can a Florida estate be closed from out of state?
Often yes. Florida probate filings are electronic, many uncontested closings do not need a hearing, and a personal representative who lives in another state can sign and return documents remotely. Some steps, such as original documents, a contested hearing or the assigned judge’s procedures, may require other arrangements. See serving as an out-of-state executor in Florida.
How do I force an executor to close an estate?
Ask in writing for the status and for the closing papers, which also creates a record. If the 12-month deadline has passed without an extension, an interested person can ask the court to require the final accounting and petition for discharge. Florida also provides a proceeding to compel payment under section 733.802 and Rule 5.380, and removal under section 733.504 for failure to comply with a court order or failure to account, among other grounds.
How long should estate records be kept after the estate is closed?
Keep the final accounting, the receipts, the bank records, the tax returns and a certified copy of the order of discharge for as long as anyone could question the administration or a tax year could be reviewed. They are difficult to reconstruct once accounts are closed, and the estate’s tax professional can say how long the tax records should be kept.
What is the 10-day rule for probate in Florida?
It is the requirement in section 732.901 that the custodian of a decedent’s original will deposit it with the clerk of the court where the estate is administered within 10 days after learning of the death. It applies at the start of probate, not at closing; the steps are explained in the Florida probate process guide.
Can Lorenzo Law take over an estate that is stuck at closing?
Often, yes. Jose M. Lorenzo, Jr. takes over Florida probate matters from other lawyers partway through a case, depending on the facts and position of the case, and that is discussed at the consultation. He also represents beneficiaries who want an accounting, a waiver or a release reviewed, as a paid engagement. Call (305) 224-6811 or use the contact page; only the initial consultation is free, and representation fees and costs are agreed separately in writing.
Talk with a Florida probate attorney about closing an estate
If you are a personal representative preparing to close an estate, or a beneficiary reviewing closing papers, call (305) 224-6811 or use the contact page. Have the county, the case number, your role, the latest filing and any service dates available. Jose M. Lorenzo, Jr. takes first calls personally and handles each matter himself.
Consultations are by phone or video statewide, in English or Spanish. Lorenzo Law’s principal office is in Kissimmee; meetings in Coral Gables and Fort Lauderdale are by appointment. For probate elsewhere in Florida, see Florida probate lawyer.
Request a free initial consultation. Only the initial consultation is free; representation fees and costs are agreed separately in writing.
Request a free initial consultationCall (305) 224-6811
This page gives general information about Florida probate law and procedure as of the date shown at the top. It is not legal advice for any estate. Reading it or contacting Lorenzo Law does not create an attorney-client relationship; representation begins only with a signed written engagement.
Sources and a note on the authority cited
Rule text on this page follows the Florida Probate Rules as amended effective October 1, 2026. Statutory figures reflect the 2026 Florida Statutes. Two kinds of figures change from time to time and are worth checking against the current statute before relying on them: the summary administration limit and the compensation schedules.